Graham Real Estate | Savills Partner
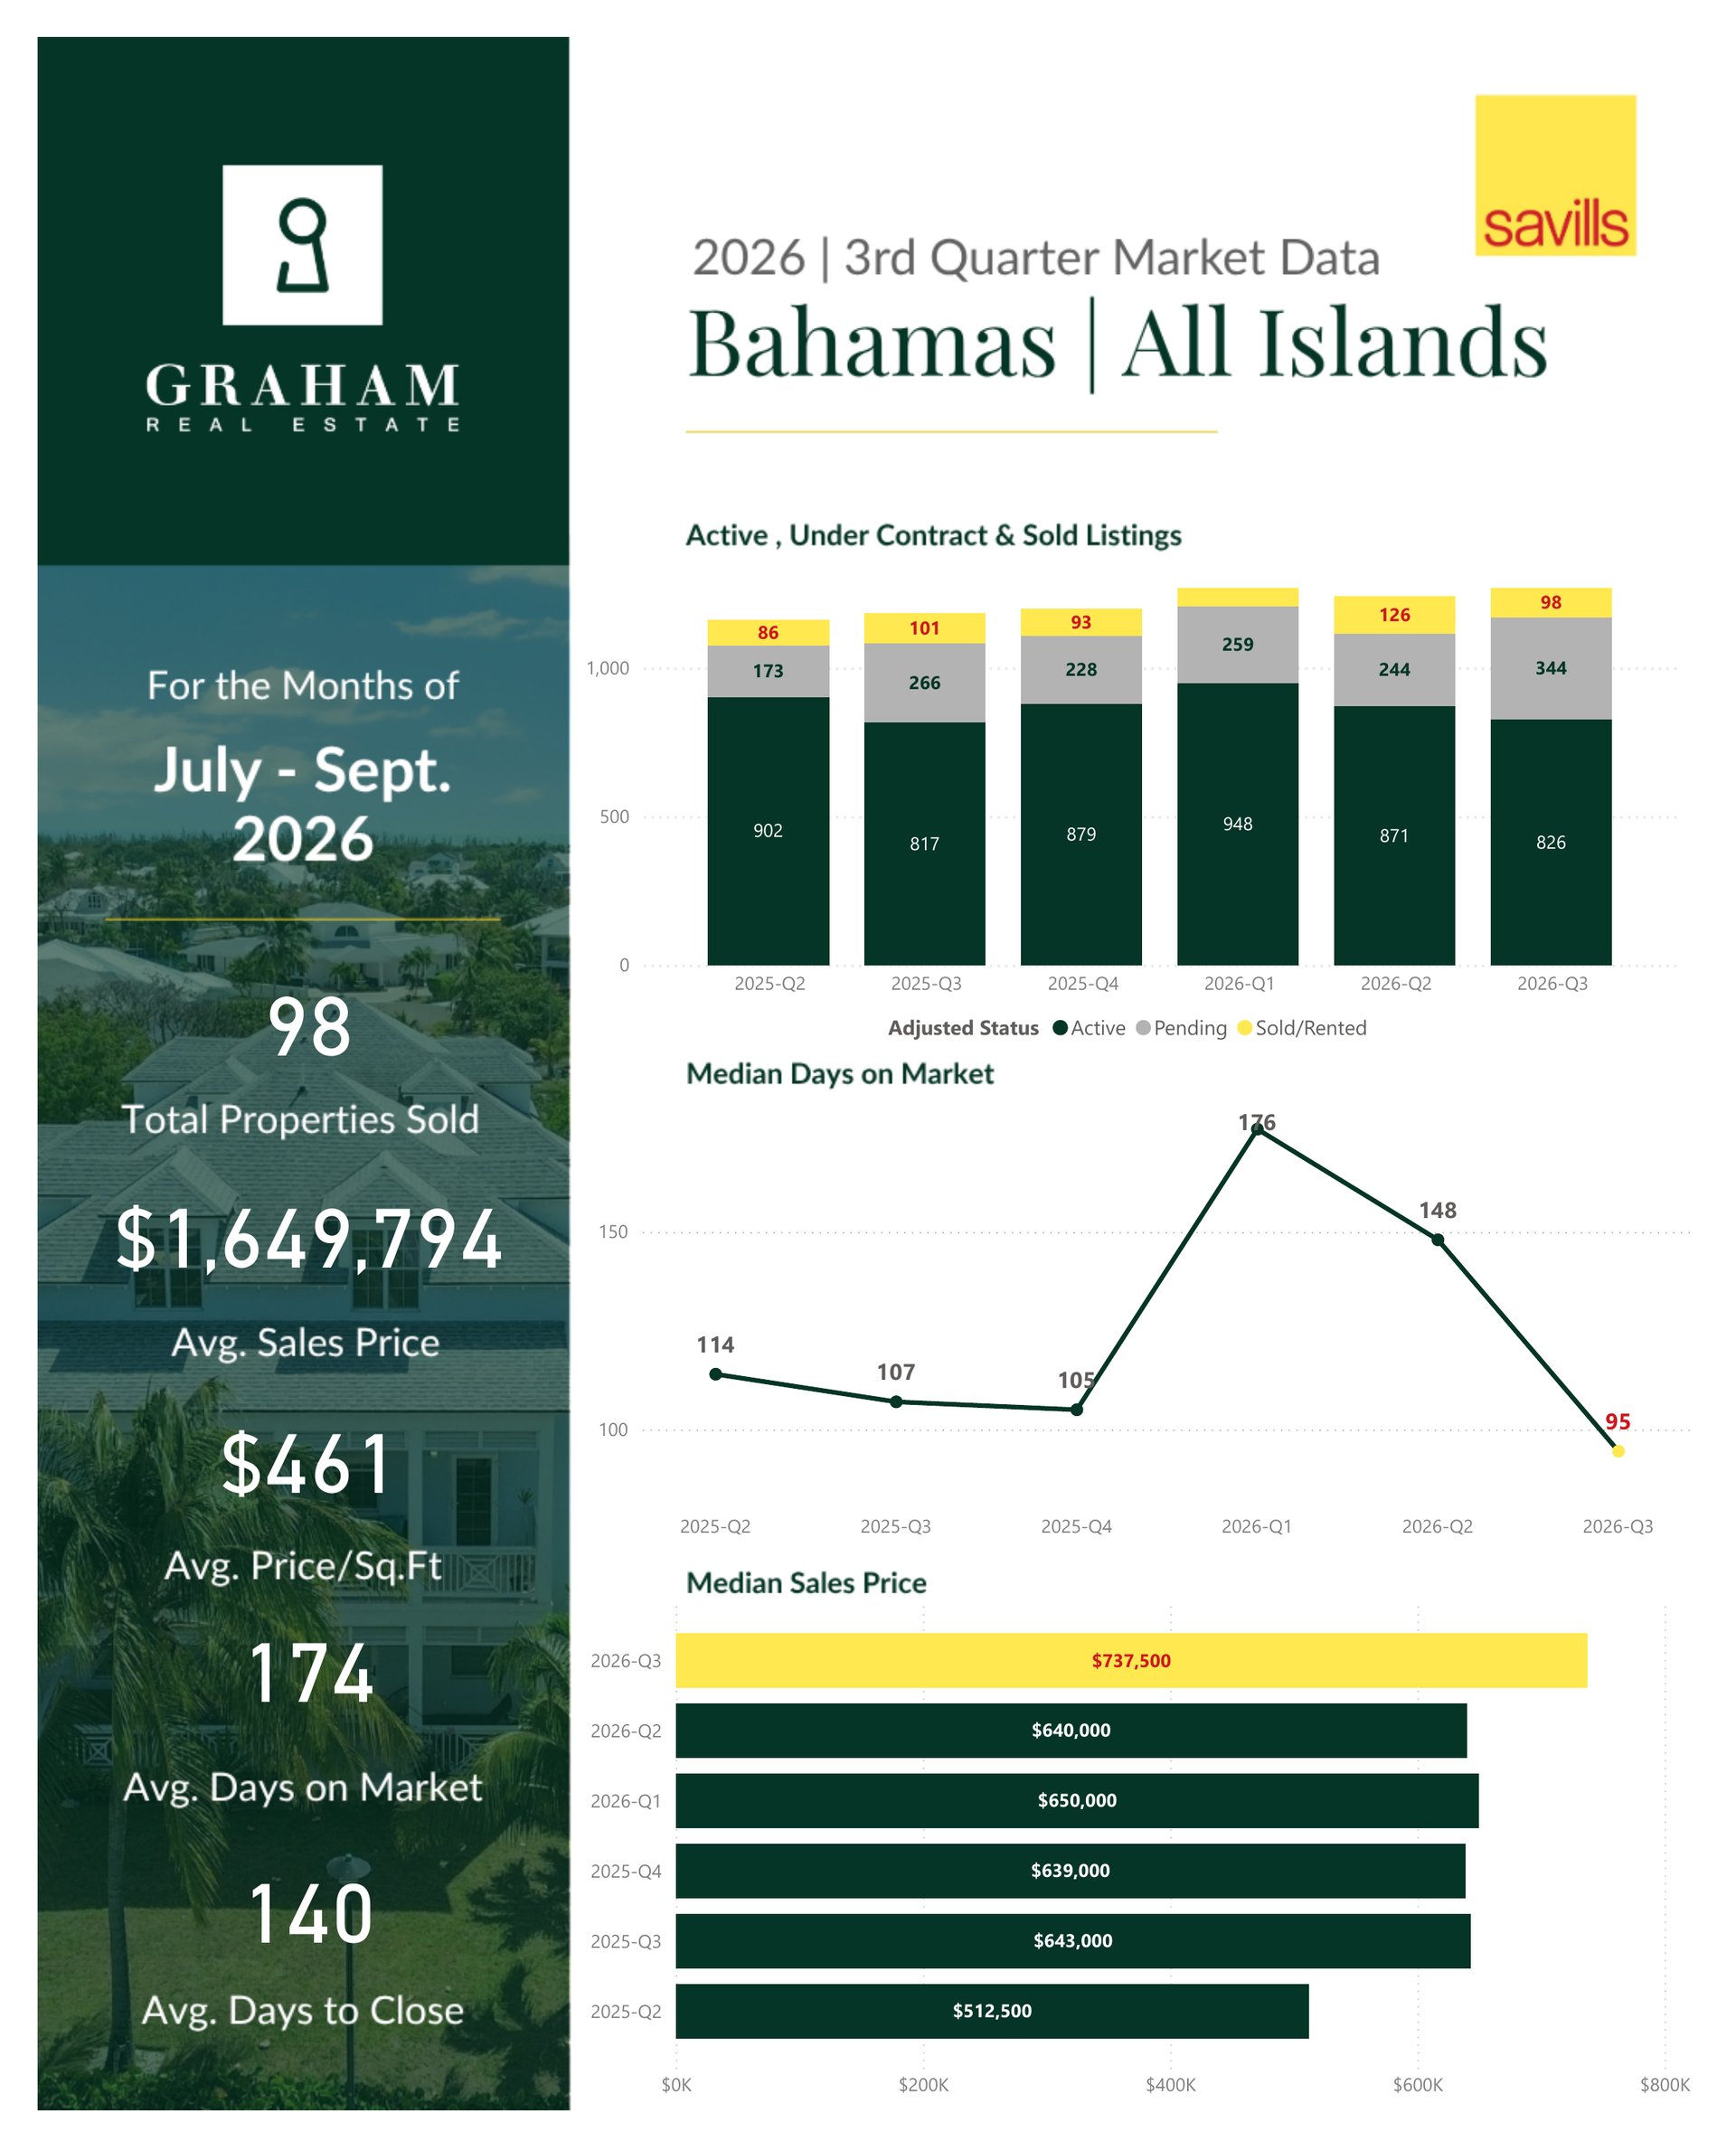
The Bahamian residential real estate market delivered a steady Q3 2026, with pricing strengthening and homes selling faster even as closed sales eased. Closed sales across the Islands we work in eased to 98 from 126 in Q2, broadly level with the 101 recorded in Q3 2025, while the median sales price rose to $737,500 and median days on market improved to 95 days. The stronger signal sits in the pipeline: pending listings climbed to 344, the highest level in six quarters, led by New Providence and Grand Bahama. Higher-value closings in Exuma and New Providence lifted pricing at the top end, while Eleuthera and the Abaco Cays settled back to more typical price points after standout second quarters. The market enters Q4 with strong momentum building beneath the surface.
Market Coverage Note: This report focuses on residential real estate activity on the Islands of Abaco, Eleuthera, Exuma, Grand Bahama, Long Island, and New Providence. Data includes single-family homes, condominiums, apartments, and half duplexes unless otherwise noted. Vacant land is referenced where noted.
GRE Islands
Overall Market: Across the GRE Islands, Q3 2026 saw active listings ease to 826 from 871 in Q2, while pending listings rose to 344 from 244 and closed sales eased to 98 from 126. The average sales price was $1,649,794, with a median of $737,500 and an average price per square foot of $461. Median days on market improved to 95 days, and average days to close came in at 140 days. Closed sales were broadly in line with the 101 recorded in Q3 2025, while the median sales price is up 14.7% from $643,000 a year ago. The pending pipeline, the strongest in six quarters, sets up a busy close to the year.
New Providence
New Providence Overall
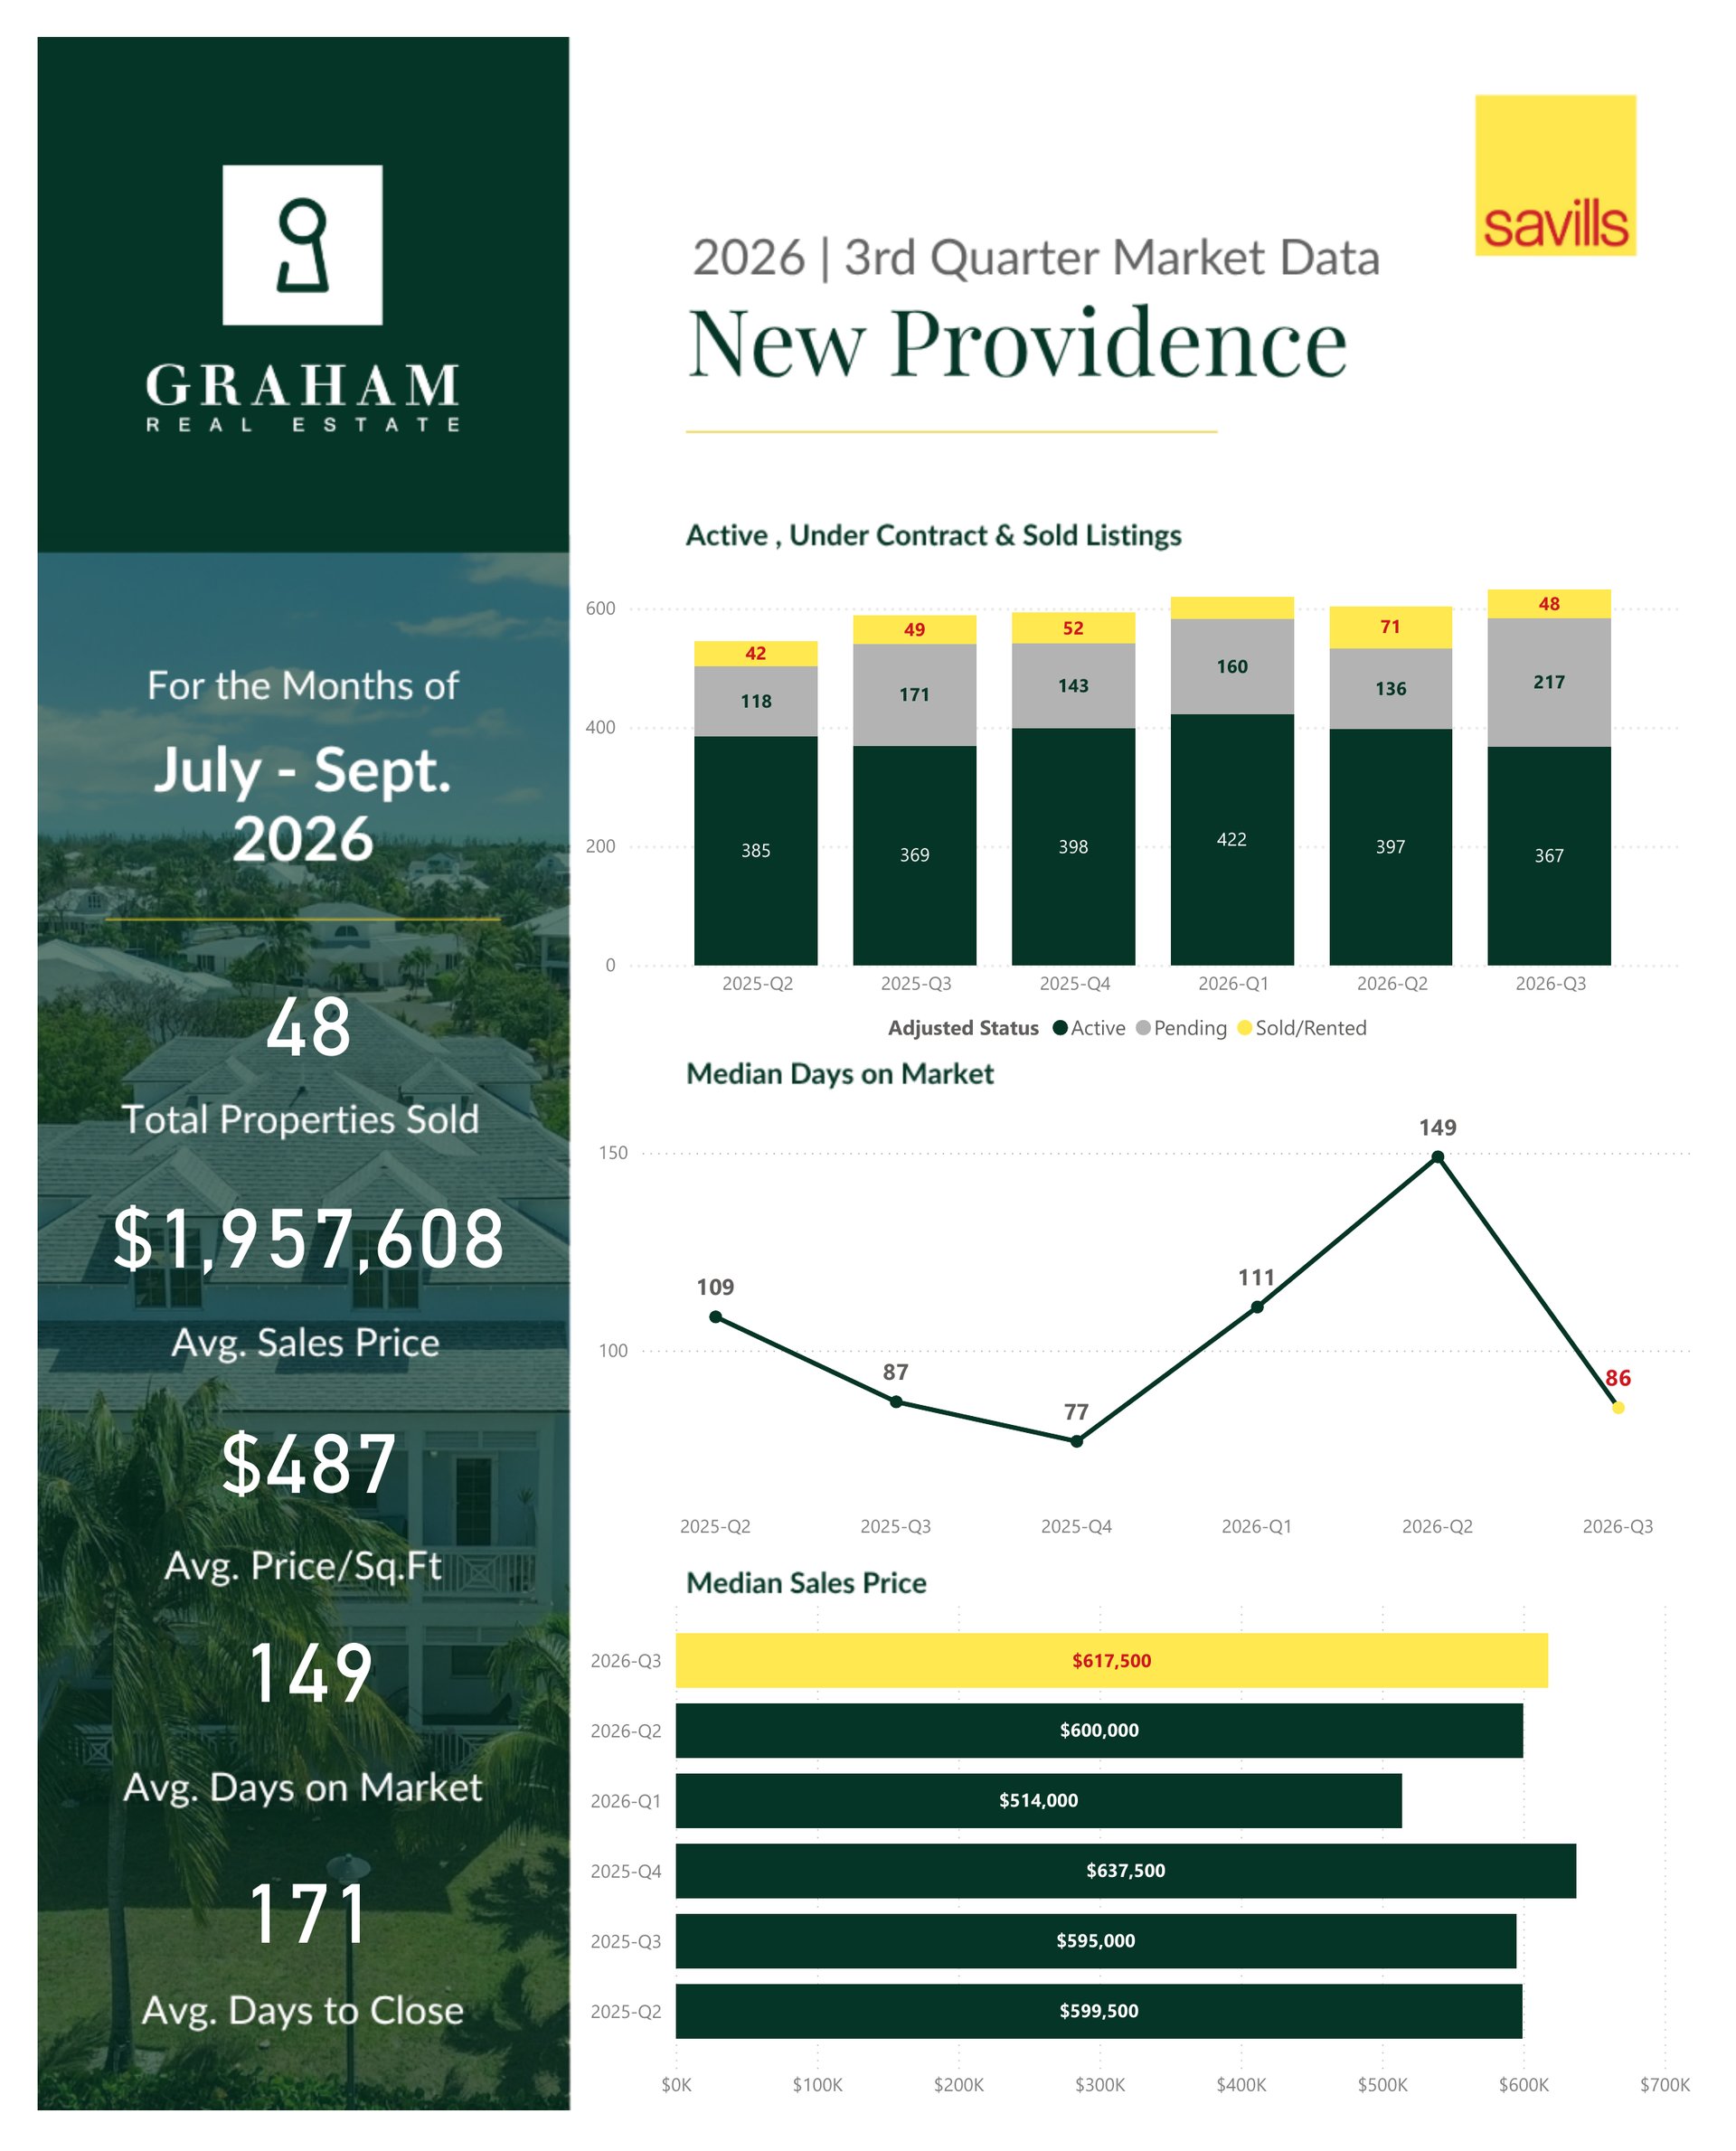
New Providence recorded 367 active listings, 217 pending listings, and 48 closed sales in Q3, down from 71 in Q2 and level with the 49 closed in Q3 2025. The average sales price was $1,957,608, with a median of $617,500 and an average price per square foot of $487. Median days on market improved to 86 days from 149, and average days to close were 171 days. Pending listings rose 60% from 136 in Q2, confirming a healthy pipeline of buyers heading into Q4.
Eastern Road
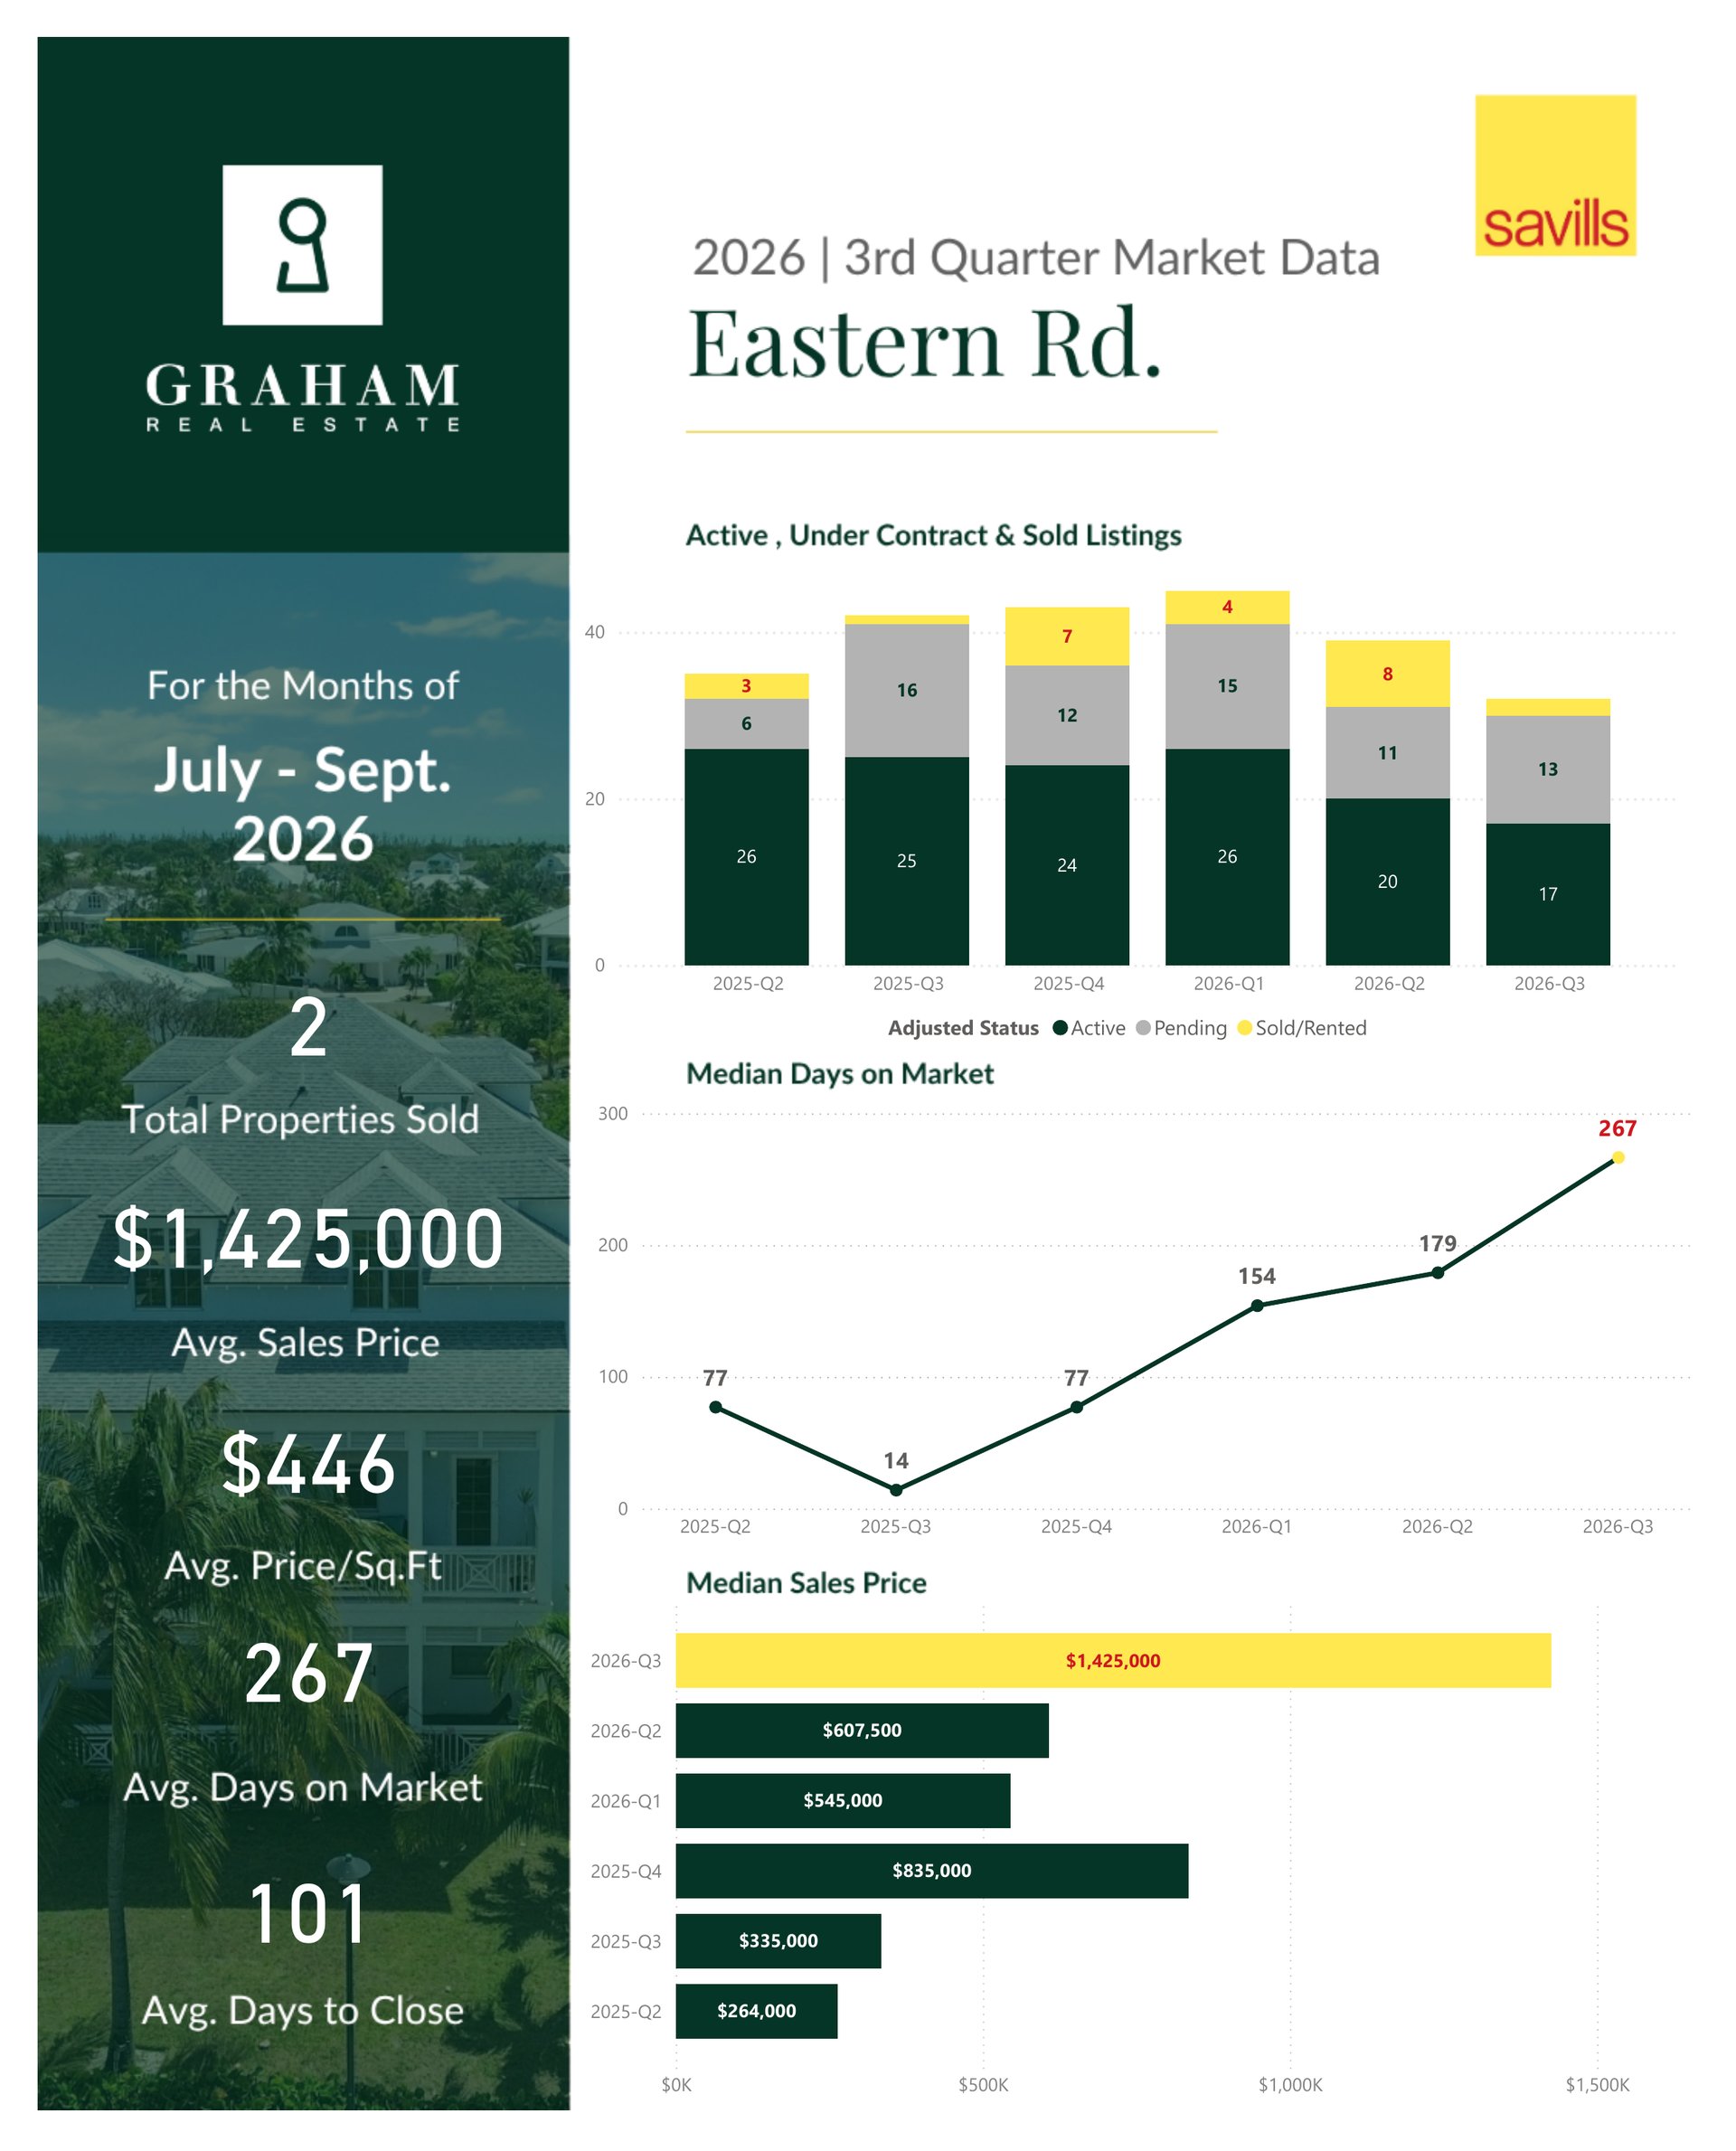
Eastern Road recorded 17 active listings, 13 pending listings, and 2 closed sales in Q3. The average and median sales price both came in at $1,425,000, with an average price per square foot of $446. Median days on market were 267 days and average days to close 101 days. With activity limited to two transactions, results should be read with caution, though the 13 pending listings, up from 11 in Q2, point to a pickup in Q4.
Port New Providence & Palm Cay
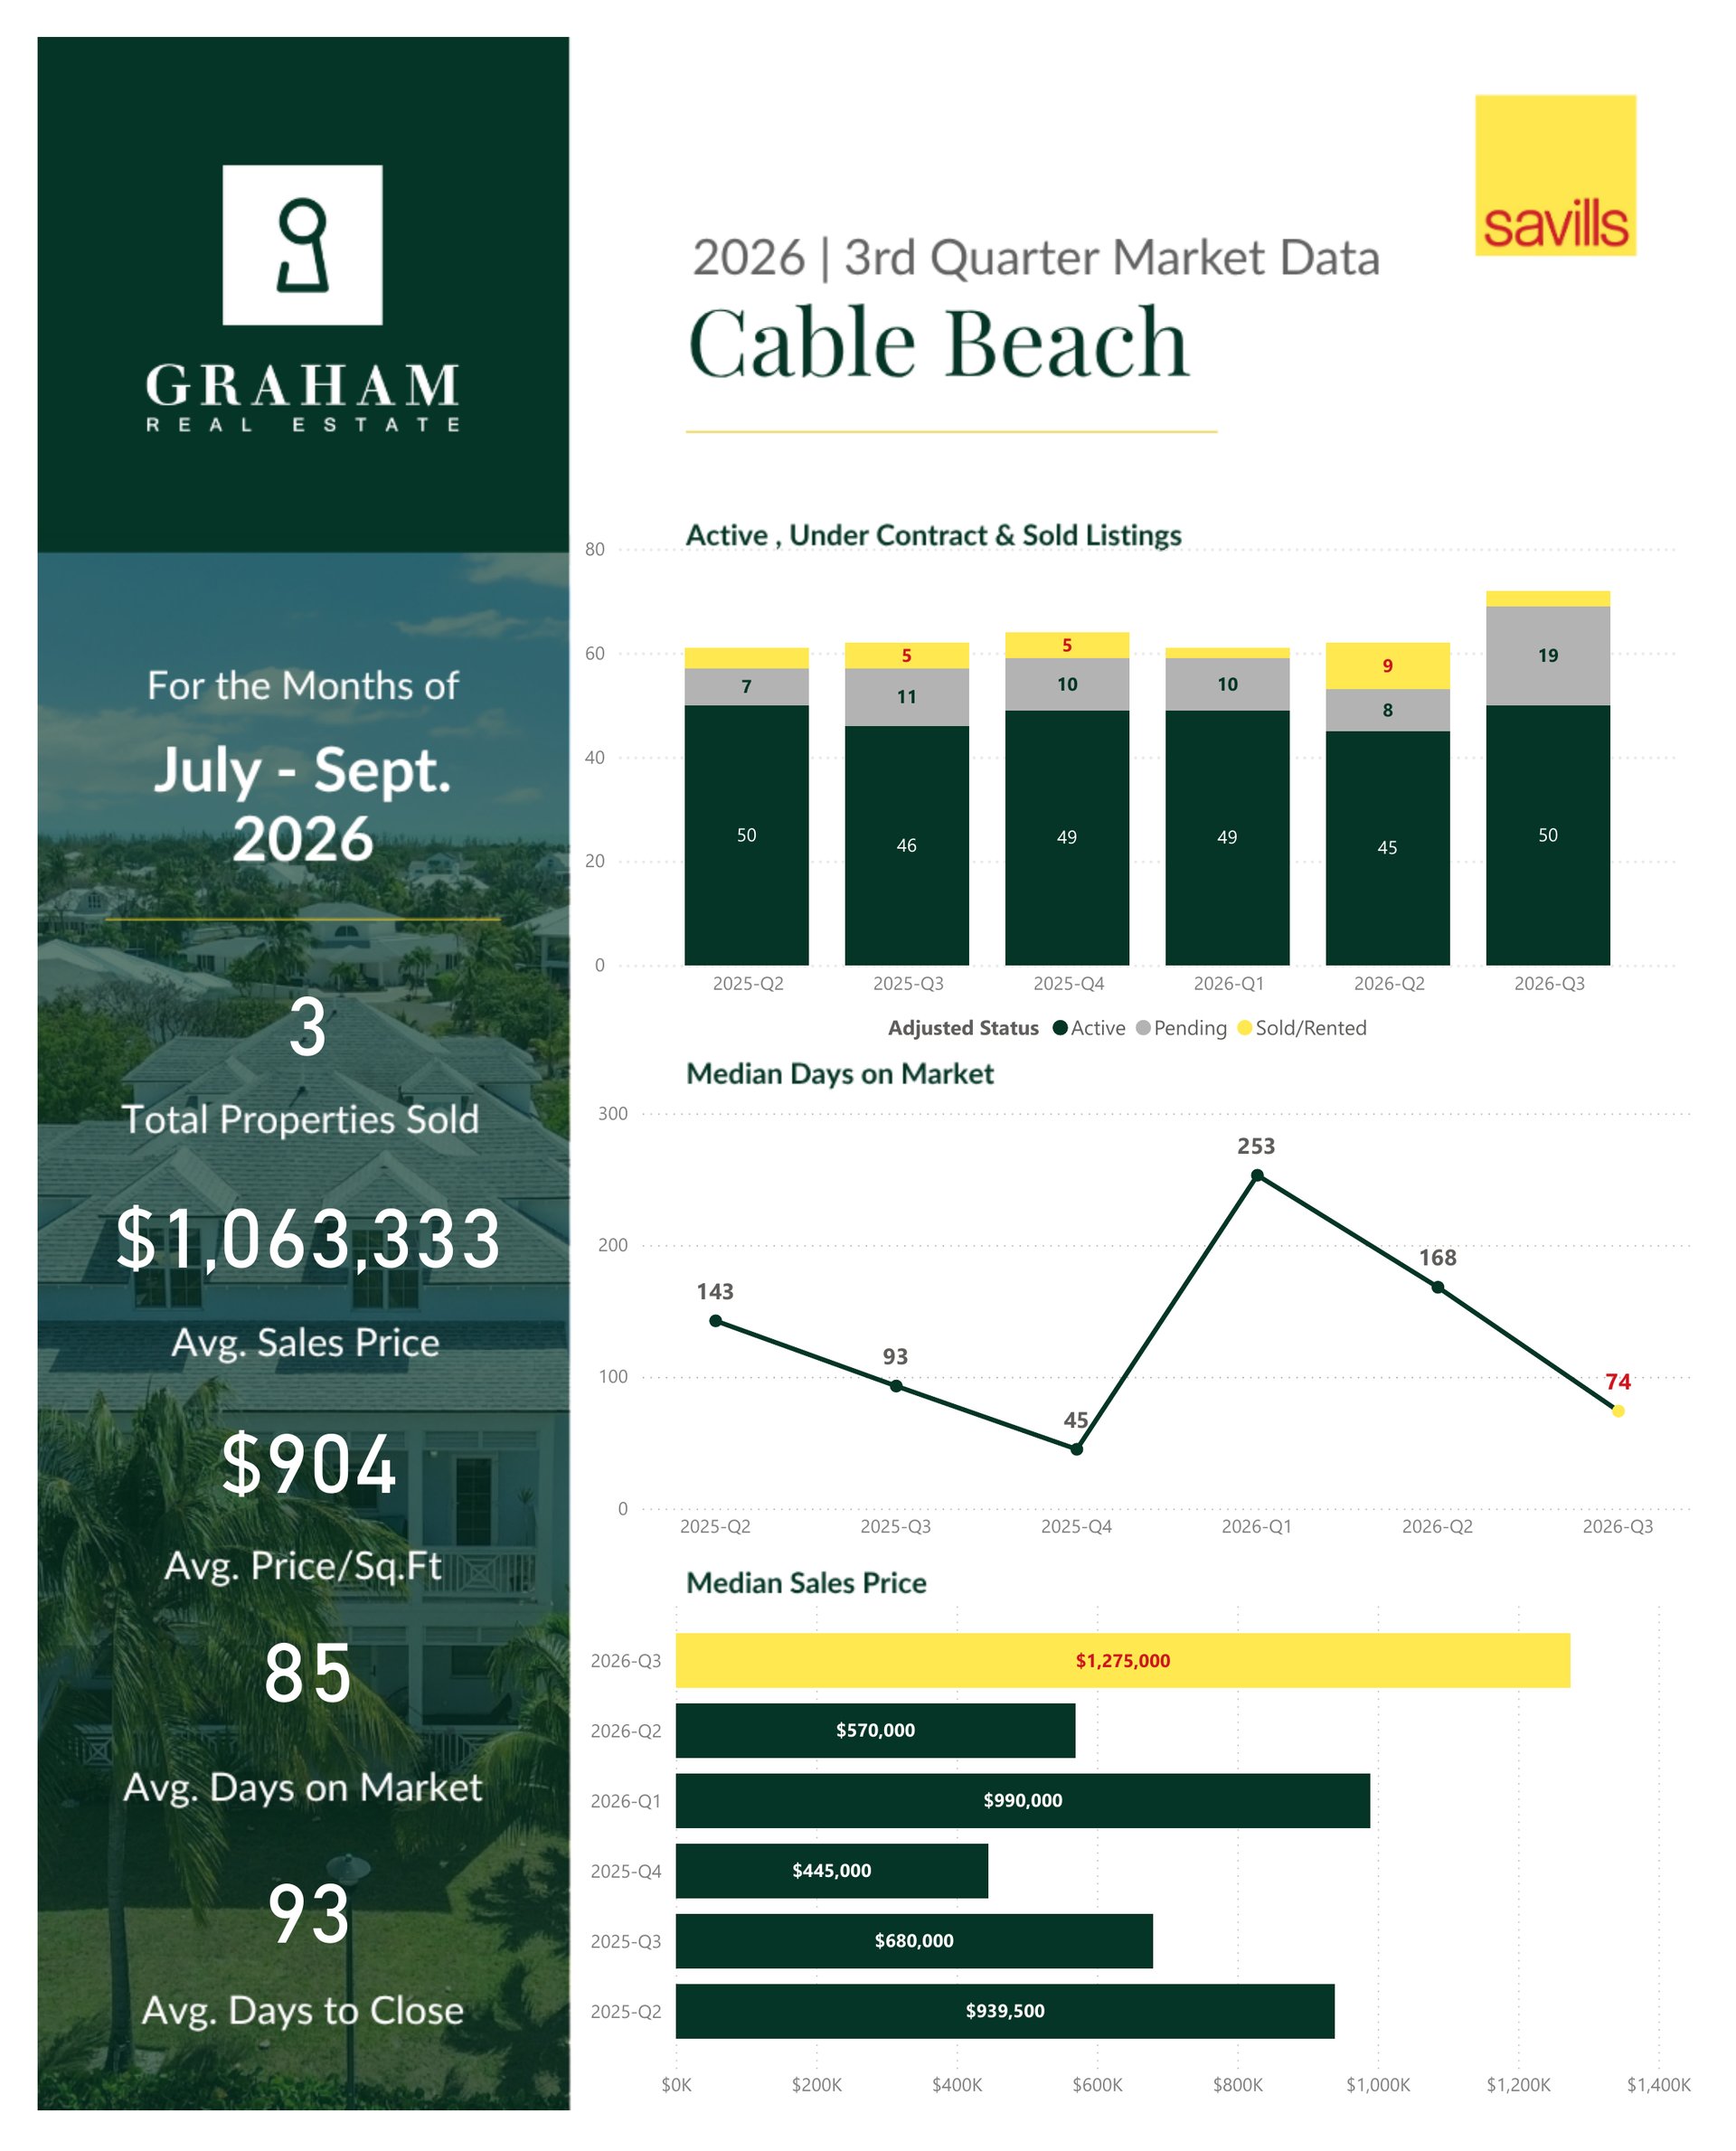
Port New Providence and Palm Cay recorded 31 active listings and 5 pending listings in Q3, with no closed sales during the quarter, compared with 4 closed sales in Q2. Active inventory rose from 27 listings in Q2, while pending listings increased from 3 to 5. Because pending listings typically convert to closed sales in the following quarter, the 5 properties now under contract point to a return of closed activity in Q4. Submarkets of this size can move from quarter to quarter on a handful of transactions, and the pipeline suggests buyer interest remains consistent.
Cable Beach
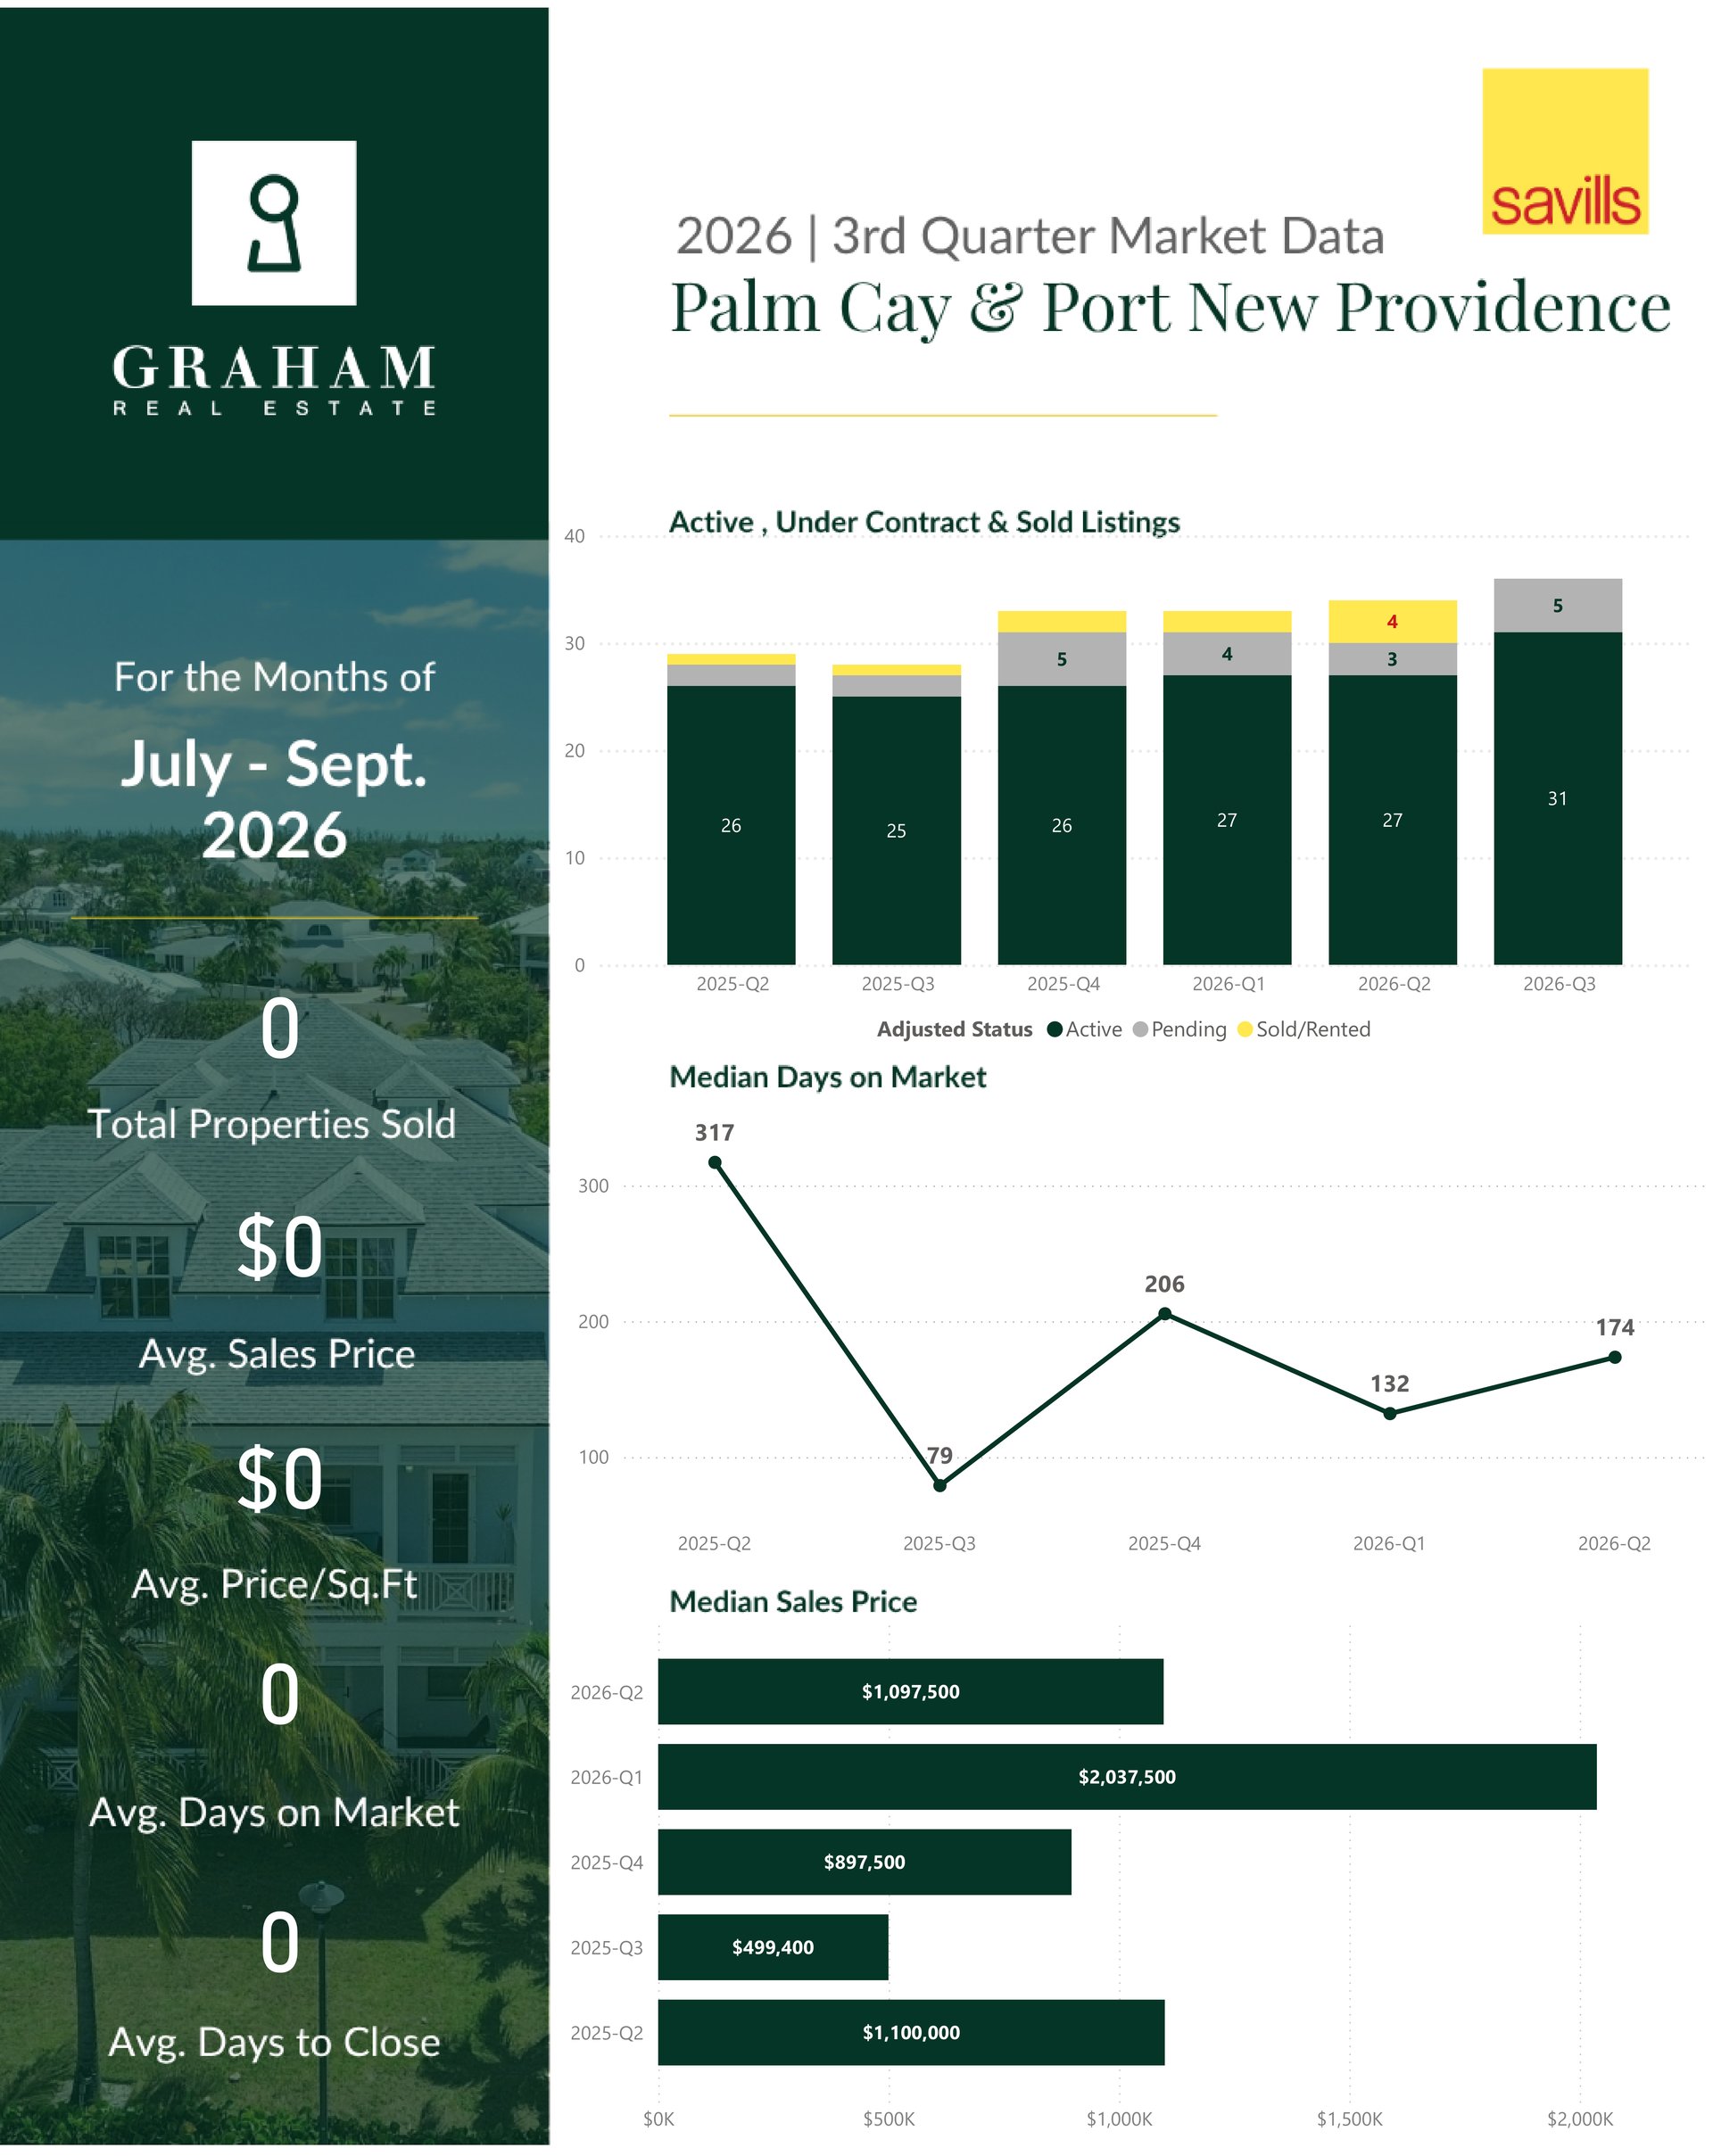
Cable Beach recorded 50 active listings, 19 pending listings, and 3 closed sales in Q3, down from 9 in Q2. The average sales price was $1,063,333, with a median of $1,275,000 and an average price per square foot of $904. Median days on market improved to 74 days from 168 and average days to close were 93 days. Pending listings more than doubled from 8 in Q2, signalling renewed buyer activity.
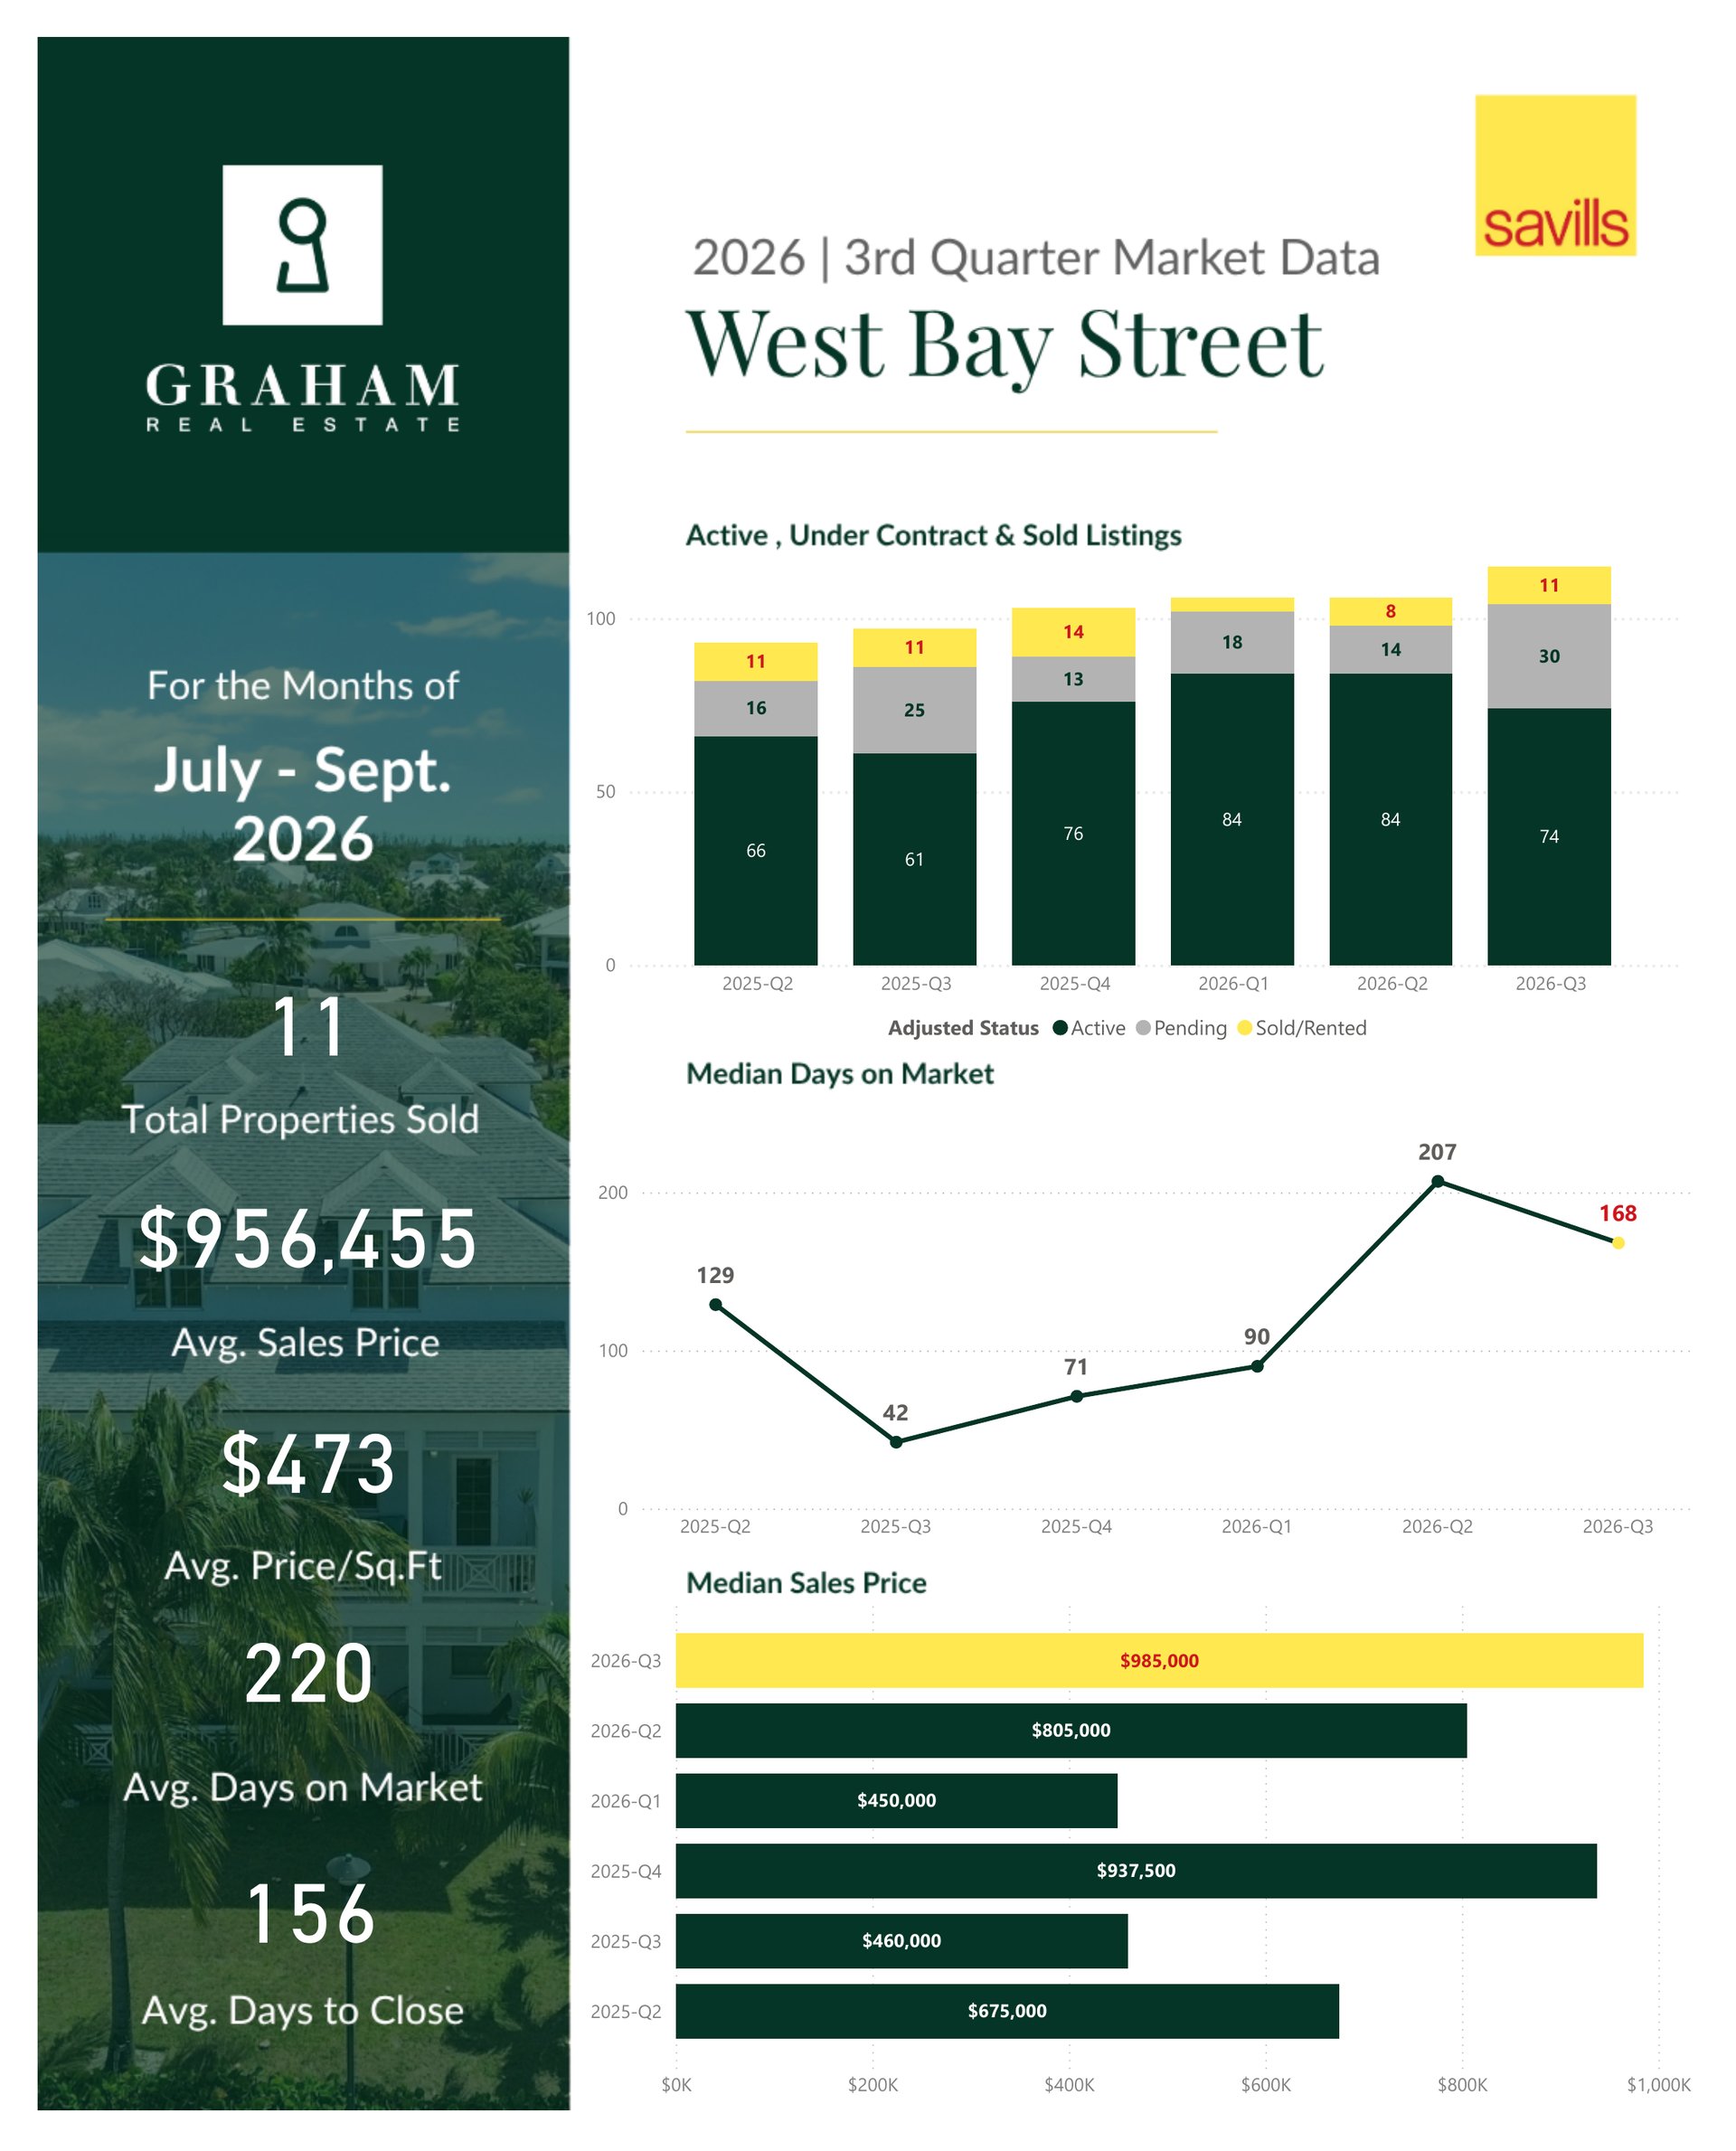
West Bay Street
West Bay Street recorded 74 active listings, 30 pending listings, and 11 closed sales in Q3, up from 8 in Q2. The average sales price was $956,455, with a median of $985,000 and an average price per square foot of $473. Median days on market were 168 days and average days to close 156 days. The median sales price rose 22% from $805,000 in Q2, and pending listings more than doubled from 14 to 30.
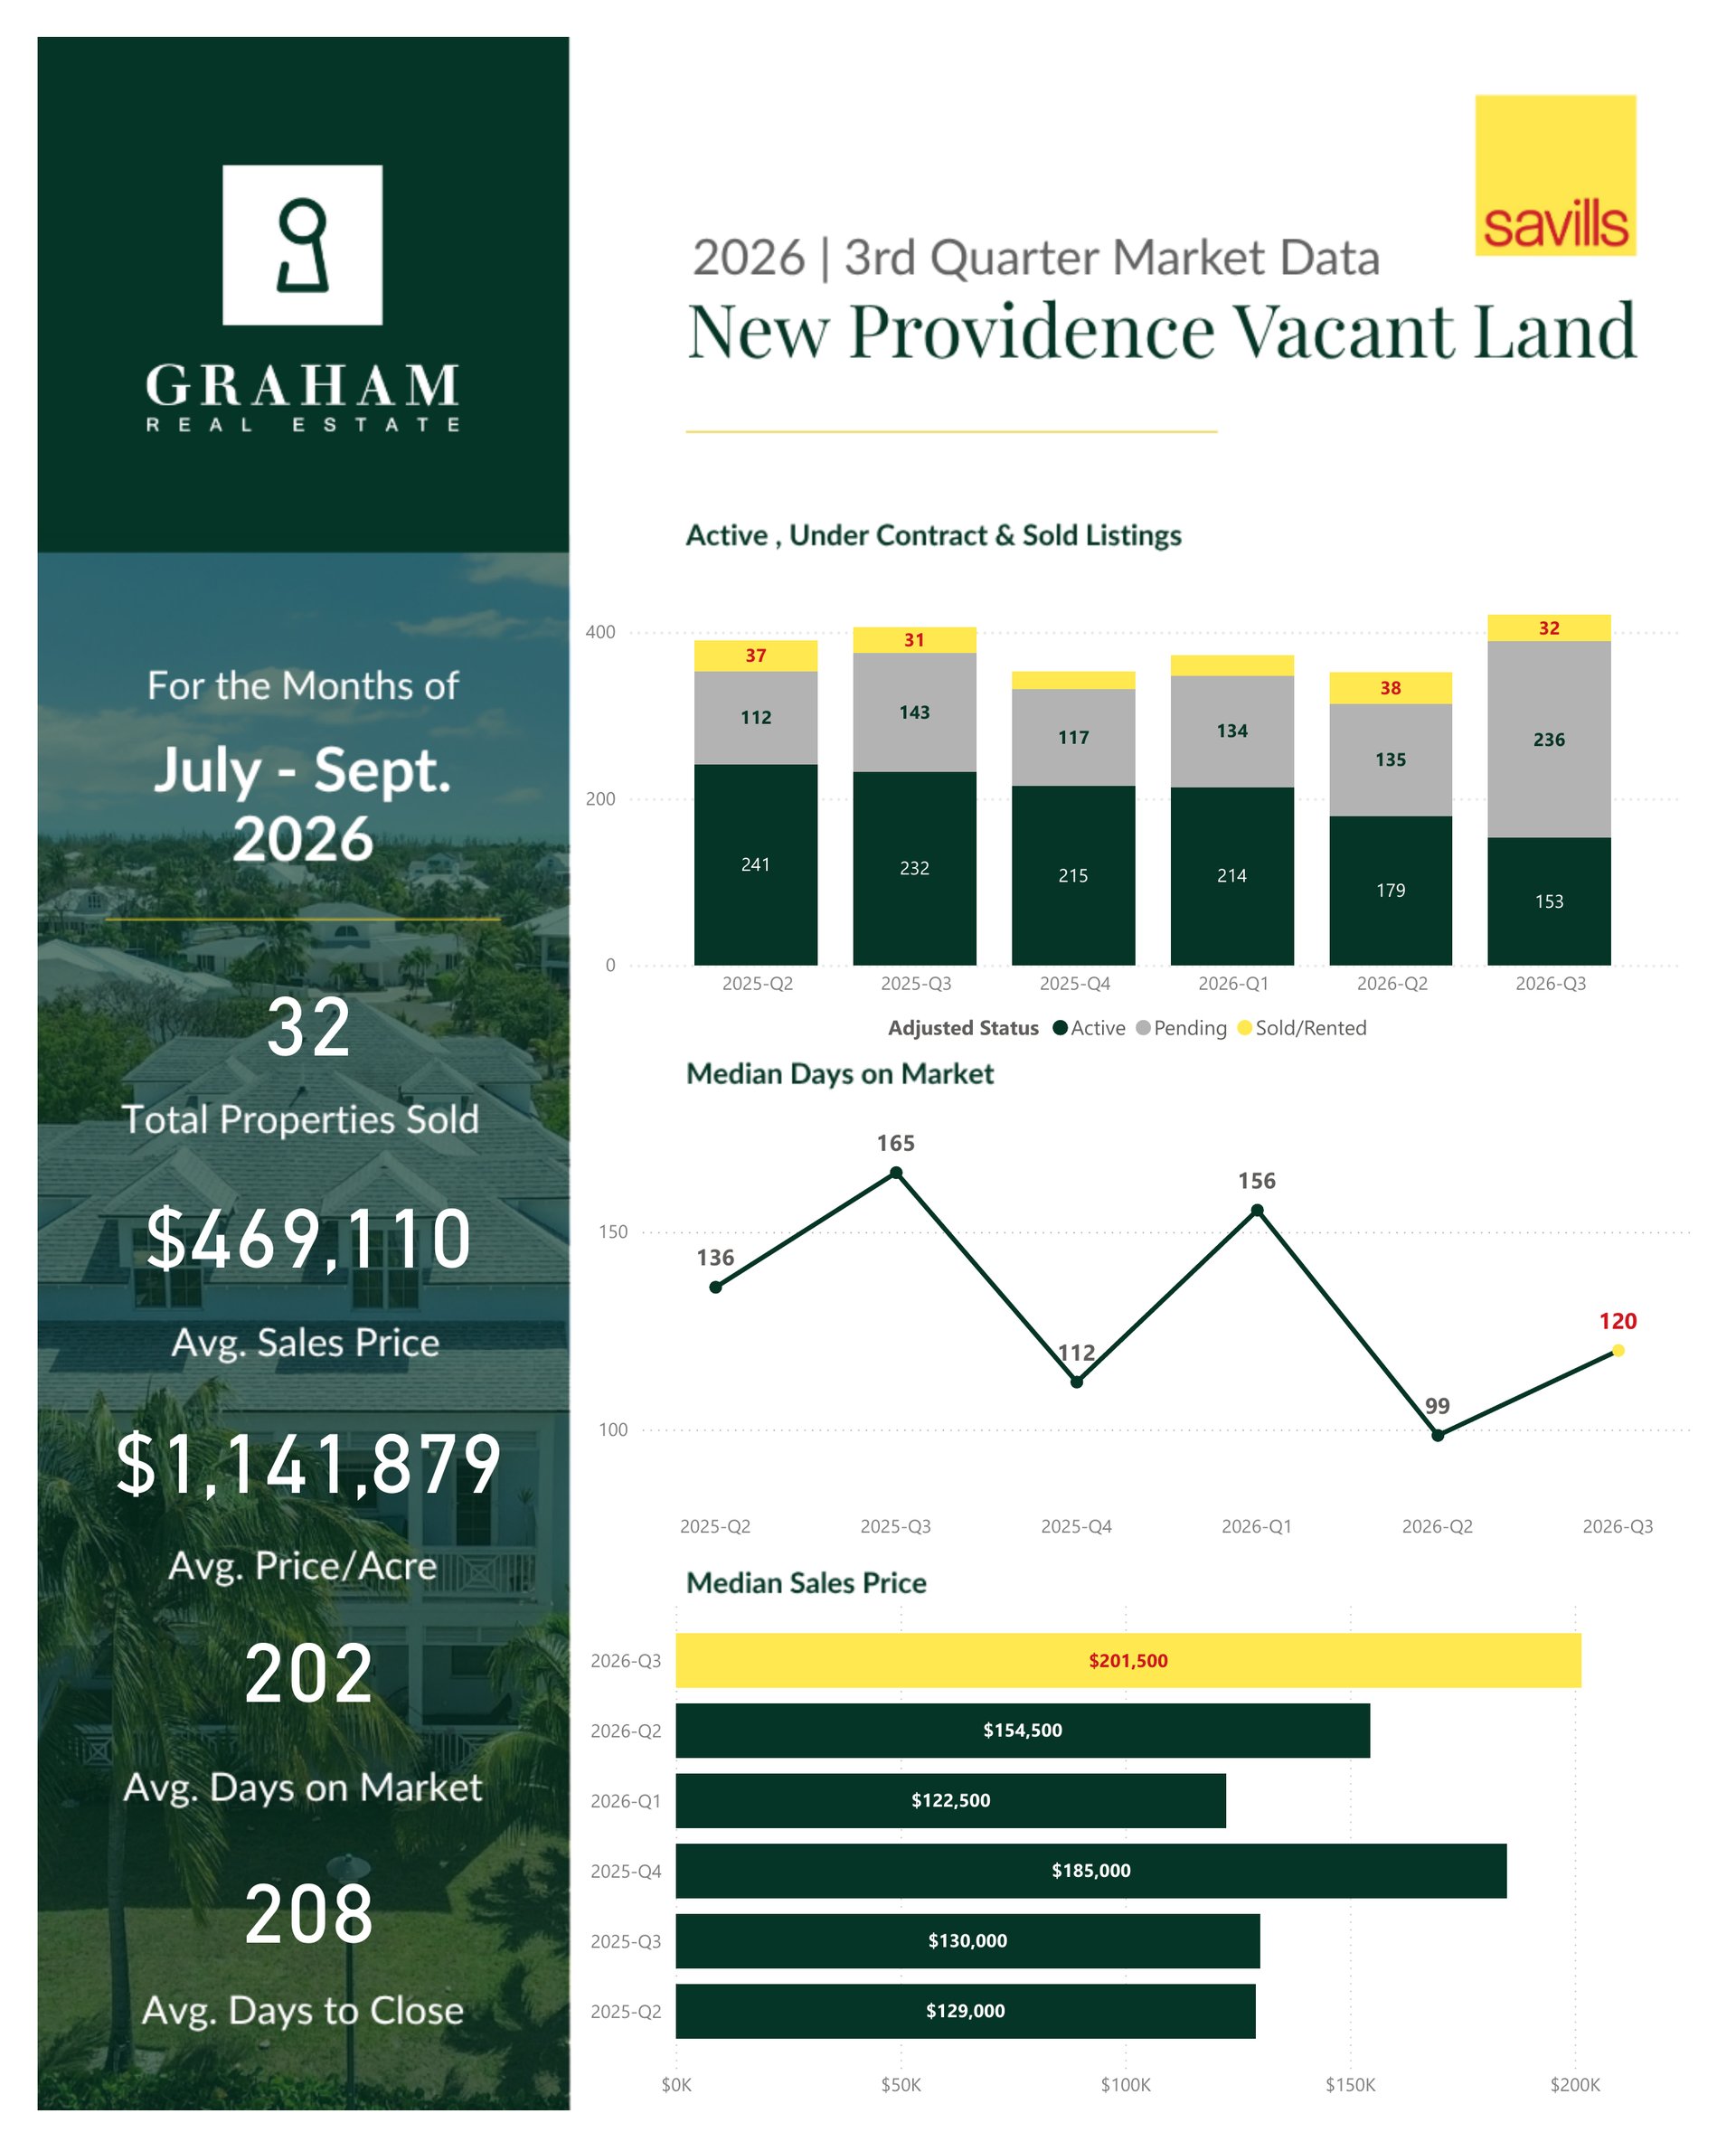
New Providence Vacant Land
New Providence land recorded 153 active listings, 236 pending listings, and 32 closed sales in Q3, down from 38 in Q2. The average sales price was $469,110, with a median of $201,500 and an average price per acre of $1,141,879. Median days on market were 120 days and average days to close 208 days. Pending listings climbed to 236 from 135 in Q2 and now exceed active inventory, while the median sales price rose 30% from $154,500, signalling continued momentum heading into Q4.
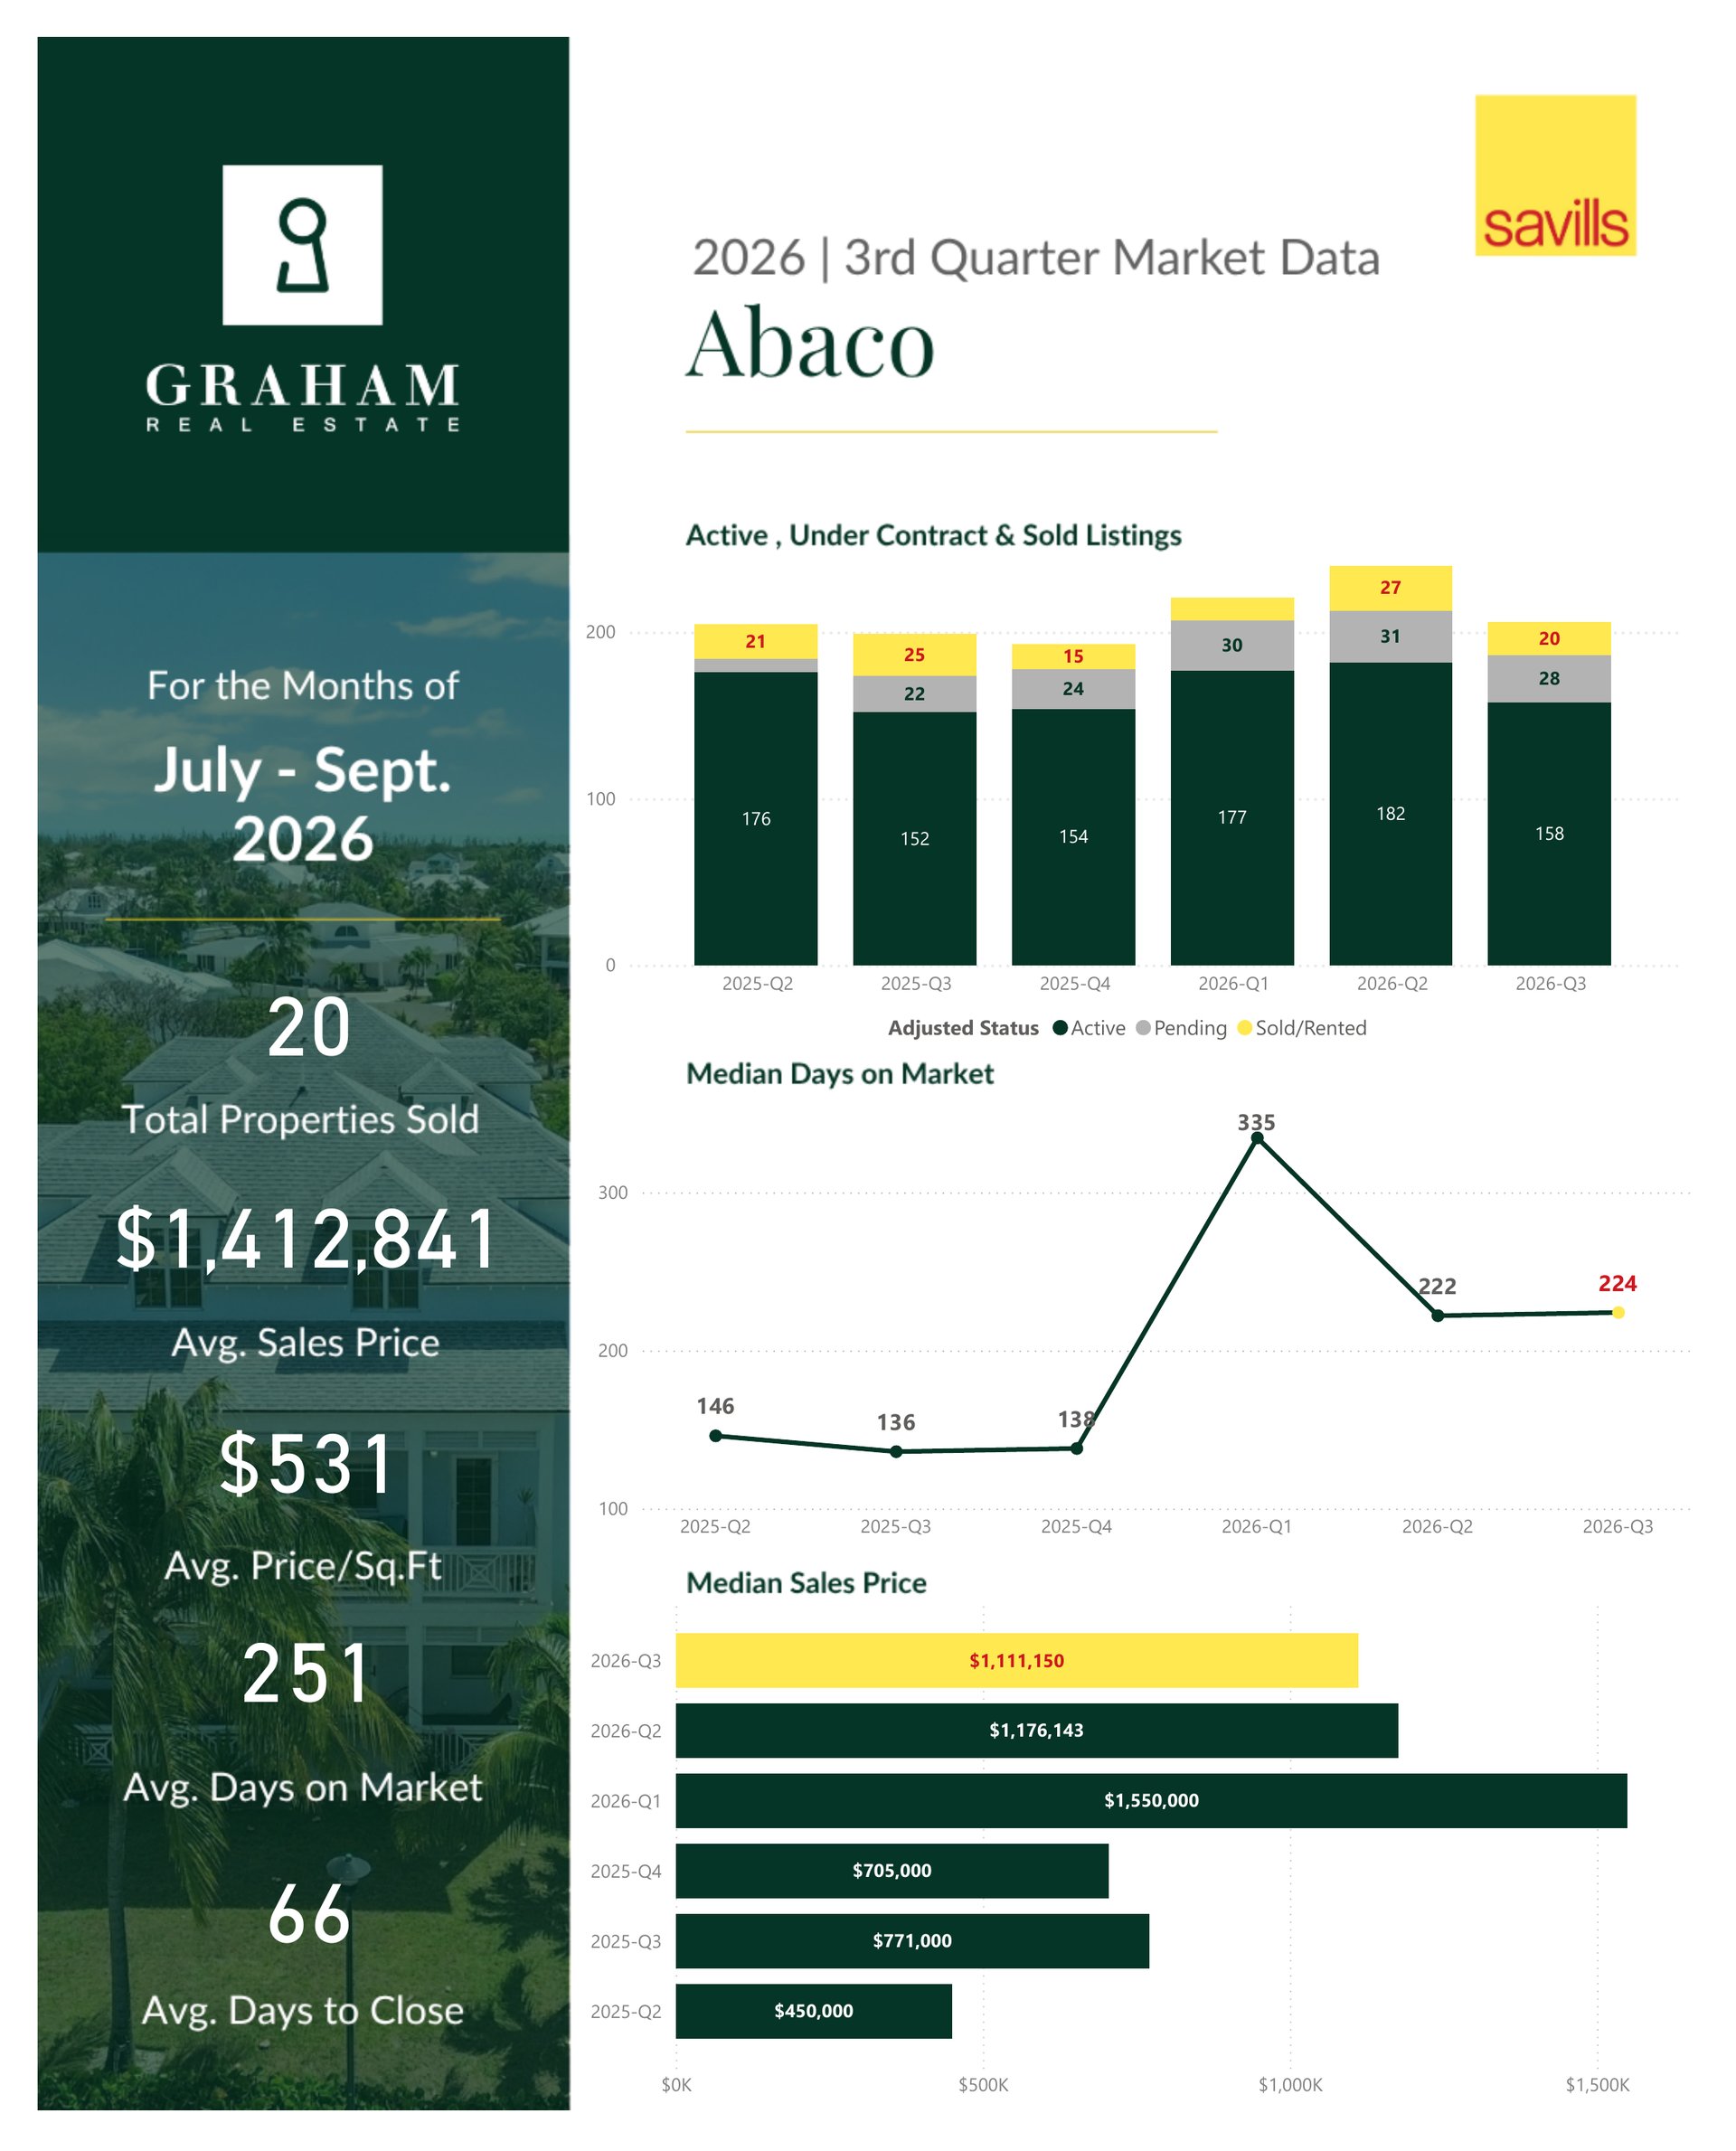
Abaco
Abaco recorded 158 active listings, 28 pending listings, and 20 closed sales in Q3, down from 27 in Q2. The average sales price was $1,412,841, with a median of $1,111,150 and an average price per square foot of $531. Median days on market were 224 days and average days to close 66 days, down from 100 in Q2. Median pricing remained above $1.1 million, within 6% of Q2 and well ahead of the $771,000 recorded in Q3 2025, with faster closing timelines reflecting committed buyers.
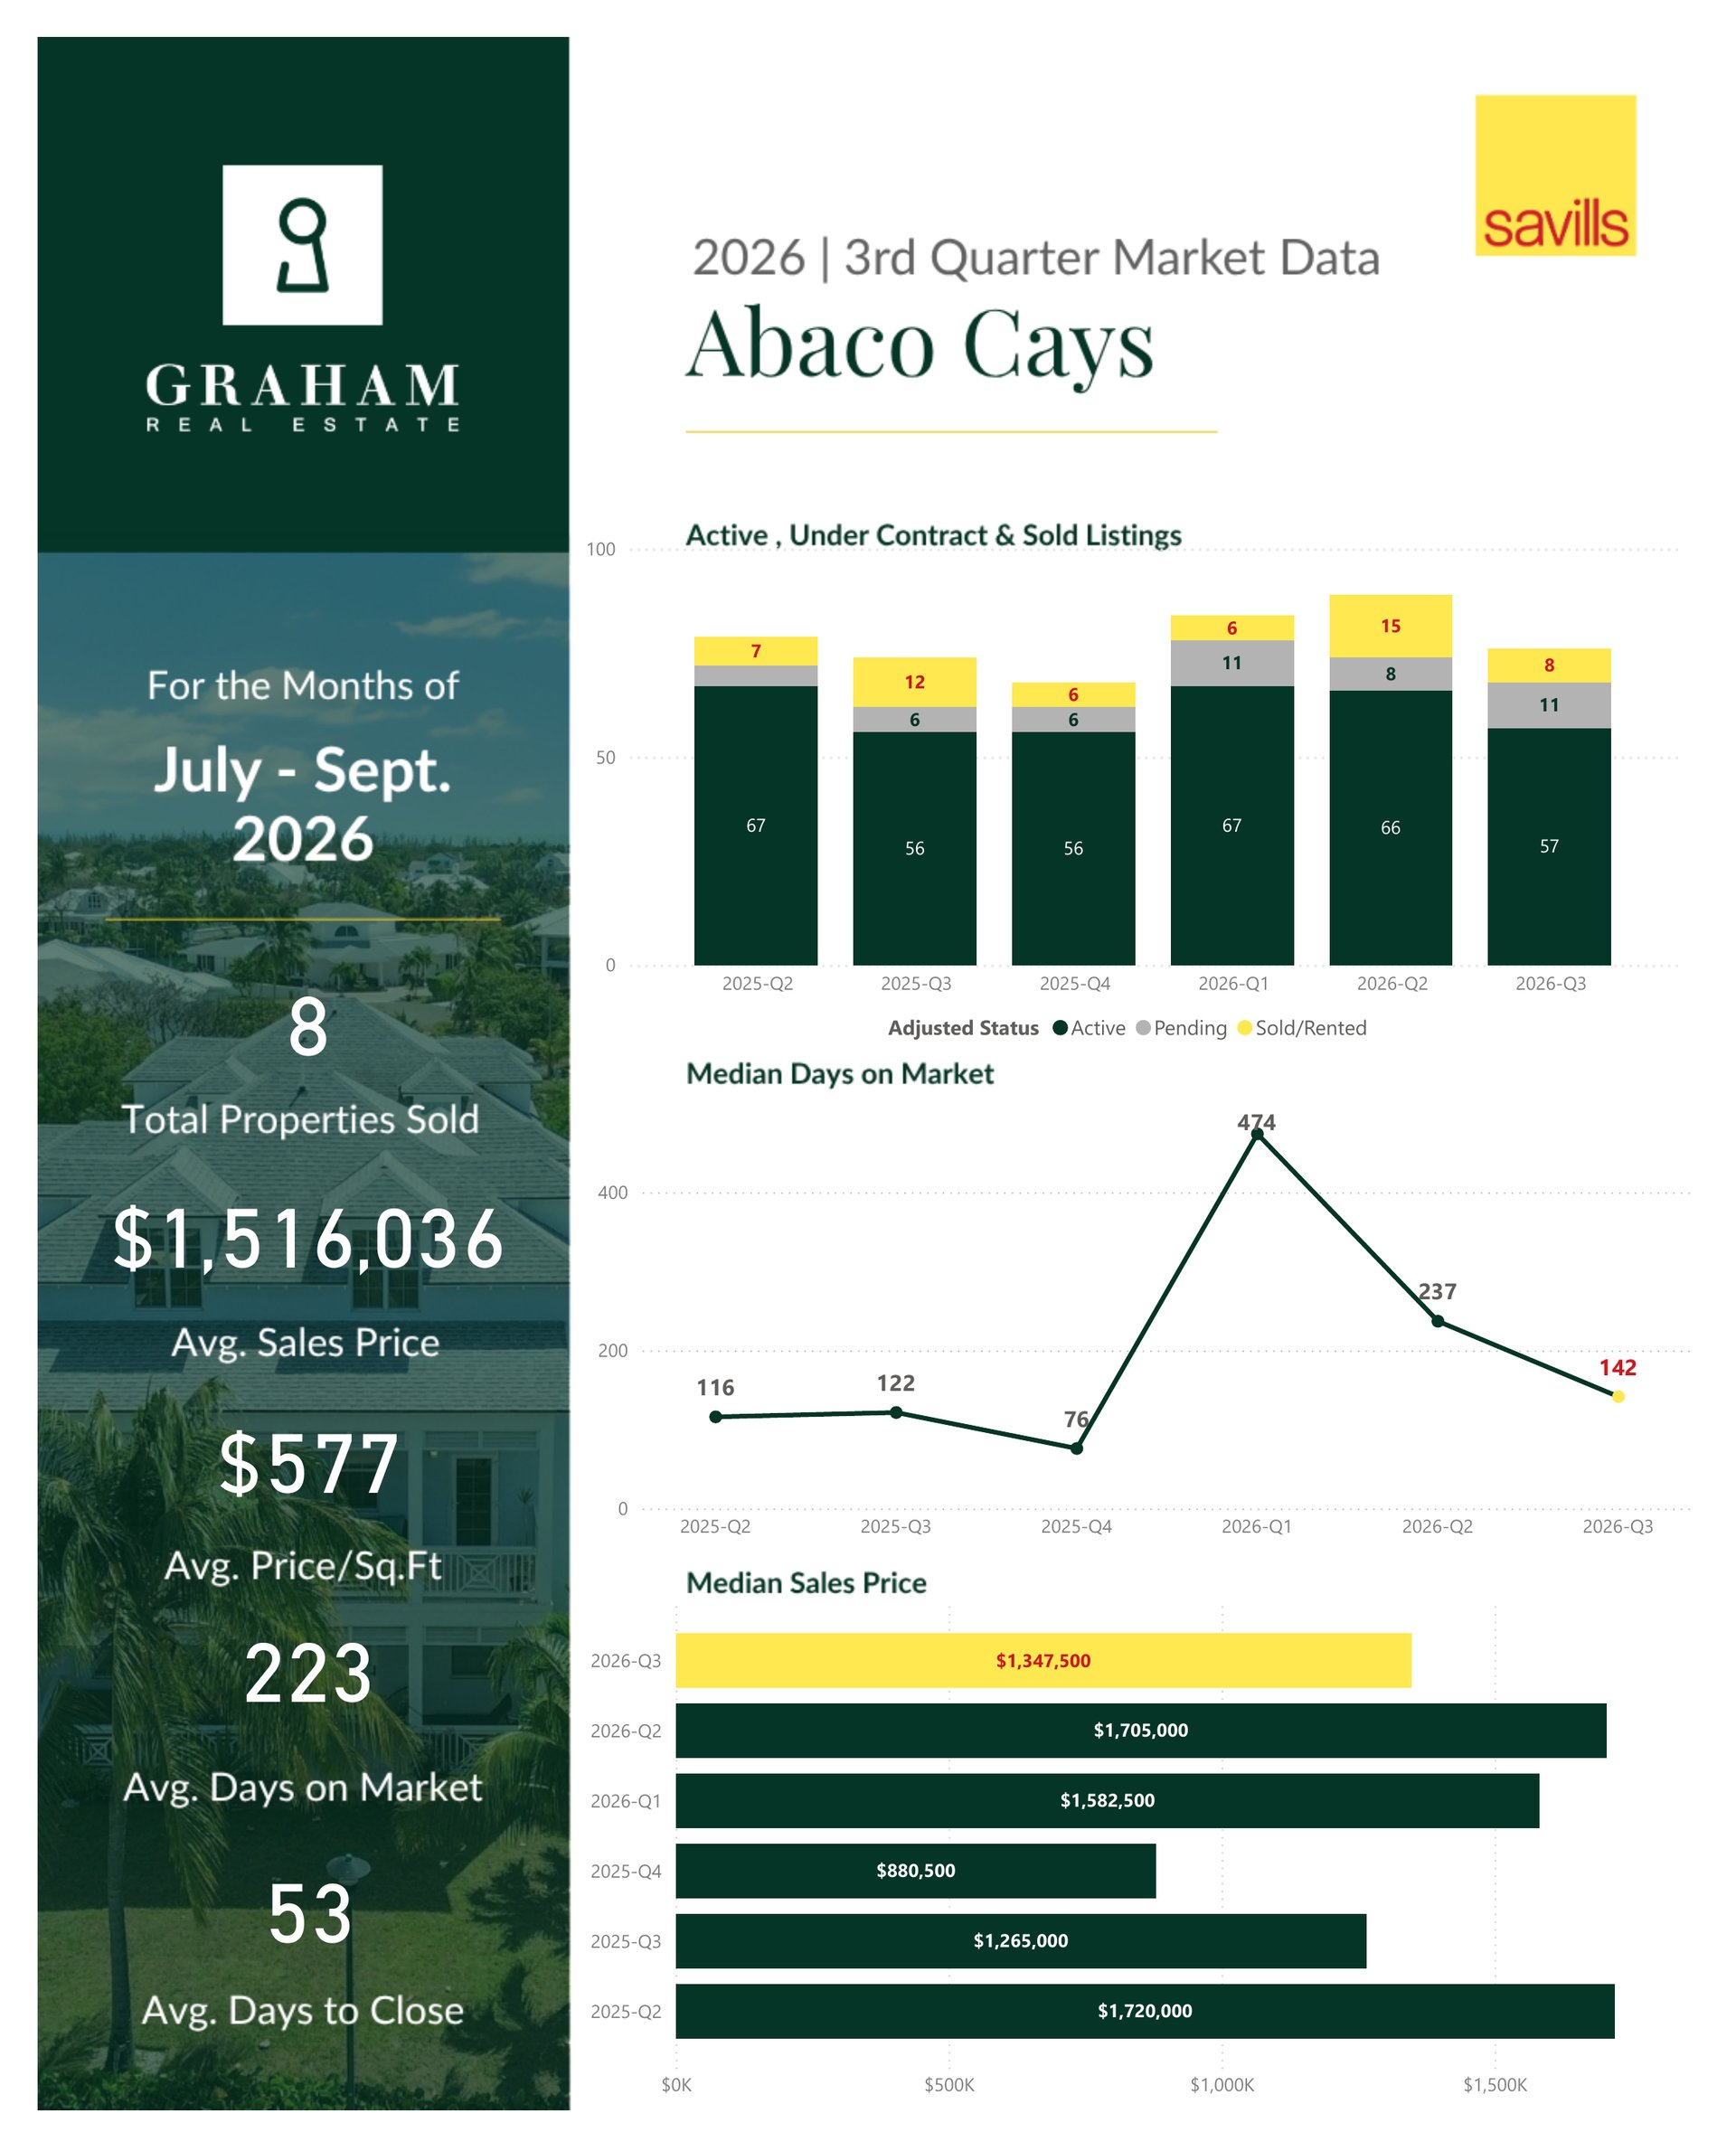
Abaco Cays
The Abaco Cays recorded 57 active listings, 11 pending listings, and 8 closed sales in Q3, down from 15 in Q2. The average sales price was $1,516,036, with a median of $1,347,500 and an average price per square foot of $577. Median days on market improved to 142 days from 237 and average days to close came in at 53 days. Pricing eased from the standout levels of Q2 but remains above the $1,265,000 median recorded in Q3 2025.
Treasure Cay
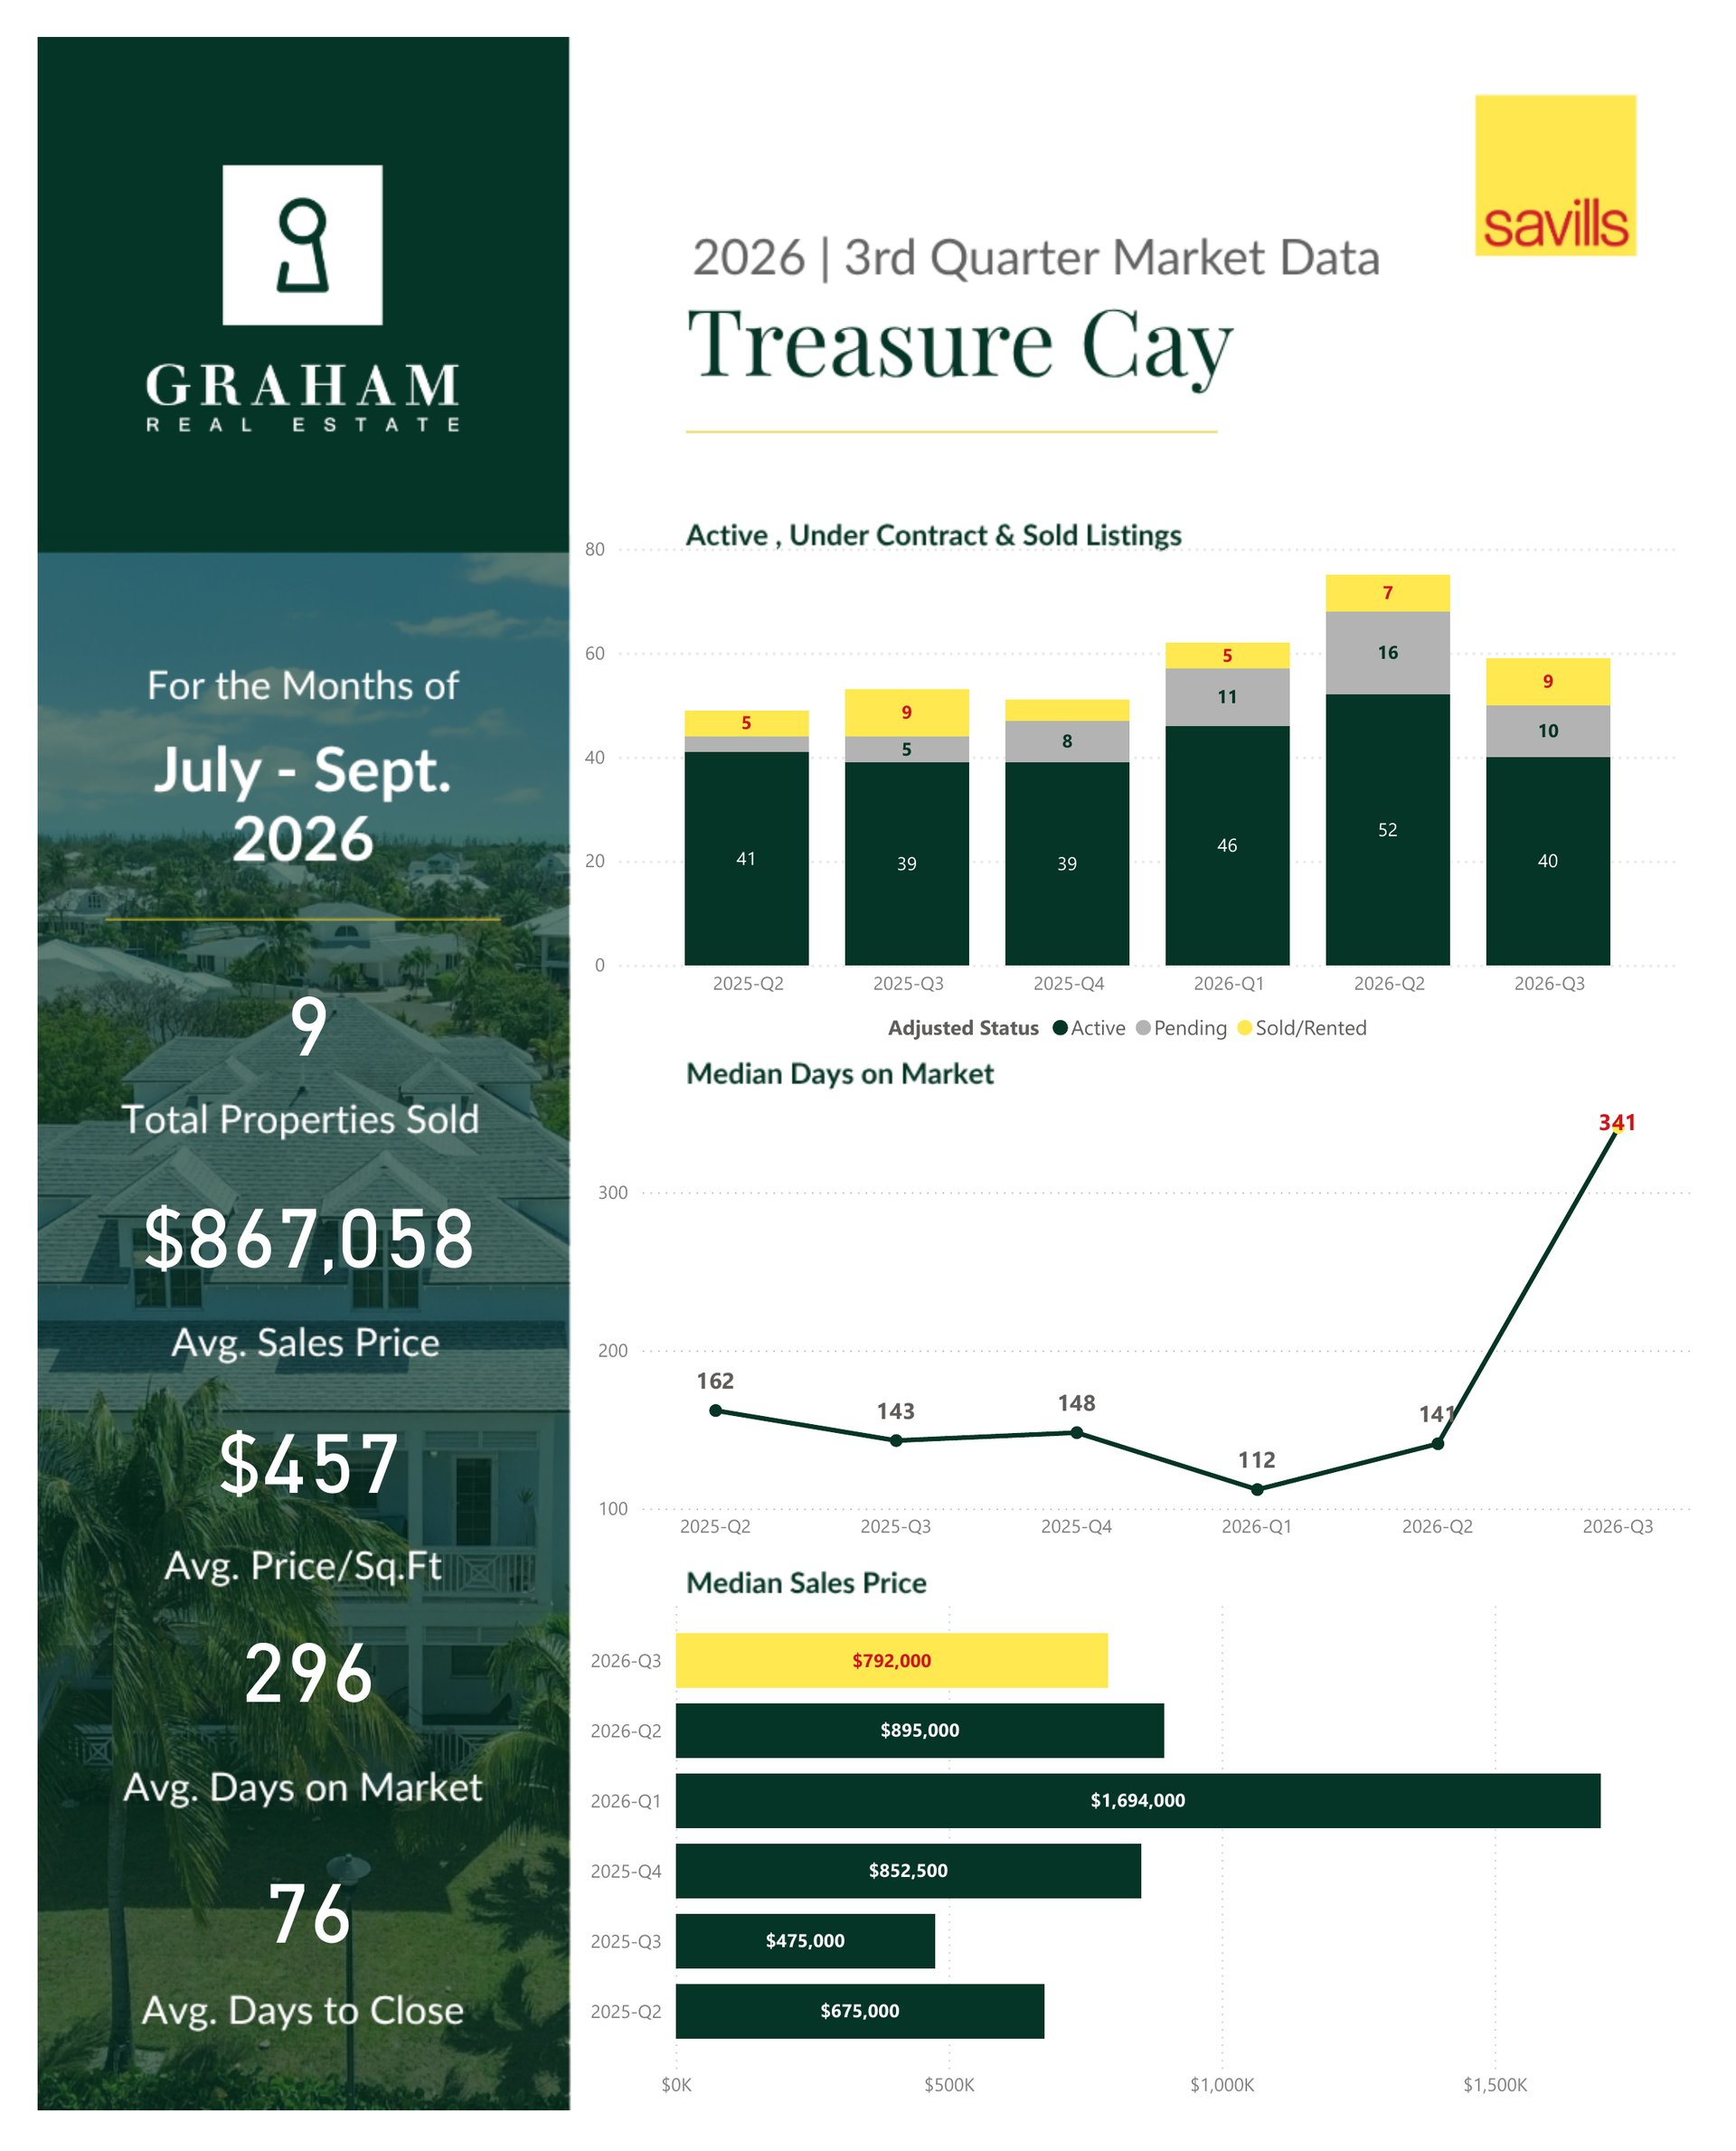
Treasure Cay recorded 40 active listings, 10 pending listings, and 9 closed sales in Q3, up from 7 in Q2. The average sales price was $867,058, with a median of $792,000 and an average price per square foot of $457. Median days on market were 341 days and average days to close 76 days. Closed sales edged higher and the median sales price is up from $475,000 in Q3 2025, though the properties that sold had spent longer on the market.
Abaco Vacant Land
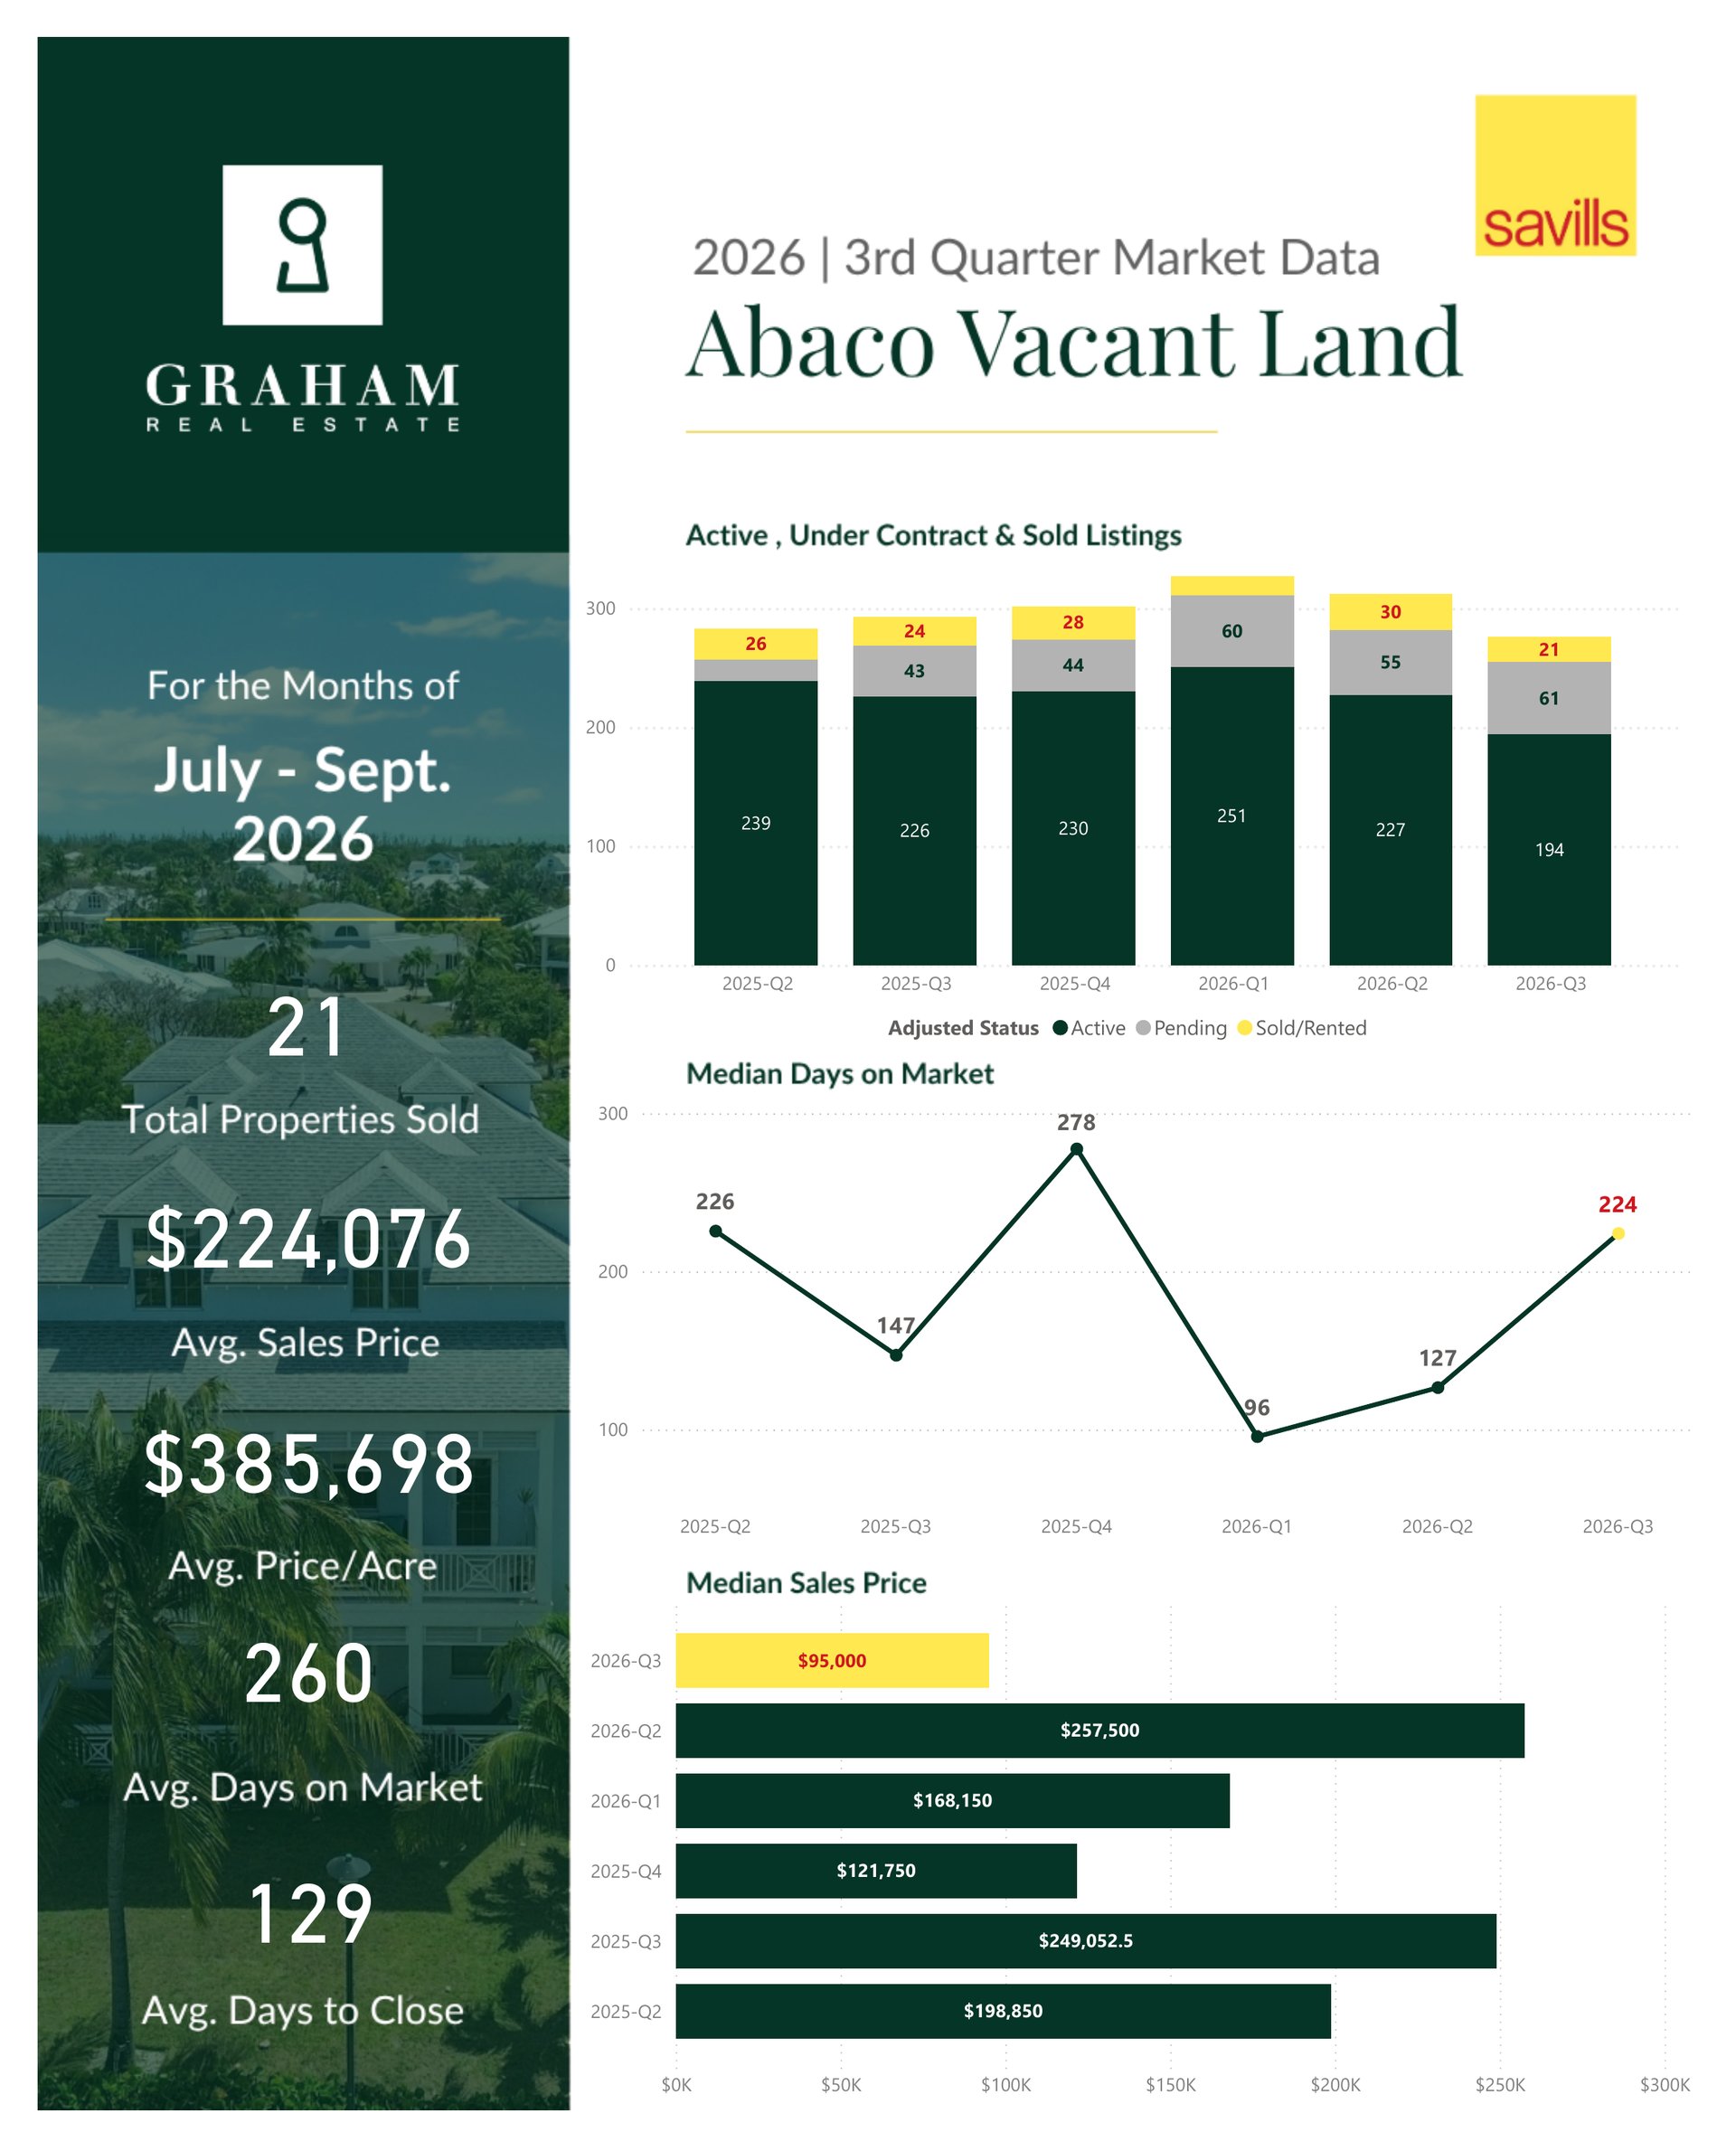
Abaco land recorded 194 active listings, 61 pending listings, and 21 closed sales in Q3, down from 30 in Q2. The average sales price was $224,076, with a median of $95,000 and an average price per acre of $385,698. Median days on market were 224 days and average days to close 129 days. Median and per-acre pricing both moved lower from Q2, while active inventory eased from 227 listings and the pending count rose to 61 from 55.
Eleuthera
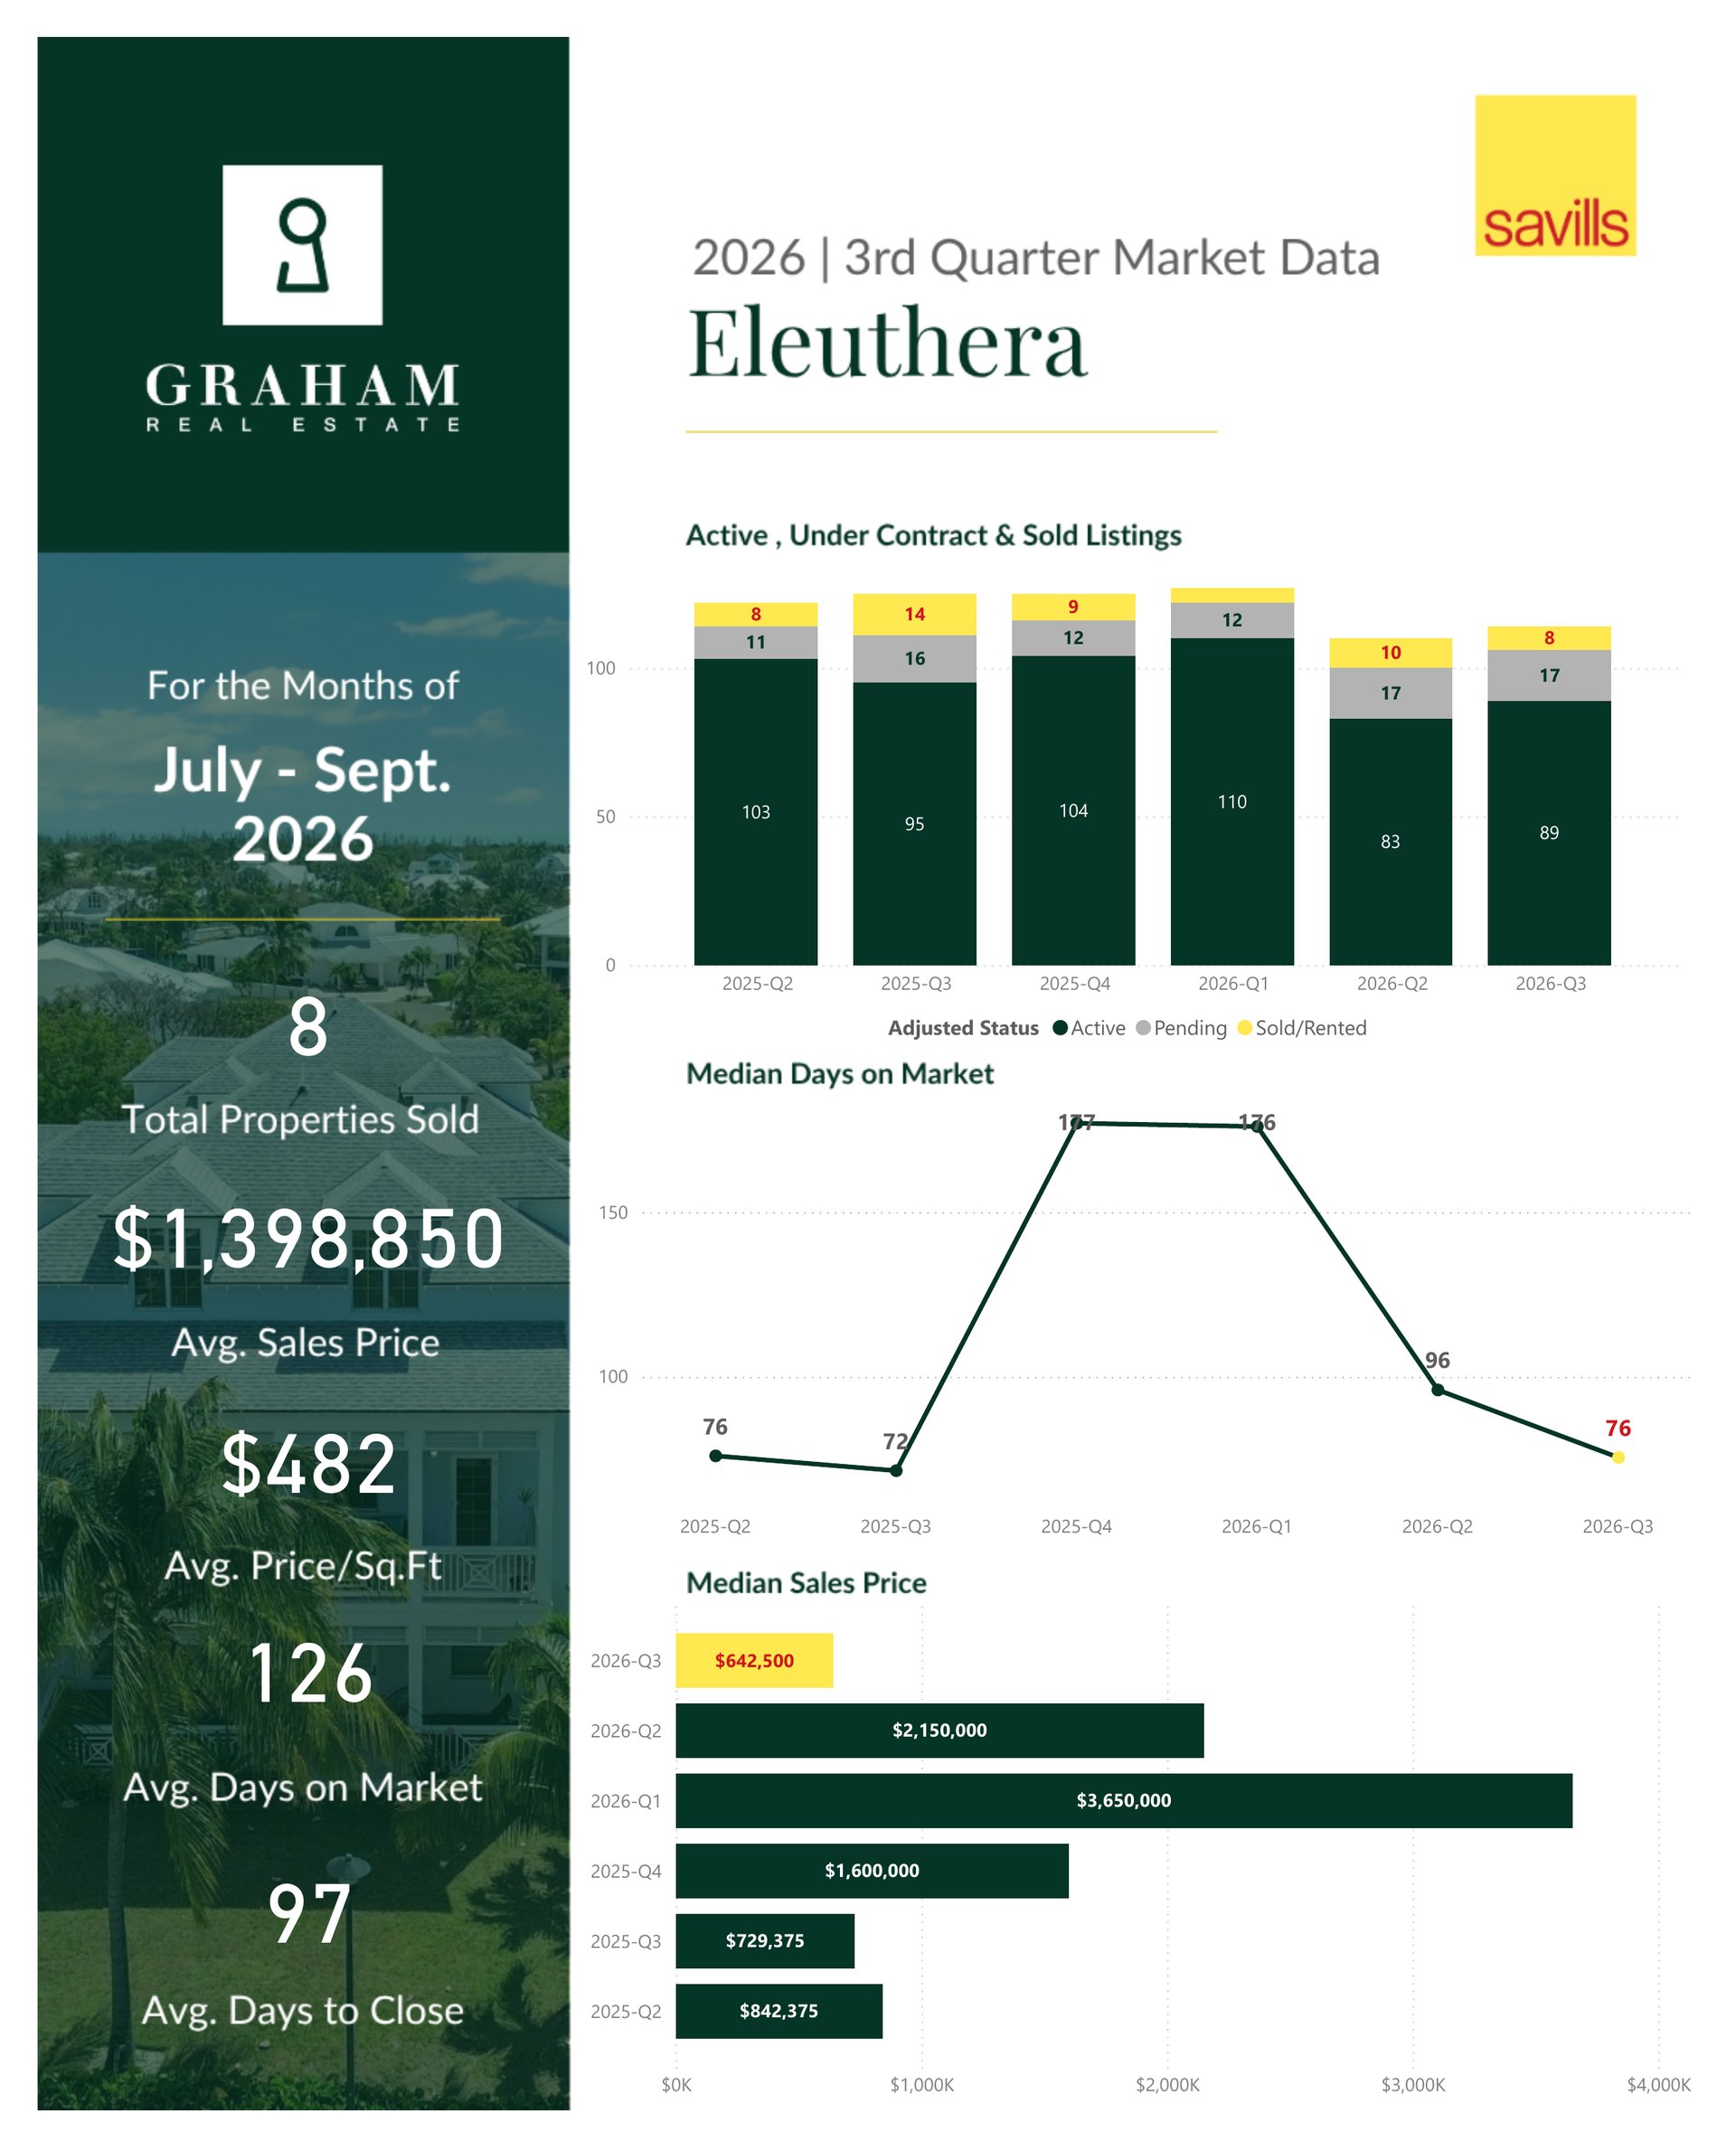
Eleuthera recorded 89 active listings, 17 pending listings, and 8 closed sales in Q3, down from 10 in Q2. The average sales price was $1,398,850, with a median of $642,500 and an average price per square foot of $482. Median days on market improved to 76 days from 96 and average days to close shortened to 97 days from 138. After a luxury-led second quarter, pricing returned to more typical levels while homes moved to contract and closing more quickly.
Harbour Island & Spanish Wells
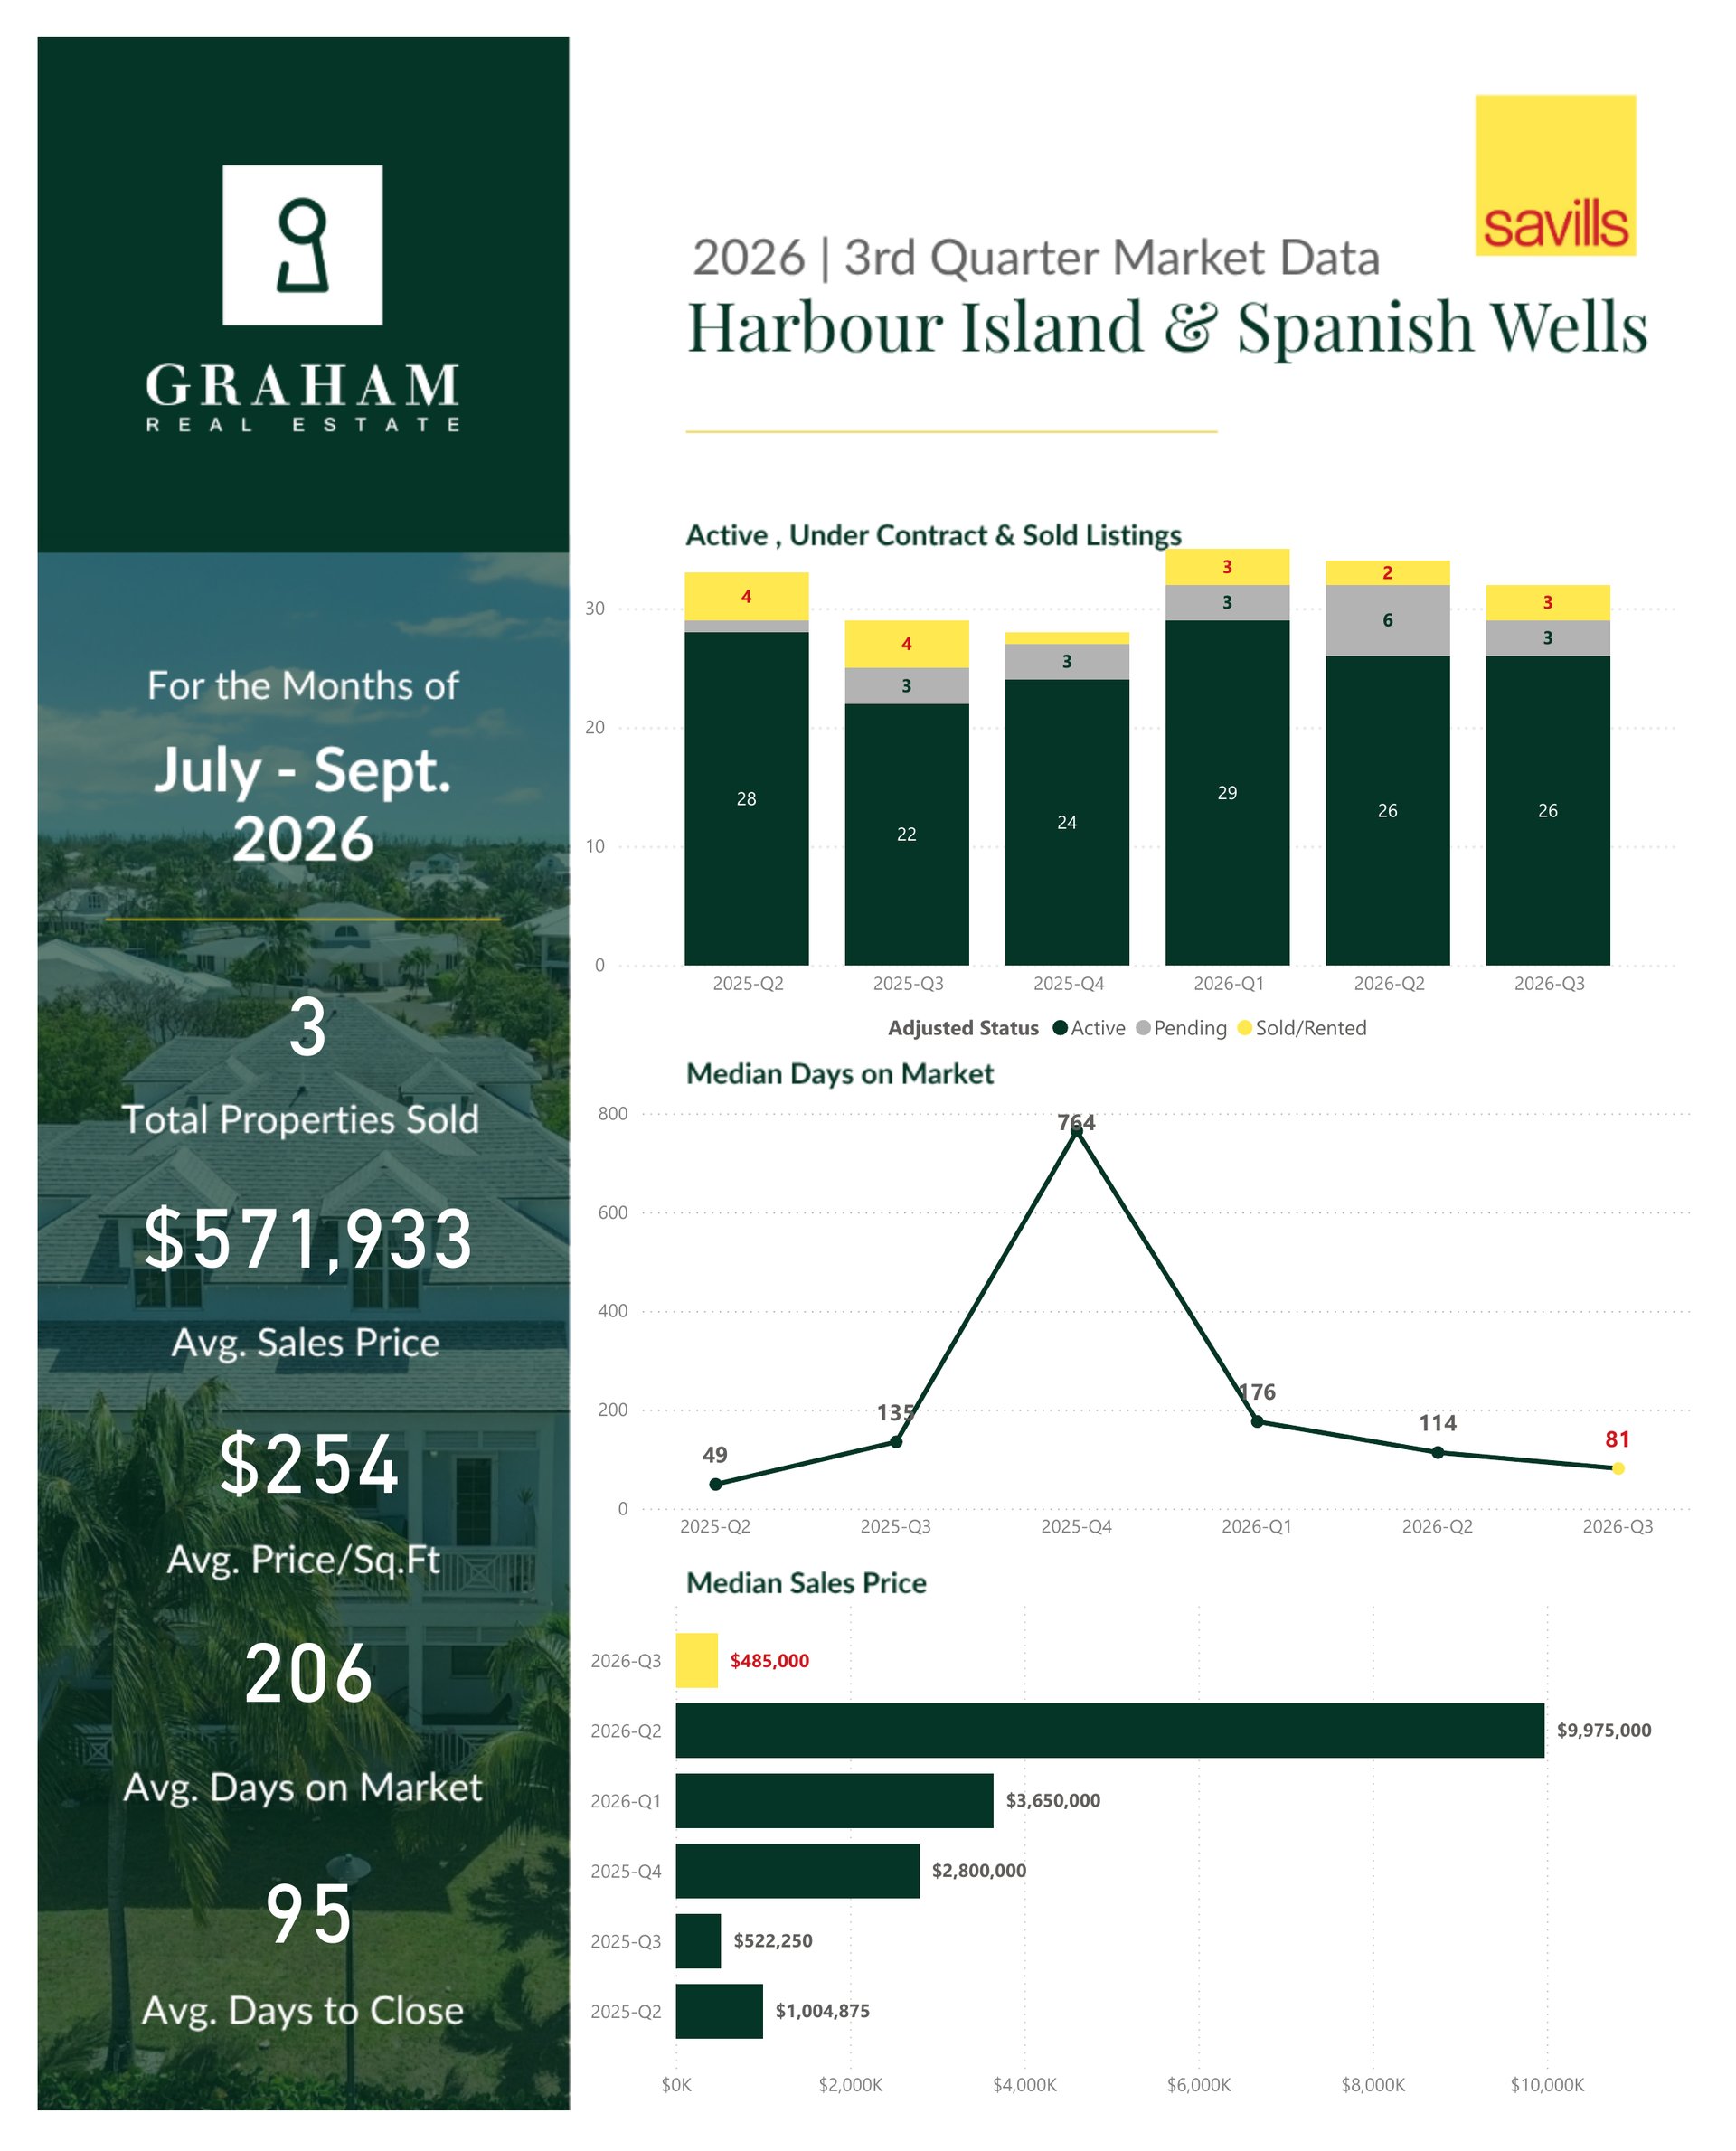
Harbour Island and Spanish Wells recorded 26 active listings, 3 pending listings, and 3 closed sales in Q3, up from 2 in Q2. The average sales price was $571,933, with a median of $485,000 and an average price per square foot of $254. Median days on market improved to 81 days from 114 and average days to close were 95 days. Activity in this market is inherently limited, and results shift significantly with the mix of properties sold.
Eleuthera Vacant Land
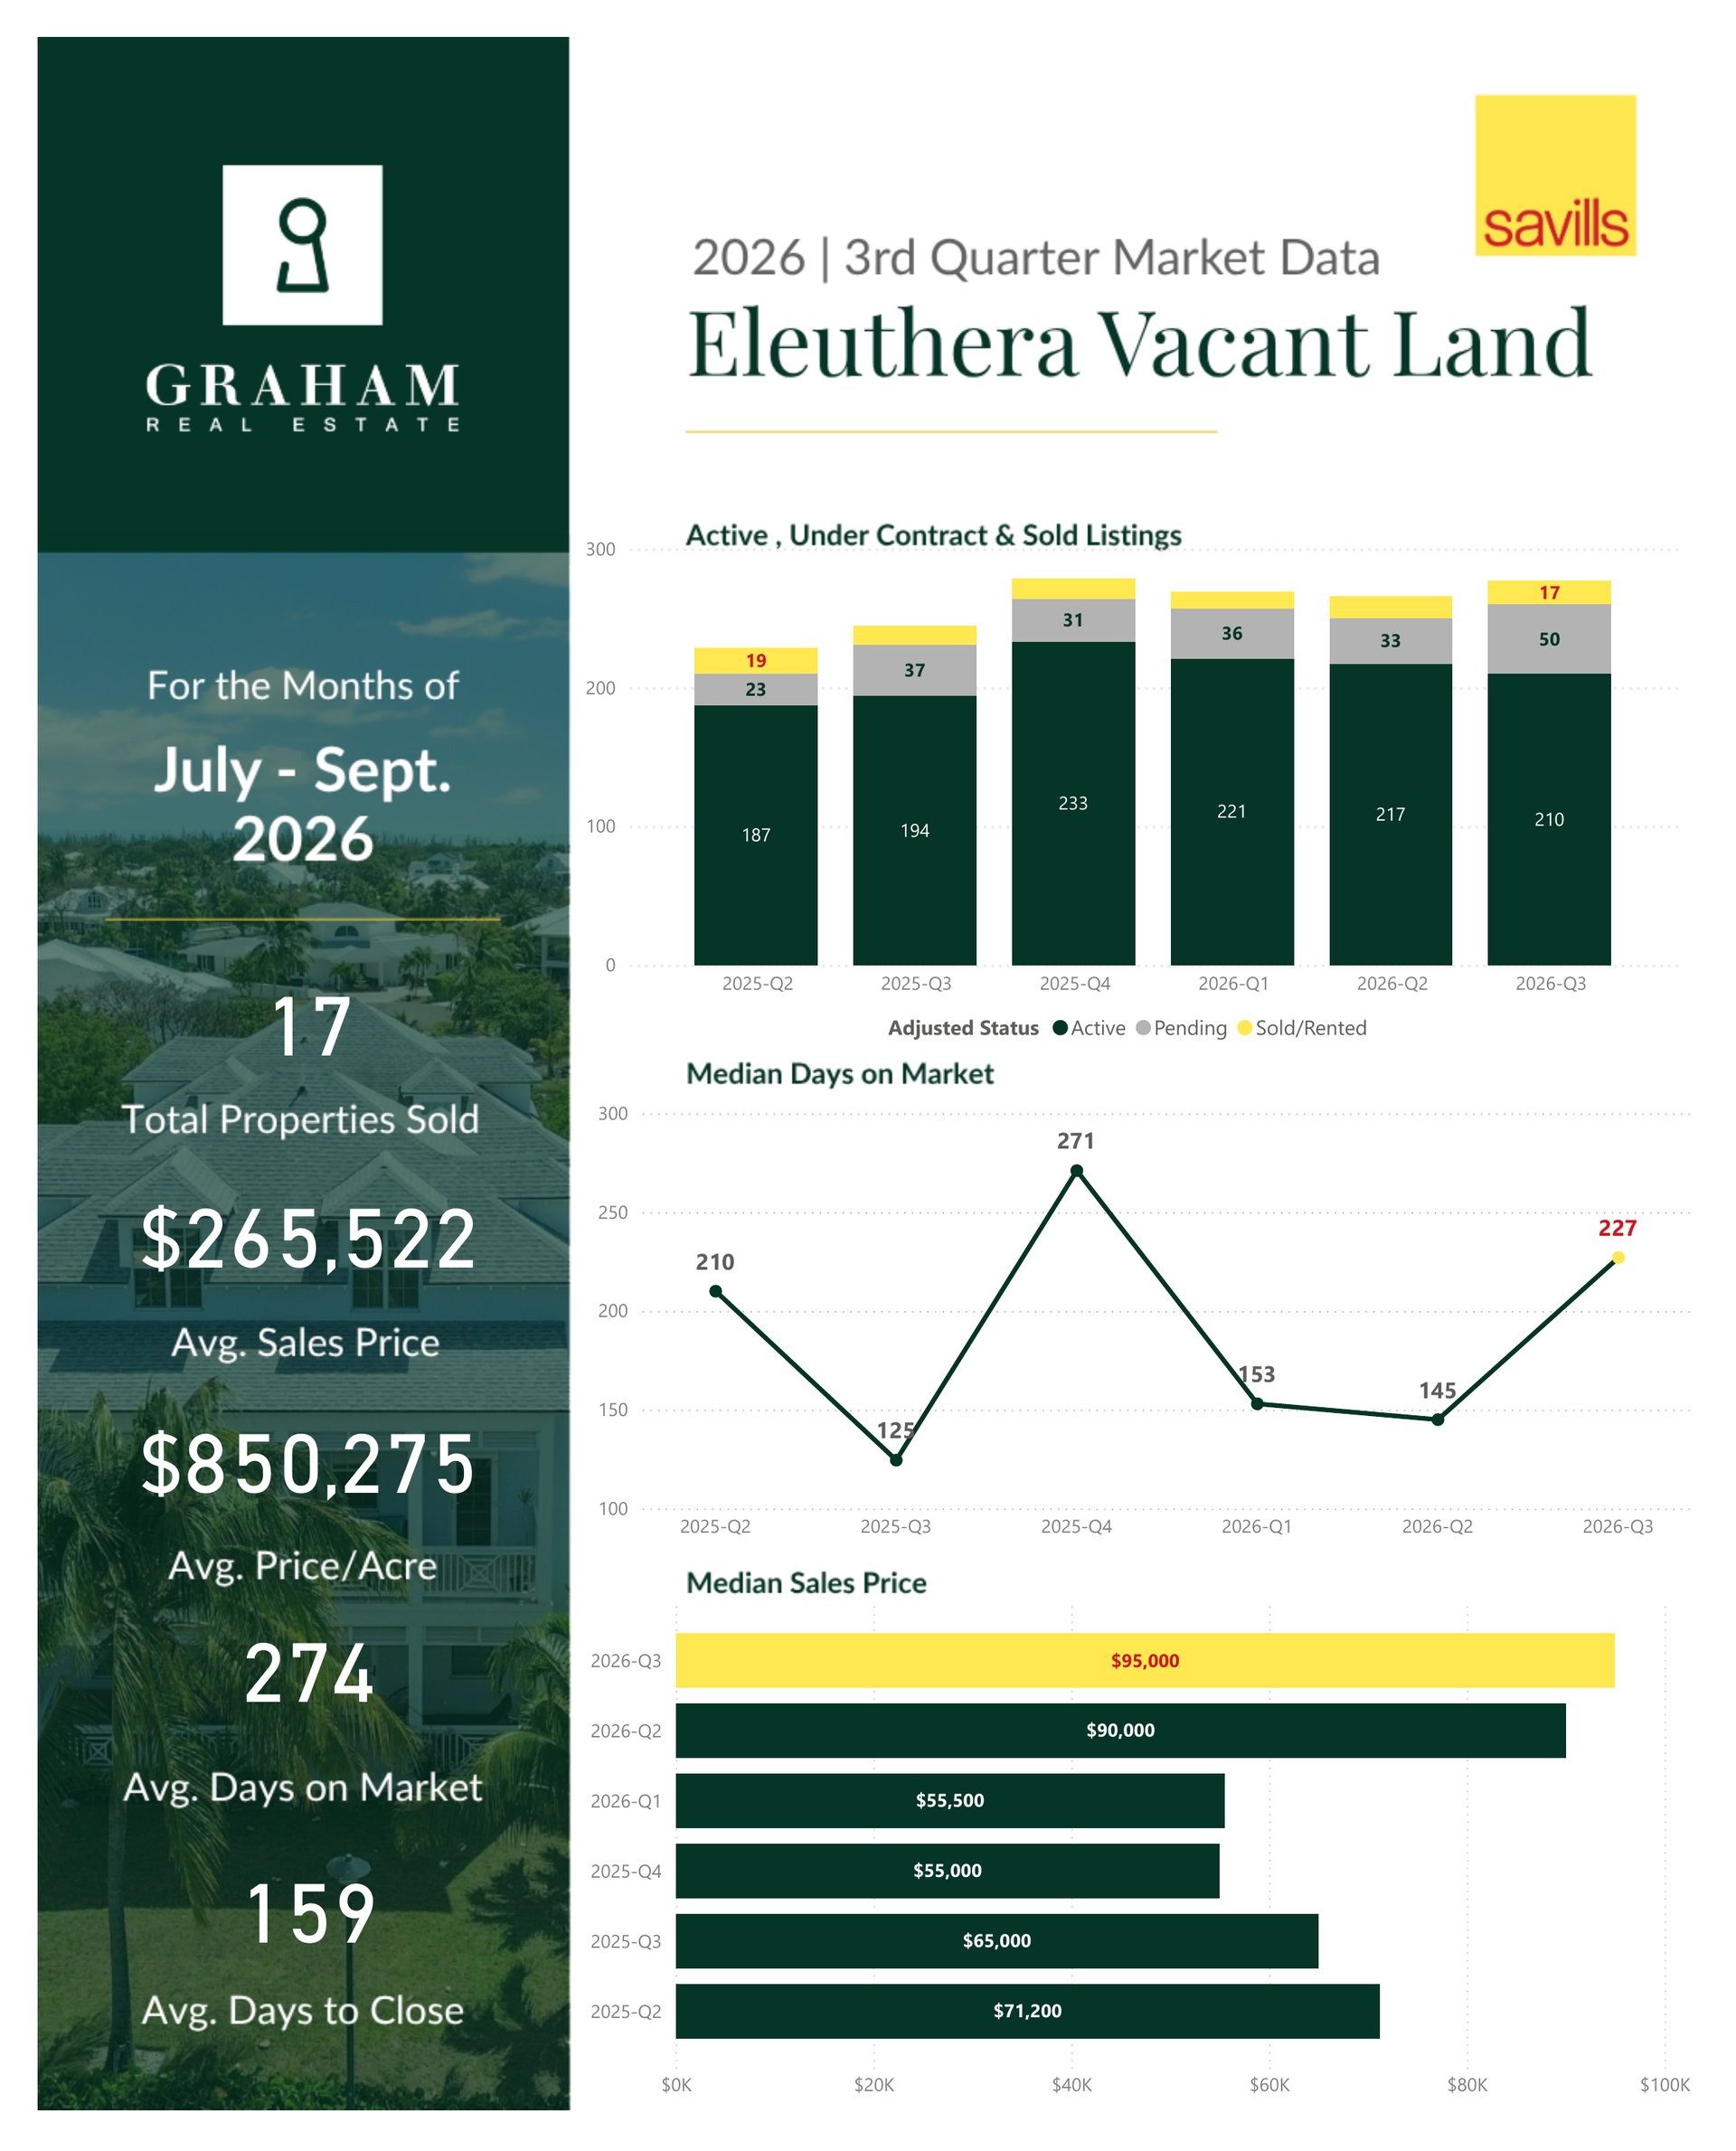
Eleuthera land recorded 210 active listings, 50 pending listings, and 17 closed sales in Q3, up from 16 in Q2. The average sales price was $265,522, with a median of $95,000 and an average price per acre of $850,275. Median days on market were 227 days and average days to close 159 days. Closed sales increased alongside firming median pricing, up from $90,000 in Q2 and $65,000 in Q3 2025, while pending listings climbed to 50 from 33.
Exuma
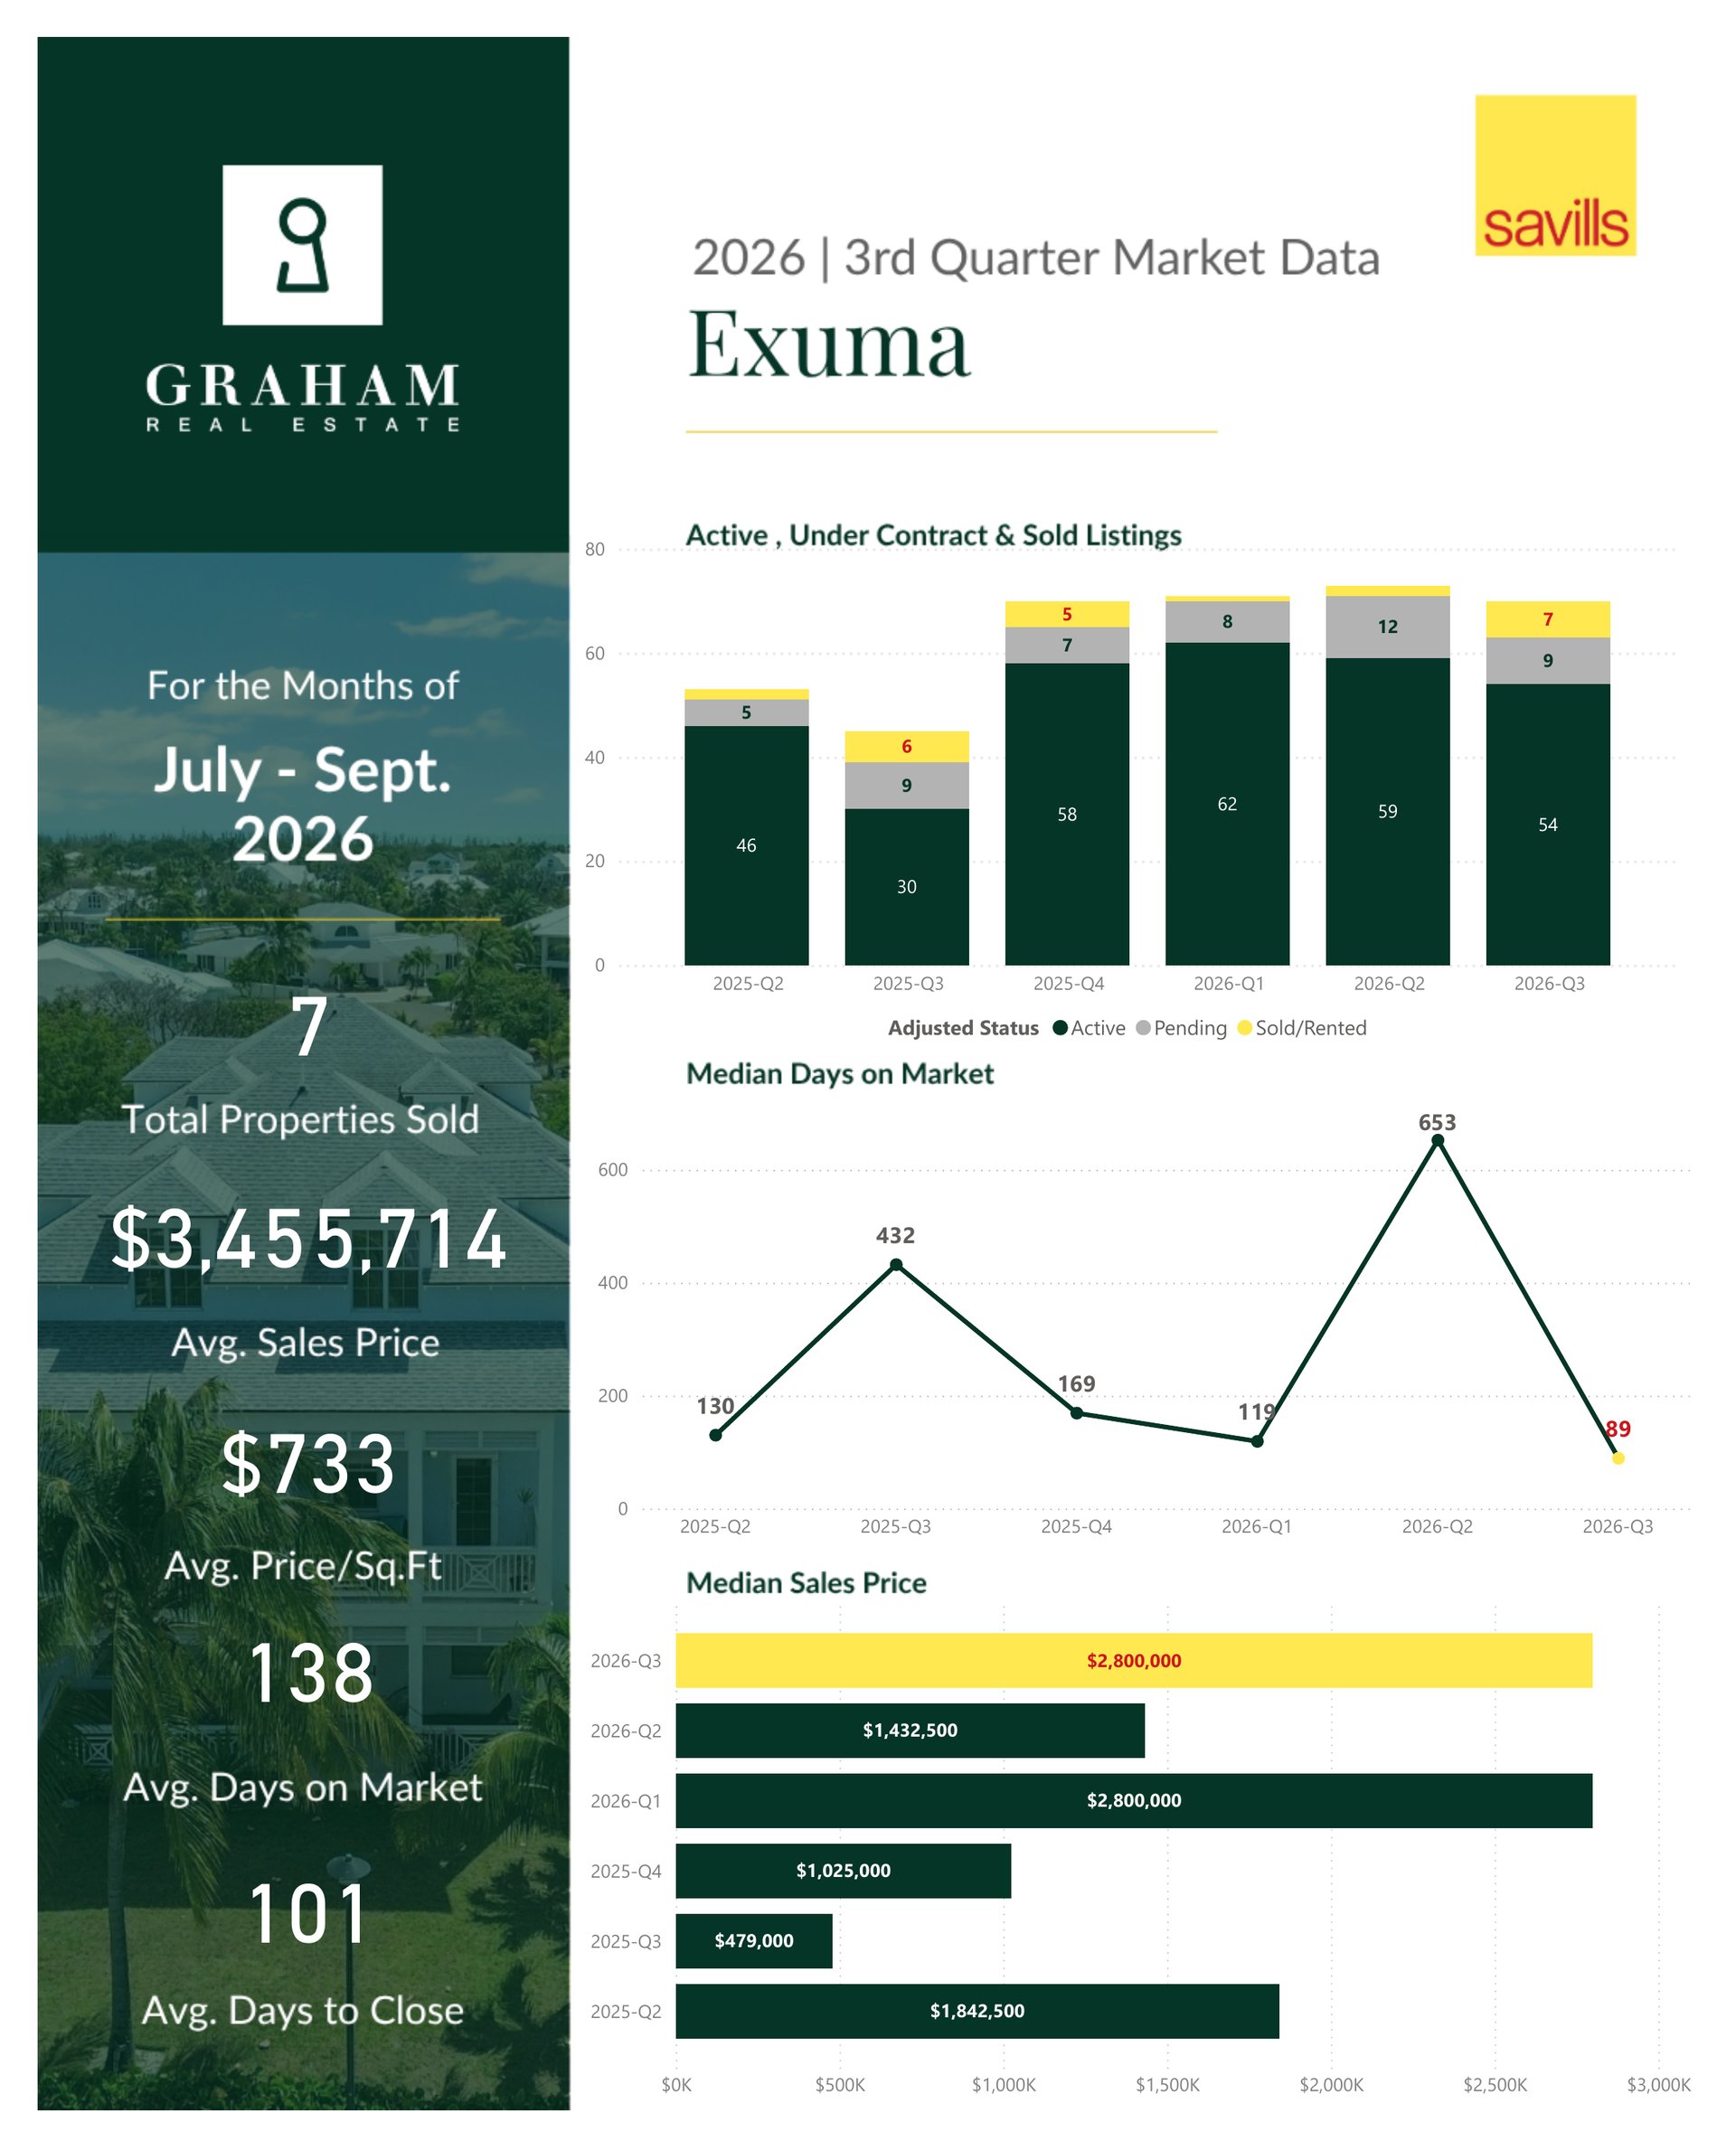
Exuma recorded 54 active listings, 9 pending listings, and 7 closed sales in Q3, up from 2 in Q2. The average sales price was $3,455,714, with a median of $2,800,000 and an average price per square foot of $733. Median days on market improved sharply to 89 days from 653 and average days to close came in at 101 days. Closed sales more than tripled from Q2, and the median sales price matches the strongest level of the past six quarters, signalling firm demand at the premium end.
Exuma Vacant Land
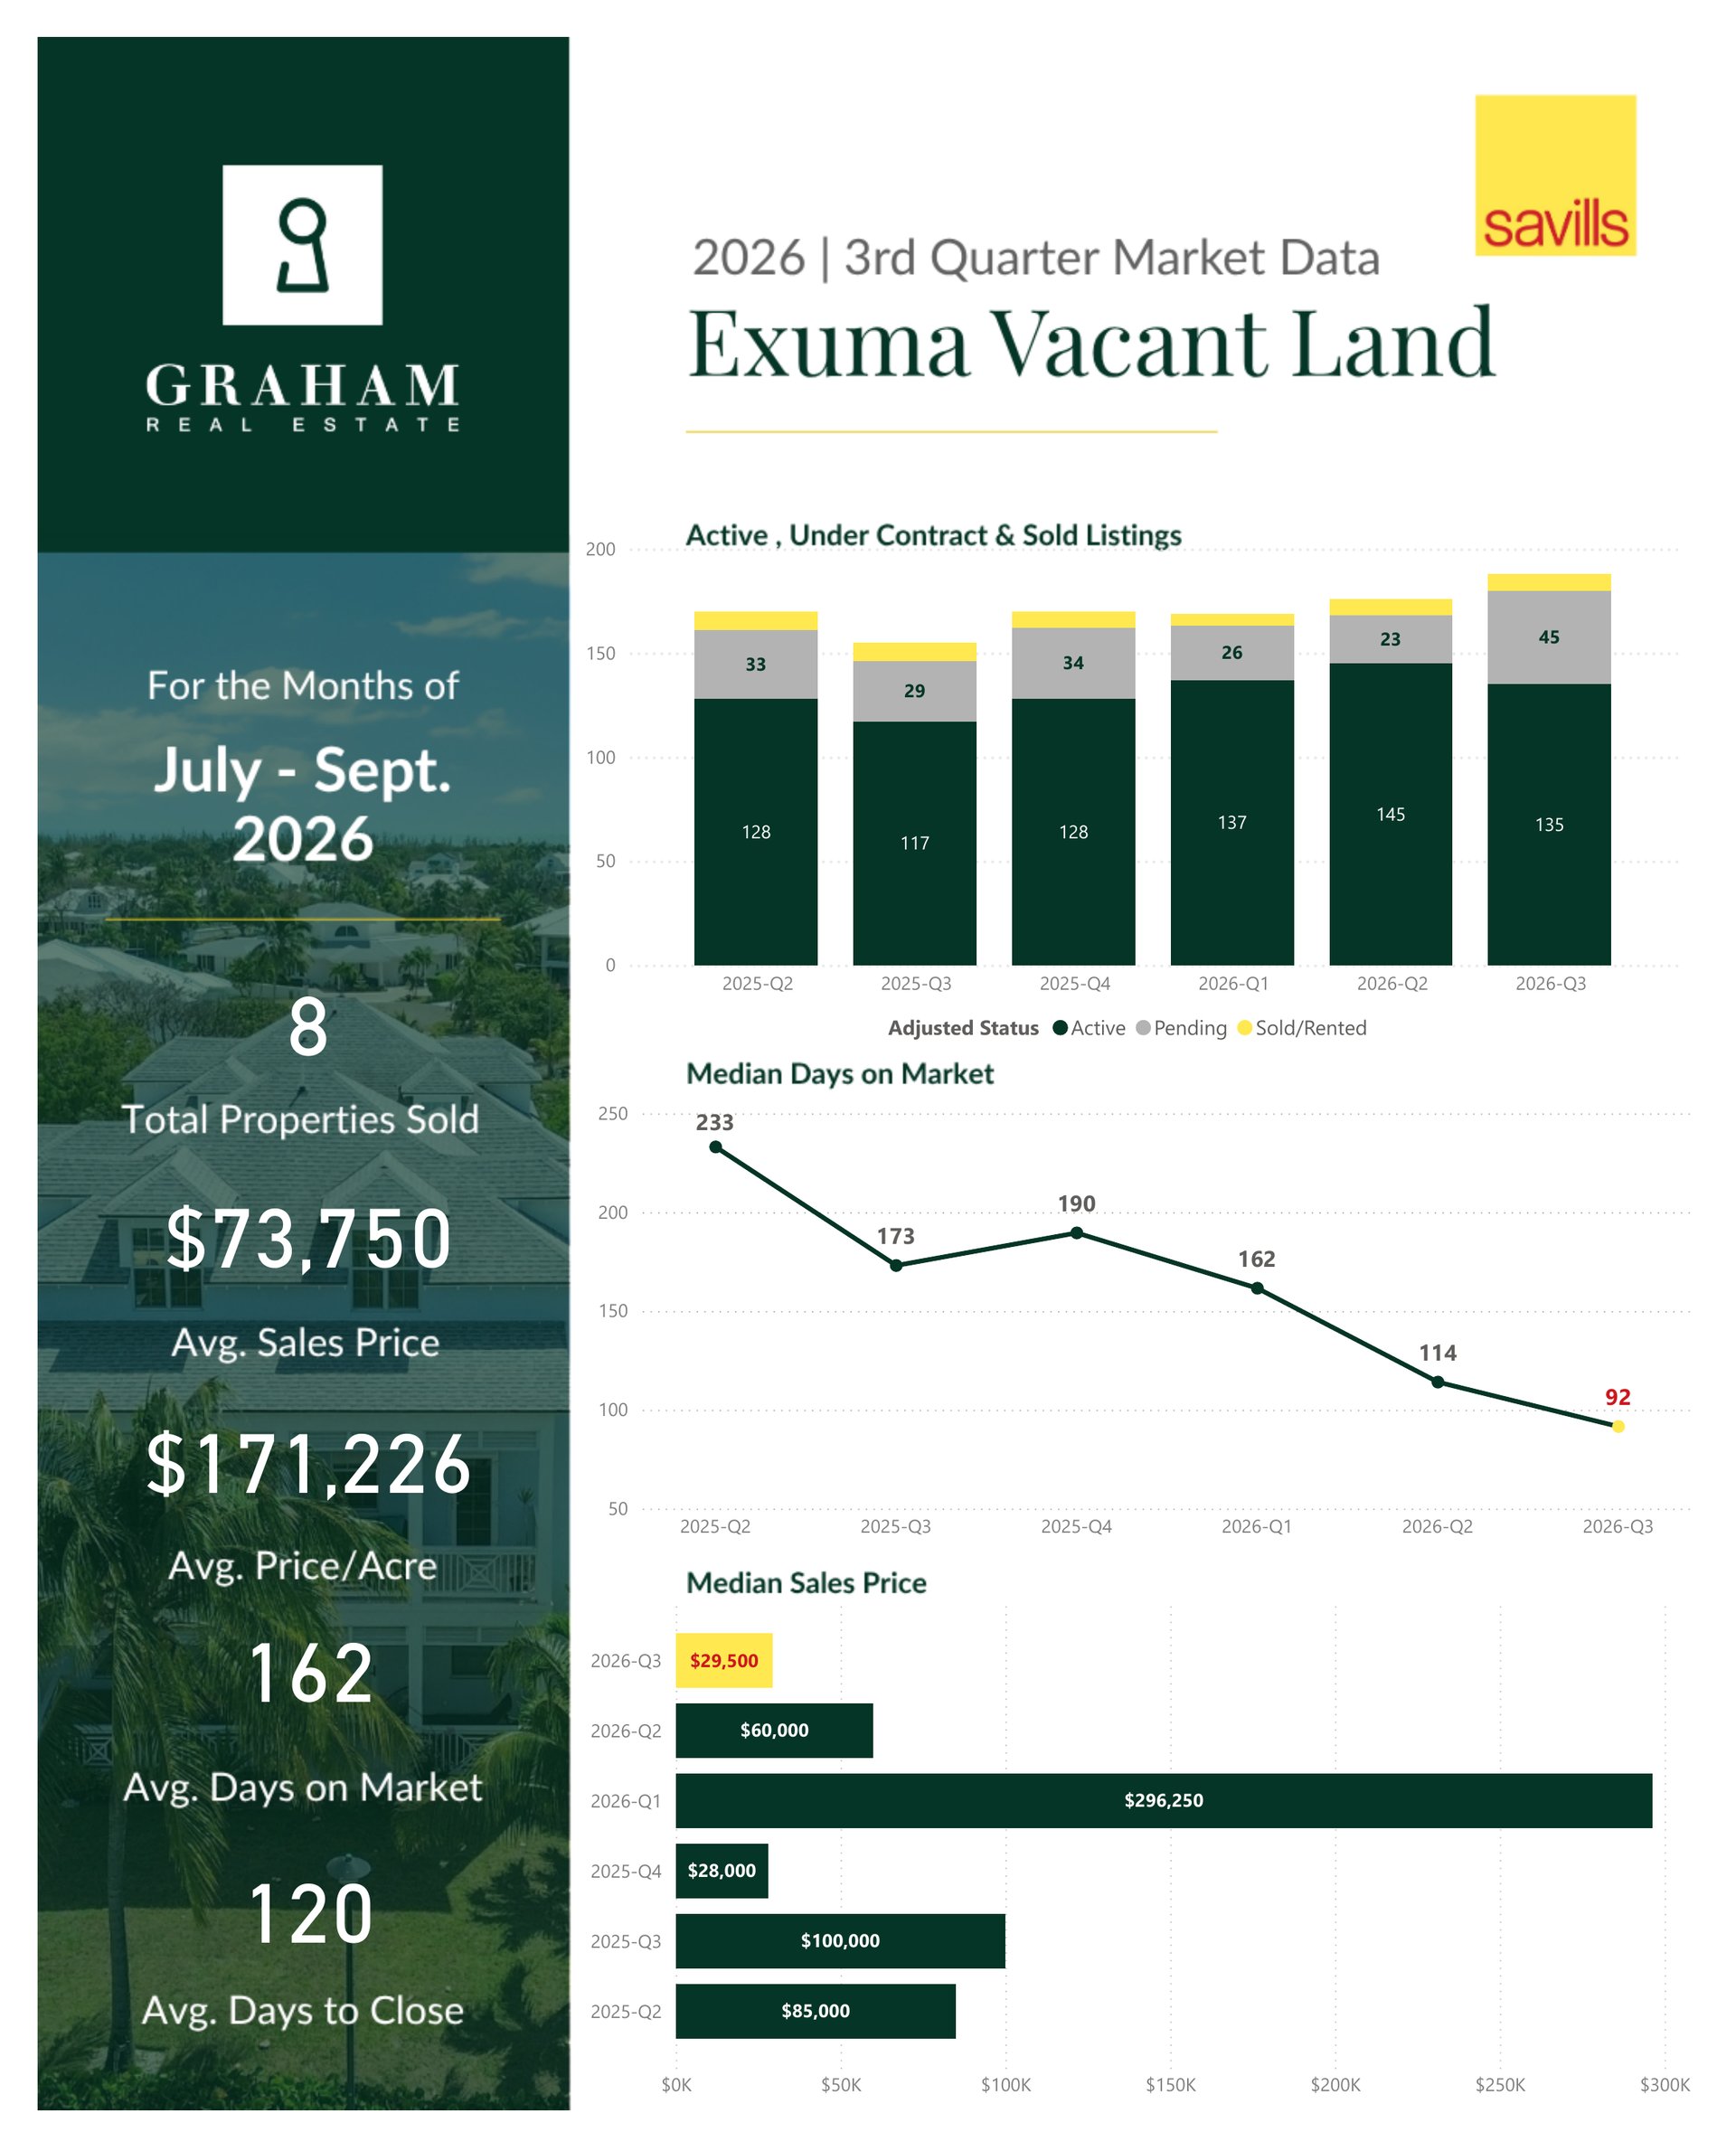
Exuma land recorded 135 active listings, 45 pending listings, and 8 closed sales in Q3. The average sales price was $73,750, with a median of $29,500 and an average price per acre of $171,226. Median days on market improved to 92 days from 114 and average days to close were 120 days. Pending listings nearly doubled from 23 in Q2, with closings concentrated at the more accessible end of the price range.
Grand Bahama
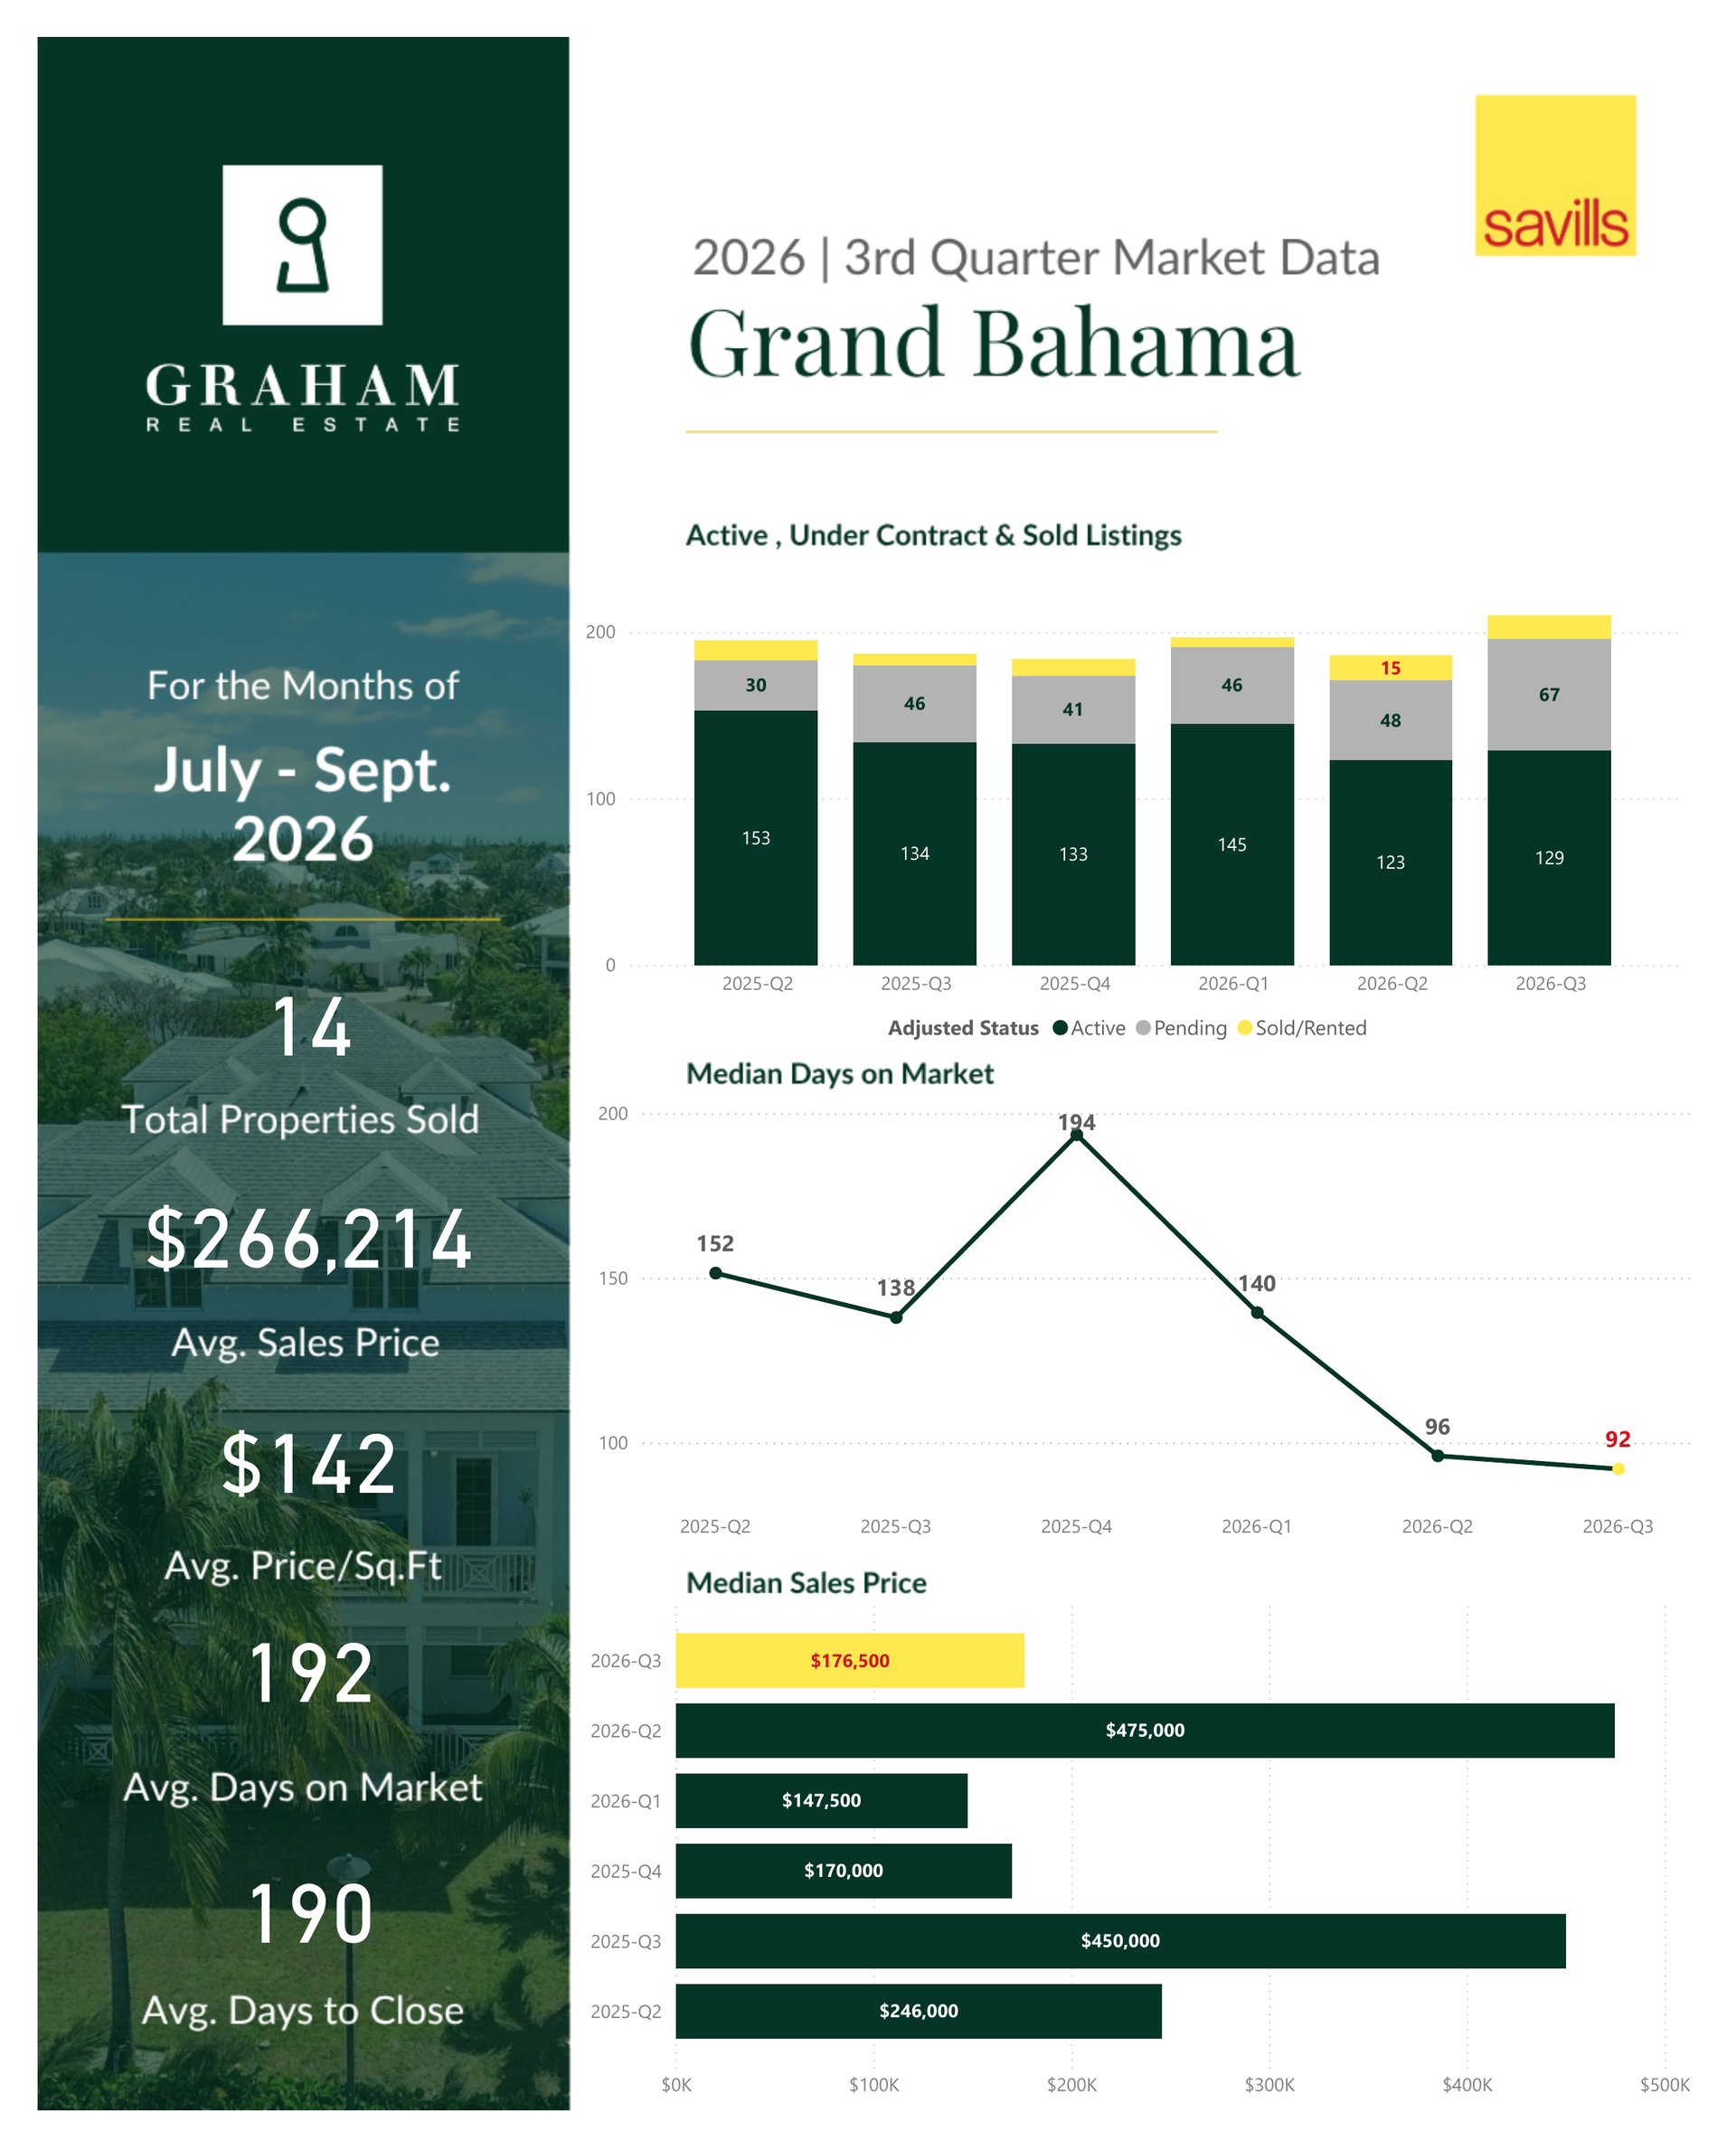
Grand Bahama recorded 129 active listings, 67 pending listings, and 14 closed sales in Q3, down from 15 in Q2. The average sales price was $266,214, with a median of $176,500 and an average price per square foot of $142. Median days on market improved to 92 days and average days to close came in at 190 days, down from 257 in Q2. After the Q2 median of $475,000, the strongest in recent quarters, pricing moved back toward the more accessible range seen previously, while pending listings rose to 67, the highest level in six quarters.
Long Island
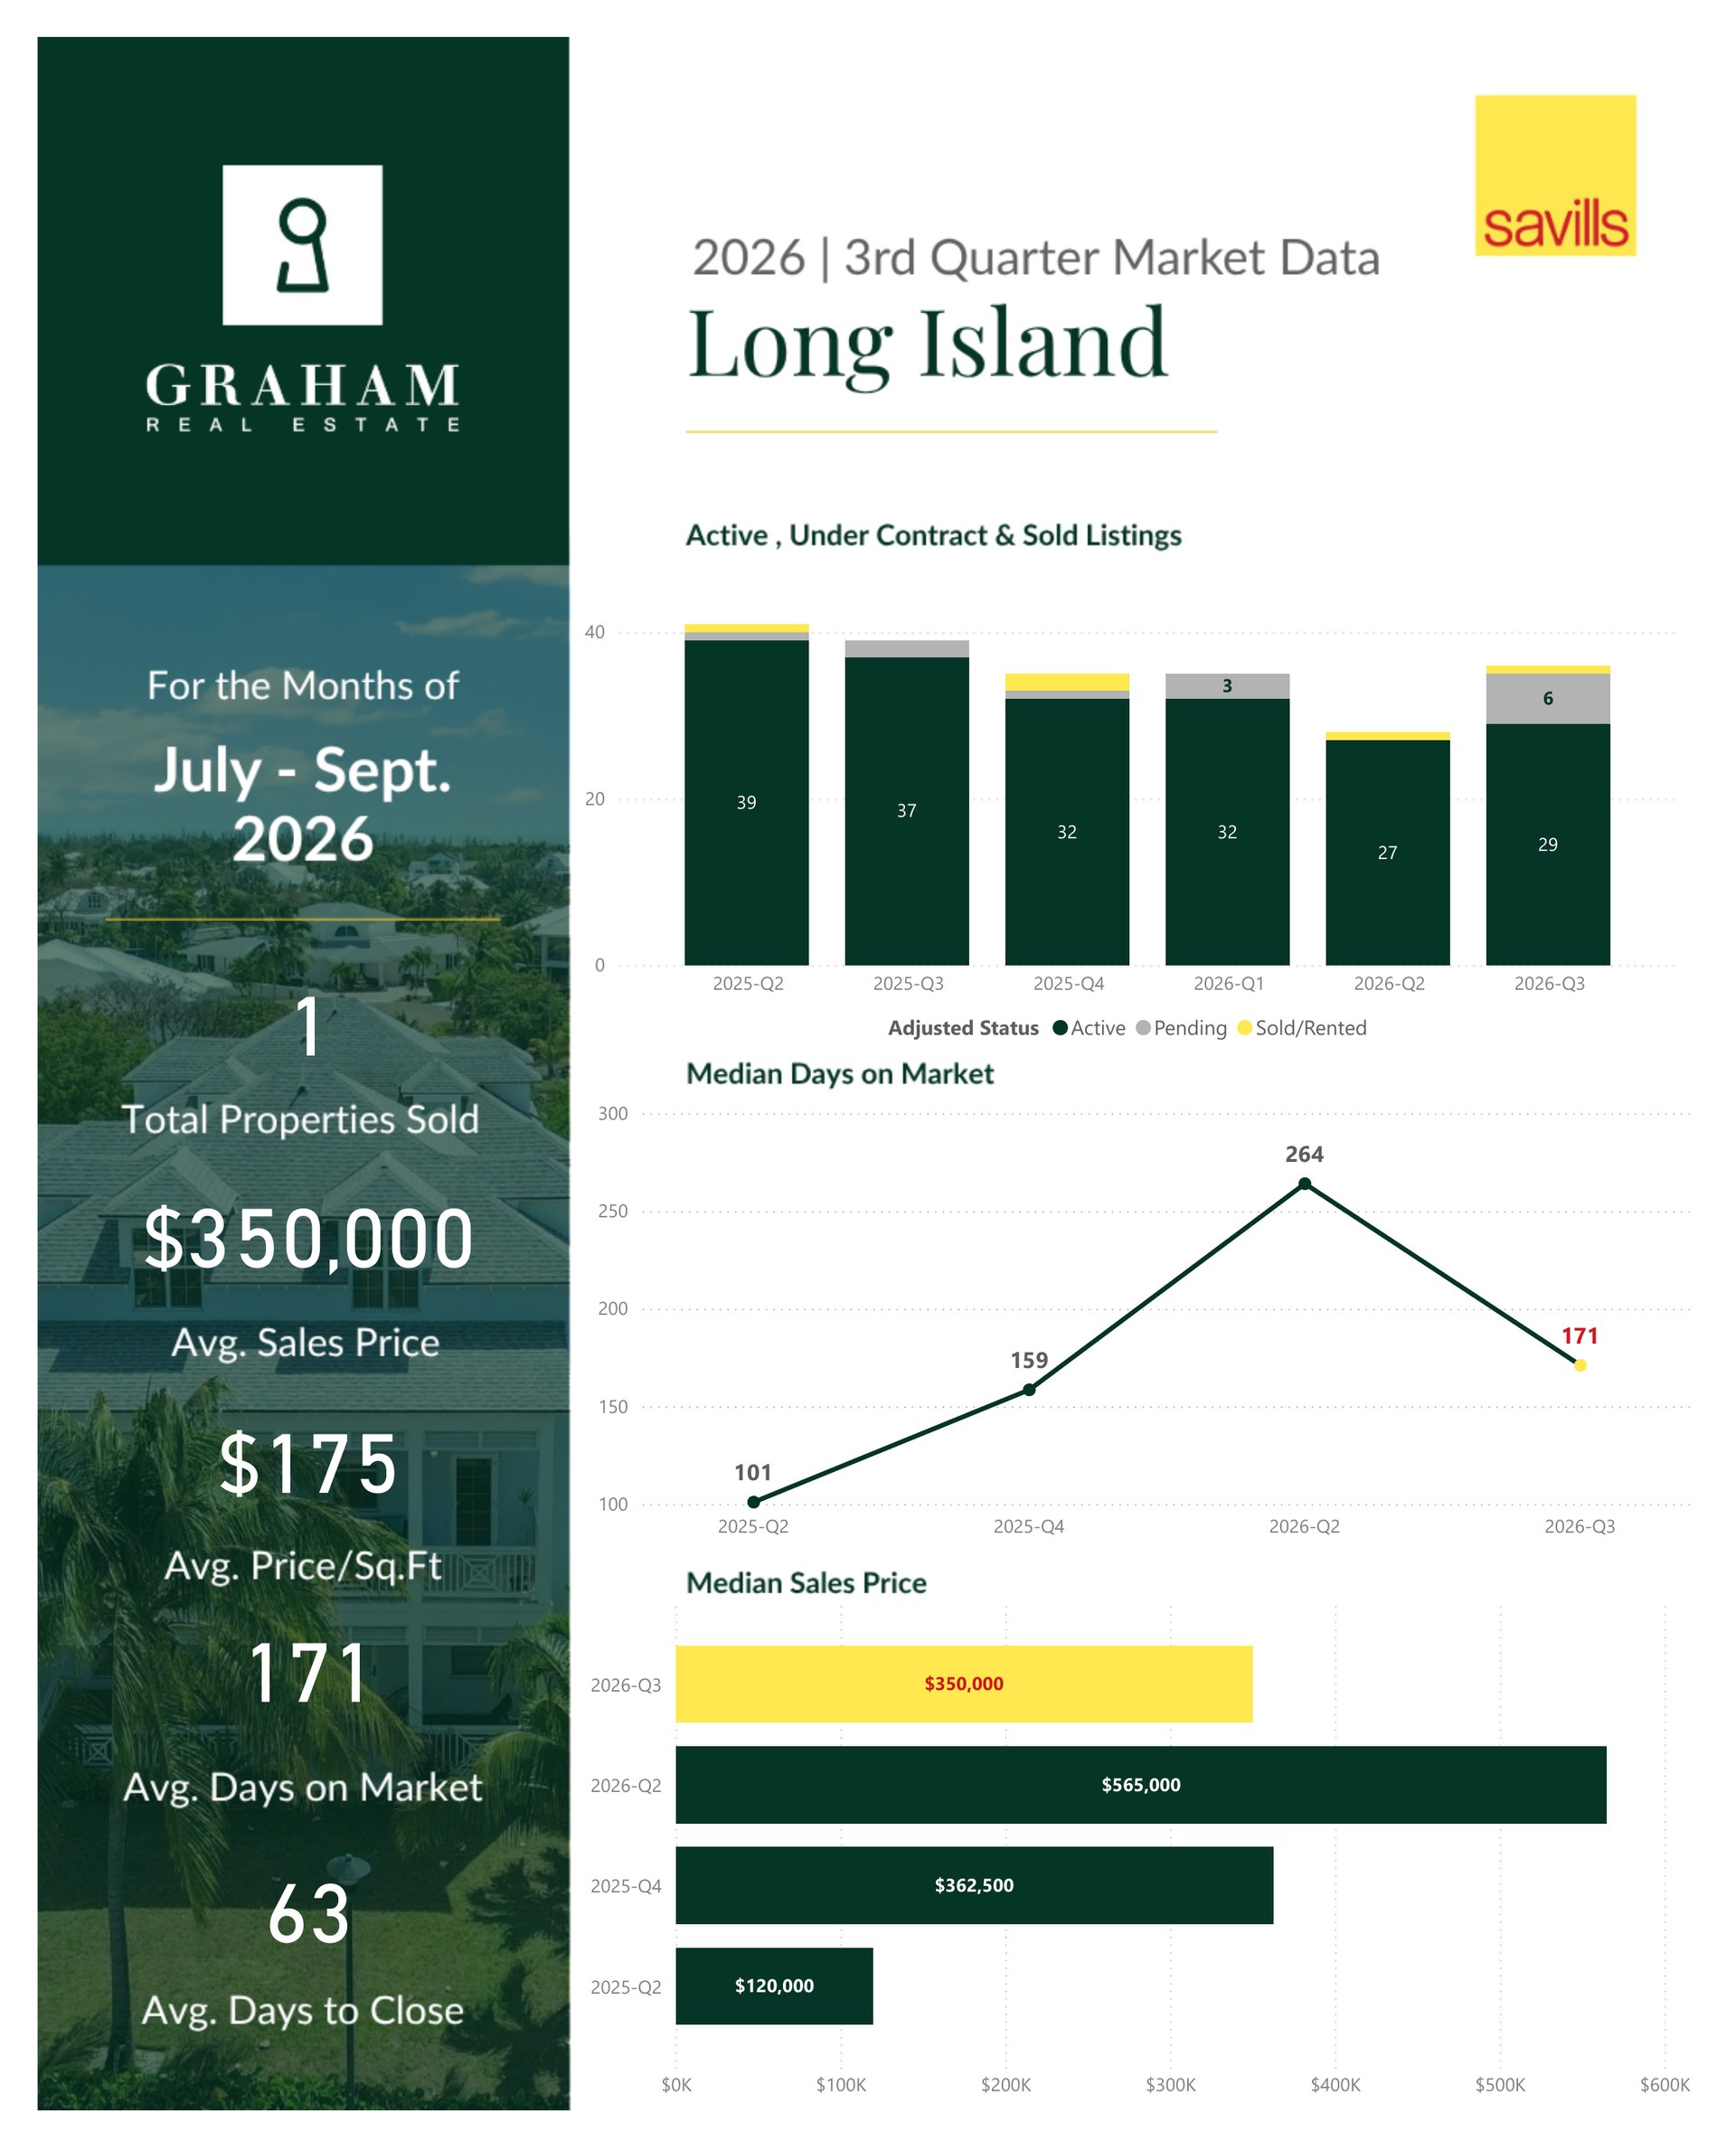
Long Island recorded 1 residential sale in Q3 at $350,000, with an average price per square foot of $175, median days on market of 171 days, and average days to close of 63 days. Active listings stood at 29, with 6 pending. While transaction volume remains limited, the island continues to attract buyers seeking larger land holdings and a quieter pace.
Long Island Vacant Land
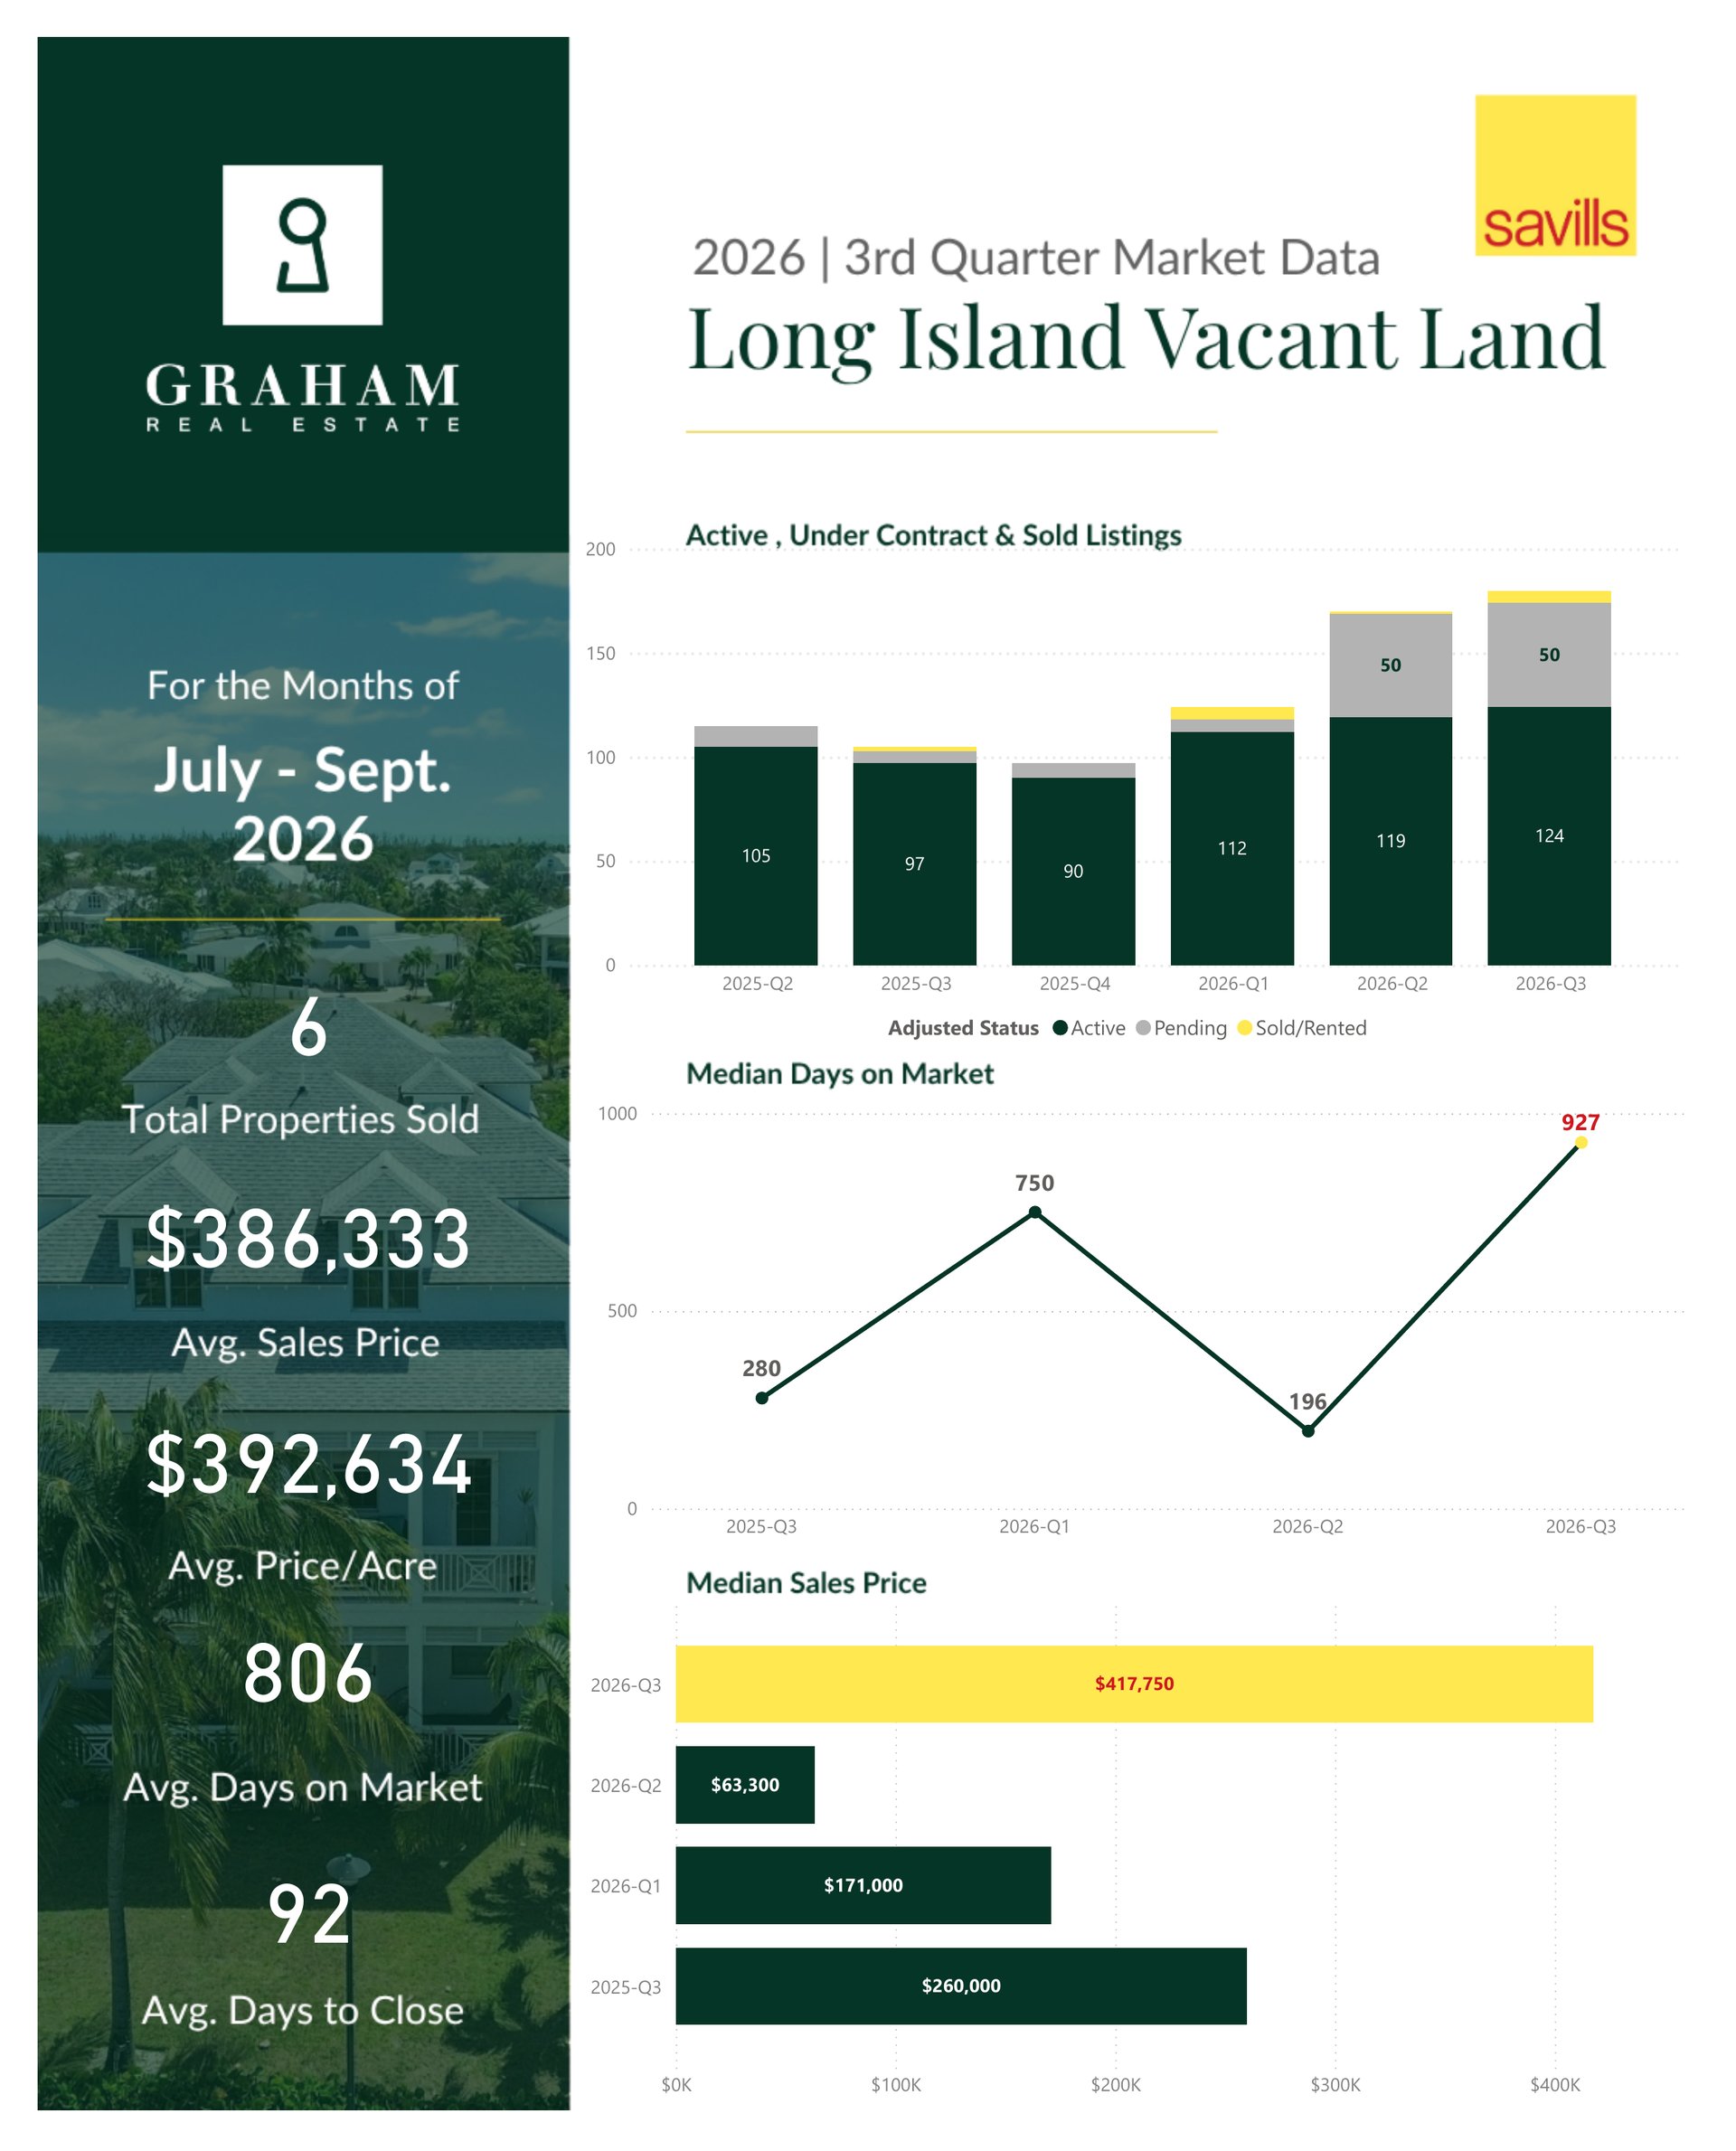
Long Island land recorded 124 active listings, 50 pending listings, and 6 closed land sales in Q3, up from 1 in Q2. The average sales price was $386,333, with a median of $417,750 and an average price per acre of $392,634. Median days on market were 927 days and average days to close 92 days, indicating the sales were of properties listed for an extended period. The pending count held at 50, level with Q2, when it was elevated by the acquisition of 43 lots within a single subdivision, which is not reflective of typical market activity but does signal growing investor interest in the island's land market as excitement grows for the reopening of the upgraded Deadman’s Cay Airport.
Conclusion
Q3 2026 combined firmer pricing and faster sales with a growing base of contracts still to close. Closed transactions eased to 98 across the GRE Islands, essentially level with Q3 2025, while the median sales price rose to $737,500 and median days on market improved to 95 days, the strongest readings in six quarters. Pending listings climbed to 344, the highest level in the same period, with New Providence, Cable Beach, West Bay Street, and Grand Bahama all adding contracts and New Providence land showing more properties under contract than actively listed. Higher-value closings in Exuma lifted pricing at the top end, while Eleuthera and the Abaco Cays settled back to more typical levels following exceptional second quarters, and Abaco land saw softer pricing. With inventory stable and a deep pipeline of contracts under negotiation, the Bahamas residential market enters Q4 well positioned for a strong close to 2026.